 Article about Fifth Third: 53 Mobile Banking
Fifth Third Mobile Banking Makes Everyday Money Checks Clearer
ViaAPK
The most valuable feature in Fifth Third: 53 Mobile Banking is not a flashy payment trick. It is the everyday view of your money: a quick way to check what is available, see recent activity, and decide whether a purchase fits before you make it. That sounds ordinary, but banking apps earn their keep in these small moments. Fifth Third’s app is most convincing when it reduces the gap between wondering about your account and knowing enough to act.
This review focuses on that money-at-a-glance experience, rather than treating every feature as equally important. The app covers routine banking jobs, but its practical value comes from making account information easy to reach and useful in context. It is a tool for short, frequent checks, not a financial adviser or a replacement for understanding your own spending.
A useful view, not just a balance
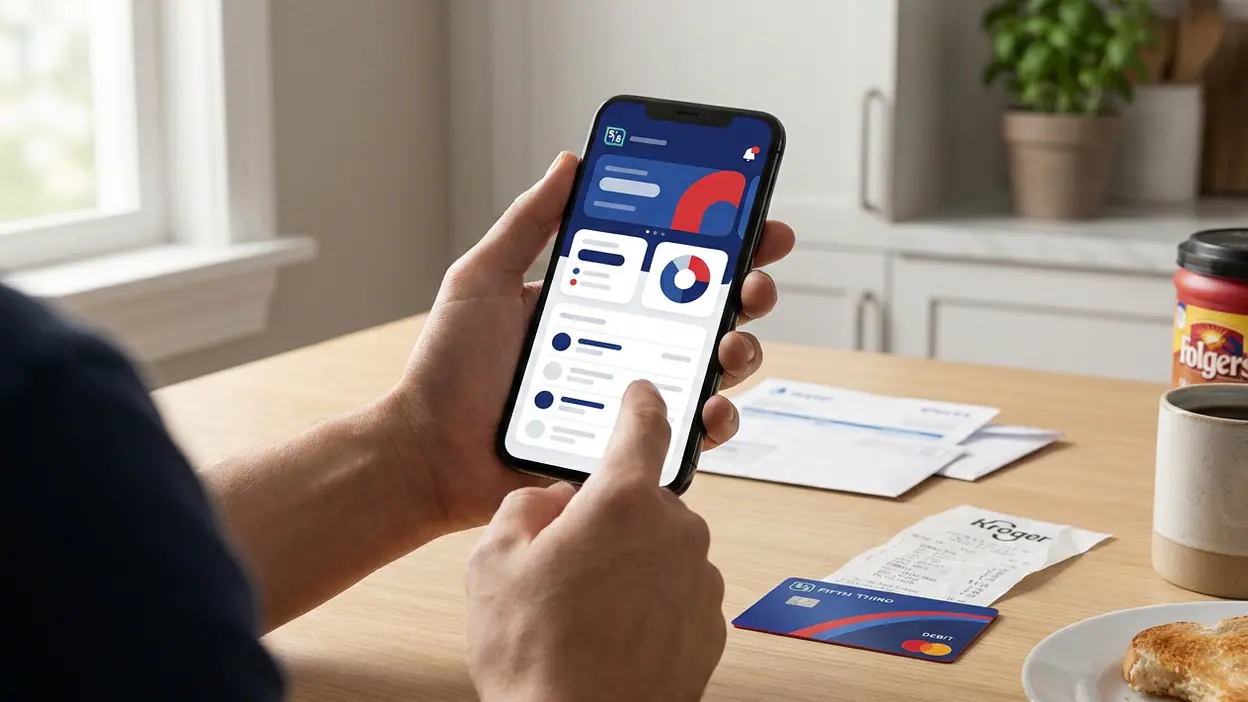
The core task is simple: open the app, identify an account, and inspect its balance and recent transactions. For a customer with checking, savings, or other Fifth Third accounts, that view can turn a vague concern into a concrete answer. Did the paycheck arrive? Has a card purchase posted? Is the available balance lower than expected? Those are the questions that make mobile banking relevant at 8 a.m. in a grocery line, not just during a formal monthly review.
The distinction between a displayed balance and money that is truly free to spend matters. Pending card activity, deposits that have not fully cleared, and scheduled payments can all affect what a customer should do next. An account screen is therefore more than a number; it is a compact record of recent movement. The app’s usefulness depends on how readily customers can connect that record to their own decisions, and Fifth Third keeps the routine check close at hand.
Recent activity also gives the balance a little explanation. A number on its own can prompt a second login or a call to customer support. A list of purchases and deposits can reveal the reason immediately, or at least help narrow it down. That is a modest convenience, but it is the sort that accumulates: a few seconds saved each time, plus less uncertainty about whether an unfamiliar charge is actually yours.
Why the small check matters
Money management often breaks down between major events. People may know their rent, paydays, and broad monthly budget, yet still make decisions in the spaces between them. A mobile account overview helps with that middle layer. Checking a balance before lunch or reviewing a transaction after a shop visit is not a full budgeting system, but it can make spending feel less detached from the account it affects.
That is the feature’s quiet behavioral value: it encourages short checks before small decisions, rather than waiting for a surprise to force attention. A customer who looks at recent activity regularly is more likely to notice a duplicate charge, a forgotten subscription, or a purchase that landed at an inconvenient time. The app does not create financial discipline by itself. It can, however, lower the effort required to stay informed.
There is a useful difference between this kind of awareness and a screen crowded with charts. A trend graph may help a customer who wants to study spending over months, but a clear account view answers an immediate question with less interpretation. Fifth Third’s central promise here is practical access: the information is most valuable when it appears at the moment a customer needs it, without requiring a spreadsheet or a long session.
The best real-world scenario
Picture a familiar errand: you are standing at a supermarket checkout, the basket is full, and you are not certain whether a bill has already drawn from checking. You open the app, inspect the account, and scan the latest activity. If the numbers look right, you can pay with more confidence. If something unexpected appears, you have a reason to pause and investigate instead of discovering the problem later.
This is where a bank app’s design has to respect both speed and caution. People want a quick answer, but they also need enough detail to avoid treating a balance as permission to spend every dollar shown. The screen is most helpful when it makes account activity legible without pretending that every transaction has settled or every upcoming obligation is already reflected. Customers still need to account for bills and pending activity that may not yet tell the whole story.
The same pattern works after a purchase. A quick look can confirm that a transaction appeared and help establish whether its amount matches the receipt. It is not a substitute for a careful dispute process, and a transaction label may not always be immediately recognizable. Still, having the activity close at hand makes the first step easier: notice, compare, and follow up if the details do not add up.
How the app can change a habit
Good mobile banking makes checking an account feel less like a chore and more like checking the weather: brief, repeatable, and tied to what comes next. The benefit is not that customers should stare at their finances all day. It is that a ten-second check can replace a guess. Over time, those small moments may make people quicker to spot spending patterns and less likely to rely on an old balance remembered from yesterday.
That shift matters most for people whose income or expenses vary. A fixed monthly routine is relatively easy to plan around; irregular shifts, shared household costs, and payments that arrive on different dates can make a static mental picture unreliable. A current account view gives those customers a better starting point for decisions. It cannot smooth out uneven cash flow, but it can make the changes visible sooner.
There is also a limit to this habit. Frequent account checking can become compulsive, particularly for someone who already feels anxious about money. The app is a useful reference, not a verdict on a person’s financial health. Its best role is to answer a question and let the customer move on, rather than encourage a stream of refreshing and second-guessing.
Where the design feels smart, and where it does not
The smart design choice is putting routine account information within easy reach. A banking app should not make a customer hunt through layers of menus just to establish what happened today. Fifth Third’s value is clearest when the path from opening the app to understanding an account feels direct, and when recent transactions give the displayed balance meaningful context.
Still, a tidy overview can only be as clear as its transaction descriptions and account timing. A merchant name that differs from the sign on a storefront can leave a customer unsure whether a purchase is legitimate. Pending activity can also make the difference between current and available funds important. If the interface does not explain those distinctions plainly at the moment of confusion, the customer has to supply the missing context alone. That is a real shortcoming of the at-a-glance approach, not a reason to abandon it.
Another boundary is scope. Seeing account activity is not the same as receiving a complete picture of a household’s finances. Cash spending, accounts at other banks, and future obligations may all sit outside the screen. Customers who want a detailed budget, automatic categorization across institutions, or long-term financial planning may need other tools alongside Fifth Third’s app. A bank account overview should be judged for how well it handles its own job, not mistaken for a full money-management system.
How rivals frame the same problem
Many banking apps begin with a similar promise: put the account in a customer’s pocket. The useful comparison is not which one uses the most elaborate graphics, but which one answers routine questions with the least friction and the clearest explanation. A broader personal-finance app may combine outside accounts and spending categories, while a bank’s own app has a more direct relationship to its accounts and transactions. Each approach solves a different part of the problem.
That difference helps define Fifth Third’s place. It is most compelling for customers who already bank with Fifth Third and want a straightforward mobile window into those accounts. It need not imitate a budgeting platform to be worthwhile. But if a customer’s main need is an all-in-one view across several banks, transaction labeling and connected-account coverage may matter more than the convenience of checking a single institution’s balance. The right comparison depends on the task, not on a feature checklist.
Unlike entertainment apps such as Bloons TD 6 or HELLO KITTY HAPPINESS PARADE, a banking app is not trying to keep people engaged for long stretches. That is a strength. The best result is often a fast visit that resolves a concern and ends. Judging it by session length would miss the point; judging it by clarity and confidence is more revealing.
Who gets the most from it
Fifth Third customers who regularly check balances, confirm deposits, or verify card activity are the natural audience. The app is especially useful for someone who wants to make quick decisions away from a desktop and prefers to handle routine account questions independently. It also suits customers who are building the habit of looking at spending as it happens, provided they treat the screen as a helpful snapshot rather than a complete budget.
People who bank mainly elsewhere, need detailed cross-bank reporting, or want the app to coach them through long-term planning may find this feature less decisive. Its value is tied to the accounts it can show and the clarity with which it presents activity. That is a sensible boundary for a bank app, but it means the experience will feel more essential to an existing Fifth Third customer than to someone shopping for a general-purpose finance tool.
For those customers, Fifth Third: 53 Mobile Banking earns its place through a humble but important job: making the next money decision less of a guess. Its account overview will not solve budgeting, explain every unfamiliar merchant, or remove the need to plan for pending payments. It does make everyday banking easier to check, and that is the feature that matters most here. The verdict is straightforward: a practical companion for routine Fifth Third account management, strongest when you want a quick, grounded picture of what has happened and what you can sensibly do next.