Acorns: Invest For Your Future
For Android and iOSFree·User Rating
 Analysis by ViaAPK
I approach investing differently when it feels like a separate project: a decision to research, money to set aside, and a new routine to maintain. Acorns: Invest For Your Future is built around making that routine feel smaller. Rather than asking me to begin with a large, carefully timed investment, it focuses on gradual contributions and a guided path into personal finance. That makes it interesting for people who want to get started but find the usual brokerage experience intimidating.
There is an important distinction, though: convenience is not the same as a complete financial plan. Acorns can make investing feel more approachable, but it does not remove market risk or make spare change a substitute for an emergency fund. I would think of it as a way to build an investing habit, not as a shortcut to guaranteed growth.
From everyday spending to an investing routine
I find the most useful way to judge this workflow is to decide what each contribution is meant to do before it starts: round-ups can make investing feel habitual, while scheduled deposits give me a clearer sense of pace. That distinction helps me notice whether automation is supporting my budget or quietly competing with it. Next, I’d look at how those small actions move into an account and what I should check along the way.
Starting with a manageable first step
First things first, let's talk about how easy it is to get started with Acorns. Upon downloading the app, available on both Android and iOS platforms, you're greeted with a user-friendly interface. The setup process is straightforward, asking for simple details to create your account. What I loved right off the bat is how the app is designed for everyone, even if you're a complete newbie to the world of finance.
As a finance app developed by Acorns, it has a clear beginner-friendly role. It is free to download, has an Everyone age rating, and its current version is 4.172.0, with minimum OS 9. The app was released on Oct 7, 2014; its 4.7 average comes from around 375,000 ratings, alongside around 77,000 written reviews and over 10 million installs. Those figures suggest a well-established product, but they cannot tell me whether its investing approach suits a particular budget. I would still check the account terms and make sure the routine fits my own cash flow before committing.
Turning small purchases into contributions
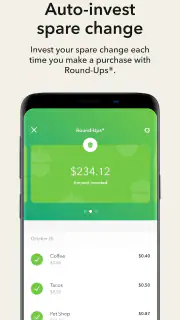
The concept of micro-investing is Acorns' unique selling point. Imagine this: every time you purchase a coffee or pay for your groceries, Acorns rounds up your transaction to the nearest dollar and invests the spare change. It's like a digital piggy bank that grows with every swipe of your card. I found this feature incredibly convenient and a no-brainer way to dip your toes into investing without even noticing.
That hands-off quality is also the key trade-off. Small round-ups can make investing feel painless, but the amounts may be modest, and their pace depends on your spending pattern. If you mostly pay in cash, or your card activity is irregular, the flow may not produce the steady contributions you had in mind. I would not treat round-ups as a savings target with a predictable finish date. Instead, I’d pair the feature with a contribution routine I can afford, then check occasionally whether the combined habit is still working for my budget.
News Worth Your Time
Brain Test 2 Suits the Stop-and-Start Rhythm of Modern Phones
Google Play Games Makes Android Gaming Easier to Navigate, Not Easier to Love
WhatsApp Under Pressure: How Well It Recovers When Messages Fail
UNO!™ Beyond the Table: How Rivalry Keeps Players Coming Back
LinkedIn: Dominating the Professional Networking Arena
Unlocking the Full Potential of Pixel Art - Color by Number
Roblox: A Creative Revolution in Gaming
Why Gallery Stands Out in the Photo App World
How Pi Network is Revolutionizing Social Cryptocurrency
Google TV's Ecosystem Strategy: Redefining Streaming
How Little Panda: Princess Makeup Thrives with New OS Updates
Why Decor Life - Home Design Game Stands Out in Creative Simulation
A practical way to use it is to start with a week of ordinary spending rather than changing how you shop to generate more round-ups. That keeps the feature in its proper role: turning normal transactions into small investing steps, not encouraging extra purchases. If the resulting contributions feel too frequent or too slow, adjust the role you expect the app to play rather than trying to spend your way toward a bigger balance.
Adding consistency and learning as you go
Aside from micro-investing, Acorns offers several other features that are worth mentioning:
- Recurring Investments: You can set up daily, weekly, or monthly recurring investments, allowing you to consistently grow your portfolio.
- Found Money: This is a rewards program where you earn bonus investments when you shop with Acorns' partner brands. It’s like getting paid to shop!
- Educational Content: Acorns provides a plethora of educational resources to help you understand the basics of investing. This is perfect for those who want to learn as they go.
Recurring contributions solve a different problem from round-ups: they let me decide in advance how much to invest and when. I would set an amount that remains comfortable after bills and essentials, then treat any round-ups as an extra rather than counting on them to meet a goal. This is a useful distinction for someone paid on a regular schedule, but anyone whose income changes from week to week should be cautious about choosing a cadence that could collide with rent, utilities, or other near-term needs.
Found Money can be a pleasant bonus, but I would not shop just to earn it. A reward tied to a purchase only makes sense if I already wanted the item and the spending fits my budget. Otherwise, the bonus can distract from the more important question: whether the purchase is worthwhile without it. Educational material can help make the investing process less opaque, but I would use it to build basic understanding, not as a replacement for reading the details of an investment or deciding whether risk is appropriate for me.
Following the money after it leaves the bank
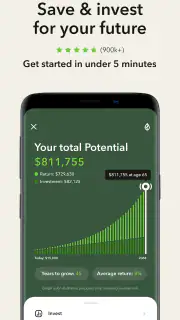
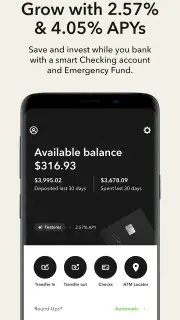
Using the app is like having a financial advisor in your pocket. The interface is intuitive and visually appealing. I especially appreciated the ability to track my investments and see real-time data on how my portfolio is performing. Plus, the "Potential" feature lets you project how much your investments could grow over time, which is a neat way to stay motivated.
The handoff from a daily purchase to an investment is where I would pay attention. A transaction is the starting point for a round-up, but it is still worth reviewing the account activity and contribution pattern rather than assuming each small amount has the same effect. The growth projection is best treated as an illustration, not a promise: future results can differ, and investment values can move down as well as up. I find projections most useful for comparing habits—such as occasional contributions versus a consistent schedule—not for predicting a precise future balance.
For a realistic routine, imagine checking the app after a normal grocery trip and a few smaller purchases. I would look at what has accumulated, make sure the activity matches what I expected, and then leave the account alone unless my budget or goals had changed. That occasional review matters because automation can hide drift: a contribution that felt negligible at first may not feel so small during an expensive month. The best workflow is not “set it and forget it forever,” but “set it, verify it, and revisit it when life changes.”
Where the simple workflow can fall short
When it comes to financial apps, security is always a top concern. Acorns uses 256-bit encryption to protect your data and partners with some of the most trusted names in the financial industry. Knowing my money and information are safe gave me the confidence to continue using the app.
Security matters, but it is only one part of deciding whether a financial app belongs in my routine. I would also consider how comfortable I am linking spending activity to an investing habit, whether the account structure and current terms suit my needs, and whether I can afford contributions without needing that money soon. Those are personal checks, not reasons to assume the app will fit everyone. Anyone who wants full control over investment selection, active trading tools, or a straightforward place to hold cash may find a conventional brokerage or savings account a better match.
Compared with manually transferring money into a brokerage account, Acorns emphasizes automation and small recurring actions instead of asking me to choose each deposit myself. That can reduce the effort of getting started, while a conventional brokerage may offer more direct control over investments and how contributions are placed. Compared with simply saving spare change in a bank account, Acorns puts the habit toward investing, which also means accepting the possibility that the balance can fluctuate. The right choice depends on whether the priority is convenience, control, or keeping near-term money stable.
I would skip this approach if my finances were so tight that even small, variable contributions could cause stress, or if I needed the money soon for bills or a planned expense. I would also look elsewhere if I already know I want to select investments myself and am comfortable managing deposits without an automatic nudge. Acorns is most appealing when the barrier is getting started, not when the real need is a guaranteed return, immediate access to a stable balance, or advanced investment control.
Who benefits most from the routine
For a beginner with a little room in the budget, the combination of round-ups, scheduled contributions, and educational content can make investing less abstract. A person who already spends by card and wants a gentle reminder to participate may find the workflow easier to maintain than opening a separate account and remembering every transfer. The app can also suit someone who prefers to check progress occasionally rather than manage each investment decision day to day.
It is less compelling for someone who rarely uses cards, has an unpredictable cash flow, or already follows a deliberate investment plan elsewhere. In those situations, the automatic round-up may be too small or inconsistent to add much, while a self-directed account can make it easier to keep contributions aligned with a broader strategy. I would compare the current account terms and any costs before deciding, since a free download does not by itself establish what ongoing use may cost.
One useful test is to decide what success means before opening the app: building a first investing habit, learning basic concepts, or creating a consistent contribution schedule. Then check after a while whether the app is helping with that specific goal. If I cannot explain what the recurring amount is for, or the round-ups are arriving at an uncomfortable time, I would pause and revisit the budget rather than letting automation make the decision for me.
My verdict on making it part of everyday life
In conclusion, Acorns: Invest For Your Future is an excellent app for anyone looking to ease into the world of investing. Its innovative approach to micro-investing, combined with educational resources and a user-friendly interface, make it a standout in the financial app space. Whether you're a seasoned investor or just starting out, Acorns offers a convenient, low-pressure way to grow your wealth over time. So, why not give it a try and watch your pennies turn into potential?
My more measured recommendation is to try it only if automation solves a real problem for you and you have money you can leave invested through market ups and downs. Keep the routine modest, do not spend extra to chase rewards, and check that scheduled contributions still suit your budget. Acorns: Invest For Your Future makes the most sense as a low-friction starting point for building an investing habit; it is not a replacement for emergency savings, careful planning, or a more hands-on brokerage when those are what you need.
Pros
- Easy to use interface
- Automated saving and investing
- Low fees for beginners
- Diverse investment options
- Educational resources available
Cons
- Limited customization options
- Not ideal for advanced investors
- Requires bank account linking
- Limited customer support
- No direct stock investments
FAQ's for Acorns: Invest For Your Future
What is Acorns: Invest For Your Future and how does it work?
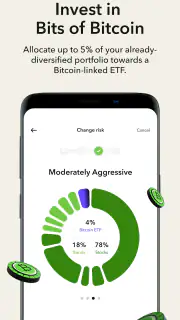
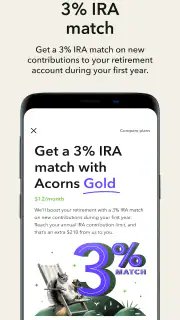
Acorns: Invest For Your Future is a mobile app that simplifies investing by rounding up your everyday purchases and investing the spare change into diversified portfolios. It uses automated features to help you build wealth over time, making it a perfect choice for beginners or those looking to invest with minimal effort. The app offers various account types such as individual taxable accounts, IRAs, and even custodial accounts for children.
Is Acorns safe to use for investing my money?
Yes, Acorns is considered safe for investing. The app uses bank-level security and data encryption to protect your information. Additionally, Acorns is a member of the Securities Investor Protection Corporation (SIPC), which protects securities customers of its members up to $500,000, including $250,000 for claims for cash. The investments are also insured and regulated to ensure user protection.
How much does it cost to use Acorns and are there any hidden fees?
Acorns offers a subscription-based model with several pricing tiers starting at $3 per month for an individual account. There are no hidden fees, but users should be aware of the standard expense ratios charged by the ETFs in which they invest. Acorns also provides family plans at $5 per month, offering additional features like custodial accounts for kids.
Can I withdraw money from my Acorns account anytime I want?
Yes, you can withdraw money from your Acorns account at any time. However, it's important to note that the withdrawal process can take 3-6 business days to complete. There are no withdrawal fees, but selling investments may involve costs related to capital gains taxes, which users should consider before withdrawing funds.
What are the benefits of using Acorns compared to traditional investment methods?
Acorns offers several advantages over traditional investing methods, including ease of use, low starting costs, and automated investment features. It allows users to start investing with just a few dollars, making it accessible to everyone. The app also provides educational content to help users understand investing better and offers a seamless experience through its mobile platform, making it ideal for busy individuals.