
Acorns Early: Kids Money App
Android OnlyFree·User Rating
 Analysis by ViaAPK
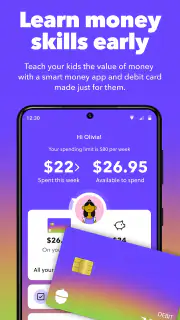
Teaching a child about money is usually easier when the lesson is connected to a real habit, not just a conversation about saving. That is the idea I found most interesting in Acorns Early: Kids Money App. It is a finance app from Acorns built around a smart investing plan for children and teenagers, with the larger goal of helping families make financial wellness part of everyday life.
I approached it less like a traditional investing tool and more like a parent-facing way to introduce long-term thinking. The important distinction is that the app is not simply asking a young person to watch a balance or memorize financial terms. Its appeal is in turning small, repeated decisions into an opportunity to discuss saving, investing, patience, and responsibility. That makes it especially relevant for parents who want a practical starting point rather than a dense lesson in personal finance.
The app is free to install, is rated for Everyone, and works on Android devices running version 7.0 or later. Acorns is the developer, and the current version is 9.7.0. It has reached over a hundred thousand installs, with an average rating of 4.5 from roughly three thousand ratings, so it has already attracted a meaningful audience without feeling like an obscure experiment.
How the smart investing plan changes the learning experience
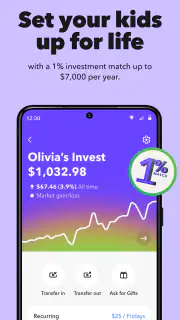
The central capability is the smart investing plan designed for a child’s or teenager’s financial journey. In practical terms, that gives the parent a framework for introducing investing as a gradual process instead of presenting it as a one-time decision. I think that framing matters because children often understand visible goals better than abstract financial outcomes.
A young user may care about a future purchase, a personal milestone, or simply seeing progress. The app’s value is strongest when a parent uses that interest as a bridge to explain why money can be set aside, why growth takes time, and why investing is different from spending immediately. The software becomes a conversation aid rather than a replacement for parenting.
The real strength is the routine it can create. A plan gives families something to revisit. Instead of discussing money only when a child asks for something, a parent can use regular check-ins to talk about what has changed, what the goal is, and whether the family’s approach still makes sense. That repeated context is more useful than a single burst of financial information.
I also appreciate that the concept is aimed at both kids and teens. Those groups need different explanations. A younger child may need simple language and visible progress, while a teenager may be ready to connect investing with longer-term independence. The same family tool can support both conversations, although the parent still has to adjust the explanation to the child’s age and maturity.
News Worth Your Time
Brain Test 2 Suits the Stop-and-Start Rhythm of Modern Phones
Google Play Games Makes Android Gaming Easier to Navigate, Not Easier to Love
WhatsApp Under Pressure: How Well It Recovers When Messages Fail
UNO!™ Beyond the Table: How Rivalry Keeps Players Coming Back
LinkedIn: Dominating the Professional Networking Arena
Unlocking the Full Potential of Pixel Art - Color by Number
Roblox: A Creative Revolution in Gaming
Why Gallery Stands Out in the Photo App World
How Pi Network is Revolutionizing Social Cryptocurrency
Google TV's Ecosystem Strategy: Redefining Streaming
How Little Panda: Princess Makeup Thrives with New OS Updates
Why Decor Life - Home Design Game Stands Out in Creative Simulation
What I would do before handing it to a child
I would not begin by giving the app to a child and expecting the interface to teach everything automatically. First, I would decide what the plan is meant to teach. Is the main lesson delayed gratification, the difference between saving and investing, or the habit of reviewing money regularly? Choosing one clear purpose prevents the experience from becoming a vague exercise in checking balances.
Next, I would agree on a simple routine. A short review once a week or once a month can be enough, depending on the child. The point is not to stare at the account constantly. Frequent checking can accidentally encourage a short-term mindset, especially if a teenager starts treating investing like a game whose score should rise every day.
I would also explain that a plan does not guarantee a particular result. That is an important limitation of any investing-focused product, and it should be discussed plainly. Children can easily interpret a growing number as a promise. Parents should use the app to explain uncertainty, time horizons, and the fact that financial decisions always involve tradeoffs.
A realistic family routine
Imagine a parent whose teenager wants to save toward a future goal but keeps spending small amounts as soon as they receive them. With Acorns Early, the parent could use the investing plan as a structured middle ground: some money can remain available for immediate choices, while another portion is connected to a longer-term objective.
During a monthly review, the parent might ask what the teenager remembers about the plan, whether the goal still matters, and what they learned from watching progress over time. The useful part is not merely the number on the screen. It is the decision-making conversation around that number. The teenager begins to see that money can have different jobs, and that not every dollar needs to be treated the same way.
For a younger child, the same routine would need to be much simpler. A parent might focus on the idea that money set aside today is being reserved for later, without introducing complicated investment vocabulary. The app can support that progression, but the quality of the lesson depends on how clearly the adult translates it.
Where the experience is genuinely helpful
One non-obvious benefit is that the app can help parents move from general advice to a repeatable workflow. Many adults tell children to save, but never establish what saving means, when to review it, or how to connect it with a goal. A smart investing plan gives the discussion a place to start and a reason to return.
Another useful angle is the separation between teaching and temptation. A child who only sees money as spending power may struggle to understand long-term planning. A dedicated financial experience can make the distinction visible: money can be used now, held for later, or connected to a broader investing objective. That three-way comparison is more educational than simply saying “don’t spend so much.”
A third insight is that the parent’s role becomes more important, not less. The app is most effective when it prompts questions. What surprised you? What would you do differently next time? Why do you think this money has a longer time horizon? Those questions turn passive viewing into active learning. Without them, the child may only learn to monitor an account.
The tradeoffs parents should understand
The biggest tradeoff is simplicity versus control. A focused plan is easier for a family to understand than a full investing dashboard, but experienced investors may want more detailed tools, research, customization, or direct control than this child-centered approach is designed to provide. If your priority is managing a complex portfolio, this is unlikely to be the right primary app.
There is also a difference between financial education and financial performance. The app can help create a useful habit, but it cannot remove market uncertainty or make investing risk-free. Parents who want guaranteed outcomes, instant access, or a completely predictable balance may prefer a conventional savings approach for a particular goal.
I would also be cautious about making the child feel responsible for outcomes they cannot control. If a balance changes in an unexpected direction, the moment should become a lesson about uncertainty rather than a source of blame. This is one reason I would keep the parent involved and avoid presenting the plan as a competition.
Another possible friction point is family consistency. If adults use the app only once and then forget about it, the educational benefit fades. The plan works better when it is connected to a household routine, such as a regular money conversation or a review of goals. Families looking for a completely hands-off solution may find that the app requires more participation than expected.
How it compares with familiar alternatives
Compared with a standard savings account, the app offers a more direct way to discuss investing and long-term growth. A savings account can be easier to explain and may feel more predictable, but it may not create the same opportunity to talk about market-based uncertainty and time horizons. The better choice depends on the lesson the family wants to teach.
Compared with a spreadsheet, Acorns Early is more approachable for families who do not want to build their own tracking system. A spreadsheet can provide excellent visibility and customization, but it requires discipline, design work, and regular maintenance. The app’s advantage is having a dedicated child-focused context rather than asking parents to construct one from scratch.
Compared with a general investing app, this product is more suitable when the goal is to involve a young person in a guided financial conversation. A general platform may offer broader functionality, but that breadth can overwhelm a beginner or shift attention toward transactions. Acorns Early makes more sense when the family values a clear educational purpose over a professional-style toolkit.
On the other hand, a teenager who already understands investing and wants advanced analysis may outgrow this approach. In that situation, a more comprehensive investment service could be a better fit, while this app remains useful as a family-oriented starting point. I would judge it by the job it is meant to do, not by whether it can replace every financial tool.
Who gains the most from using it
I think the strongest audience is parents who want to start a calm, ongoing conversation about money with a child or teenager. It is particularly useful for families that have good intentions but lack a simple structure. The plan can provide that structure without requiring the parent to become a finance expert first.
It can also suit parents who want to introduce investing gradually rather than waiting until a child is an adult. The app gives them a way to discuss future goals, regular habits, and uncertainty in age-appropriate stages. That does not mean every child will be interested immediately, but it gives the family a practical foundation.
It is less suitable for someone seeking a standalone investing experience with no adult guidance. It is also not ideal for a user who wants a broad financial dashboard, detailed trading controls, or a tool focused exclusively on day-to-day budgeting. The child-centered purpose is a strength, but it naturally narrows the audience.
Before installing it, I would ask three questions. Do I have a clear financial lesson in mind? Am I willing to review the plan with my child instead of treating it as automatic education? And do I understand that investing involves uncertainty? If the answer to all three is yes, the app has a much better chance of becoming useful rather than decorative.
My experience with the overall design and value
The free price makes it approachable for families who want to explore the idea before committing money to a new financial tool. That lowers the barrier to trying the educational workflow, although parents should still think carefully about the financial decisions connected to any investing plan rather than treating “free” as meaning risk-free.
The Everyone content rating also makes sense for a family-oriented product, but that label should not be confused with independent suitability for every child. Age rating describes general content, while financial readiness depends on the child’s understanding and the parent’s involvement. A mature teenager and a young child may use the same concept very differently.
With its release on November 8, 2024, and its current version, 9.7.0, the app feels like a relatively recent option in the family finance space. I would still keep the app updated through the normal store process, especially for a finance product, because current software is preferable when handling personal financial routines.
What stayed with me is that the app’s best outcome is behavioral, not visual. If it helps a child pause before spending, understand why a goal takes time, and ask better questions about money, it has done something valuable. If it only becomes another screen to check, its impact will be much smaller.
My recommendation is therefore specific: I would suggest Acorns Early to a parent who wants a guided way to introduce smart investing and is prepared to participate in the process. I would not recommend it as a replacement for a full investment platform, a detailed household budget, or direct financial guidance. Used in the right role, it can make an abstract subject feel more concrete and help a family build a healthier money routine together.
Overall, I see Acorns Early: Kids Money App as a focused family finance app rather than a complete financial command center. Its strongest feature is the way a smart investing plan can turn occasional advice into an ongoing learning habit. The tradeoff is that the parent must supply the context, patience, and judgment. For families willing to do that, the app offers a practical starting point for raising financially aware kids and teens.
Pros
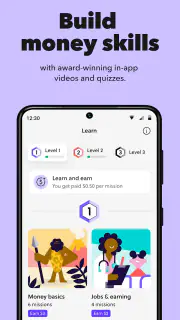
- Teaches saving and spending through age-appropriate activities.
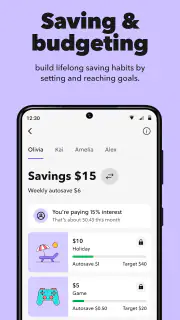
- Parents can set goals and monitor progress from one account.
- Simple interface makes money concepts easier for young children.
- Encourages regular saving with automated contributions.
- Useful companion for discussing real-world financial decisions.
Cons
- Requires a parent-managed Acorns account to access its full value.
- Some features may depend on the parent’s subscription or plan.
- Investment concepts can be difficult for younger children to understand.
- Limited usefulness if families rarely use the app together.
- Availability and features may vary depending on location and account type.
FAQ's for Acorns Early: Kids Money App
What is Acorns Early: Kids Money App, and who is it designed for?
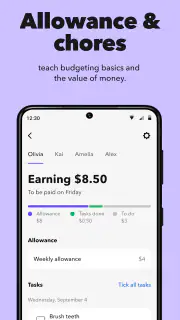
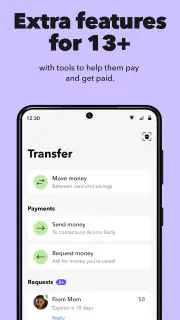
Acorns Early is a family-focused money app designed to help parents introduce children to saving, spending, and basic financial responsibility. Parents can use it to manage allowances, assign chores, set goals, and give children a supervised way to learn about money. It is generally aimed at families with children, although available features, age requirements, and account eligibility may vary depending on location and the current Acorns service offering.
Can children use Acorns Early independently, or does it require a parent account?
The app is intended to work under parental supervision rather than as a completely independent banking service for children. A parent or legal guardian normally creates and manages the family account, controls permissions, and decides how money is provided or used. Children may receive access to age-appropriate features, but parents remain responsible for reviewing activity, setting limits, and explaining safe financial habits.
What features does Acorns Early offer for teaching kids about money?
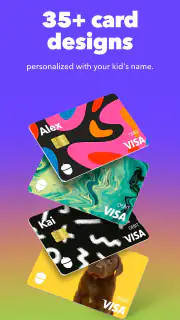
Acorns Early focuses on practical learning instead of simply showing a balance. Depending on the plan and region, families may be able to manage allowances, connect payments to completed chores, create savings goals, and provide children with a controlled spending experience. These tools can help kids understand earning, budgeting, saving, and delayed gratification, while parents retain oversight of transactions and account activity.
Does Acorns Early charge fees, and is a subscription required?
Potential costs are one of the most important details to check before downloading or signing up. Acorns Early may be included with certain Acorns family plans or may require an eligible subscription, and pricing can change over time. Additional conditions may apply to cards, transfers, investment-related services, or other account features. Always review the latest pricing, trial terms, and cancellation policy in the official app listing or Acorns website.
Is Acorns Early safe for children to use?
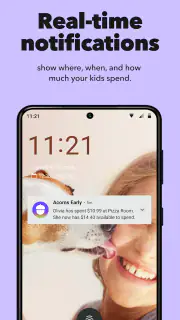
Acorns Early is built around parental controls and supervised access, which can make it safer than giving a child unrestricted access to a traditional payment account. Parents should still use strong login credentials, enable available security protections, review notifications and transactions, and teach children not to share passwords or card details. Before enrolling, check the privacy policy, age requirements, supported countries, and protections that apply to the specific account.