
Instacart Shopper Rewards
Android OnlyFree·User Rating
 Analysis by ViaAPK
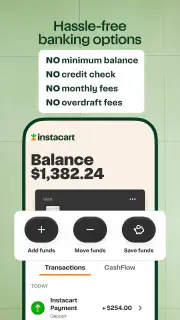
When I opened Instacart Shopper Rewards, I expected a focused finance app rather than a broad budgeting tool. That expectation matters because its store identity is tied to Instacart Shopper, while its summary points toward discovering a new debit card. In practice, I see it as a companion for people who earn through shopping work and want a more direct way to think about the money connected with that work.
The app comes from Branch Messenger, and it is free to install. Its Everyone age rating makes the presentation approachable, but the intended audience is much narrower than the rating suggests: this is most useful to an Instacart shopper who is already looking at the rewards and payment side of the experience. I would not choose it as my main personal-finance app if I simply wanted expense categories, investment charts, or a complete household budget.
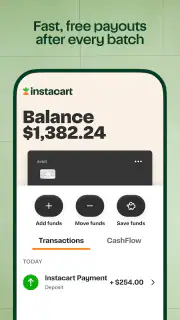
My overall impression is positive but practical. The appeal is not that it replaces every financial tool on a phone. The appeal is that it can bring a work-related debit-card experience closer to the place where a shopper already thinks about earnings. That can remove a small but meaningful step from the routine of finishing a batch, checking available money, and deciding what to do next.
From a completed shop to money I can use
I start with the moment a shopping shift ends, because that is where this app’s purpose becomes easiest to judge: it is meant to bring the debit-card side of shopper finances into view, not replace every banking tool I use. From there, I look at how that idea holds up during a busy day, when quick checks and clear handoffs matter more than extra features.
The starting condition: a shopper needs a clearer next step
Imagine finishing a busy afternoon of shopping. I have handled the orders, dealt with substitutions, and reached the point where I want to understand what happens with the money connected to that work. Normally, this is where a general banking app, a separate card, and the Instacart workflow can begin to feel disconnected. I may know that I earned money, but I still want a simple answer to a more practical question: what can I do with it now?
That is the situation where this app makes the most sense. Its purpose is not presented as a general lesson in personal finance. Instead, the focus is the debit card and the rewards experience associated with shoppers. For me, that makes the starting point easy to understand: I am not opening it to track every bill in my life; I am opening it because my shopper activity and my day-to-day spending may overlap.
This distinction is important before installing it. A person who drives for several platforms, runs a small business, or wants one universal banking dashboard may find a traditional bank app more complete. A shopper who wants a work-oriented financial companion has a clearer reason to try this one.
News Worth Your Time
Brain Test 2 Suits the Stop-and-Start Rhythm of Modern Phones
Google Play Games Makes Android Gaming Easier to Navigate, Not Easier to Love
WhatsApp Under Pressure: How Well It Recovers When Messages Fail
UNO!™ Beyond the Table: How Rivalry Keeps Players Coming Back
LinkedIn: Dominating the Professional Networking Arena
Unlocking the Full Potential of Pixel Art - Color by Number
Roblox: A Creative Revolution in Gaming
Why Gallery Stands Out in the Photo App World
How Pi Network is Revolutionizing Social Cryptocurrency
Google TV's Ecosystem Strategy: Redefining Streaming
How Little Panda: Princess Makeup Thrives with New OS Updates
Why Decor Life - Home Design Game Stands Out in Creative Simulation
The first pass: identifying the right financial lane
The first useful habit is to decide what job I want the app to perform before I start tapping through it. If I treat it as a replacement for all my banking, I will probably judge it unfairly. If I treat it as a place to understand the shopper debit-card side of my routine, the experience becomes more focused.
I would begin by checking that the app is the one published by Branch Messenger and that the shopper context matches my own work. That small verification step is worthwhile because finance apps deserve more care than casual entertainment downloads. I also prefer to install the current release rather than rely on an old copy. The current version is 2026.8.2, and the app requires Android 10 or later, so an older phone may be the first practical obstacle.
The public response is encouraging without being overwhelming: it holds a 4.3 average from around 500 ratings, with more than 100,000 installs. I read that as a sign that the app has found a real audience, not as proof that every shopper will have the same experience. Finance tools are especially dependent on personal circumstances, account setup, and how closely the service fits the user’s work pattern.
Moving through the workflow instead of browsing aimlessly
Once I am inside, I would keep the process task-based. First, I would look for the part of the experience that explains or presents the new debit card. Then I would connect that information to my actual shopper routine: when money becomes available, how I expect to use the card, and whether it is convenient enough to become part of my regular spending.
This is one of the less obvious strengths of a specialized app: it can reduce the mental translation between “I completed shopper work” and “I need to manage money.” In a general finance app, I might have to create my own categories, remember which deposits came from shopping, and manually interpret the connection. Here, the shopper context gives the workflow a more obvious starting point.
Still, I would not rush through the setup simply because the app feels focused. Before relying on a work-linked card, I would read each screen carefully, especially anything involving account access, card use, or the movement of funds. A convenient flow is only helpful when I understand what I am agreeing to and which account I will actually use for everyday purchases.
A realistic everyday handoff
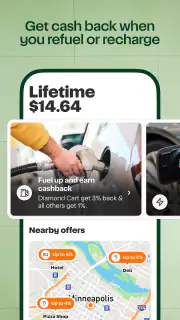
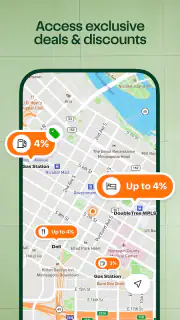
Here is the scenario I find most convincing. I finish shopping in the afternoon and need fuel before heading home. Instead of waiting until later to sort out which money is available, I open the shopper rewards app, review the card-related information, and use the connected payment method if it fits my plans. The handoff is from completed work, to financial visibility, to a purchase that supports the next work period.
That is more useful than a vague promise of “rewards” because it describes a repeatable behavior. The app becomes part of a loop: work is completed, the financial side is checked, and the result is used for a practical expense. I would also use the same routine before a long shopping session, checking that I understand my available spending position rather than assuming that a previous balance is still accurate.
A second use case is separating shopper-related money from my regular personal spending. Even without turning the app into a full accounting system, a dedicated work-oriented payment path can make it easier for me to recognize which purchases belong to the shopping routine. That could help when I review fuel, meals, or other workday spending later, although I would still keep my own records if I needed precise tax or business accounting.
Where the handoffs become important
The app is only one part of the chain. The other parts include the Instacart shopper experience, the debit-card relationship, the places where I spend, and whatever personal bank account I use alongside it. Every handoff is a chance for confusion. I might finish a shop but still need to wait for the relevant balance to update. I might see a card benefit but not understand whether it applies to the purchase I am about to make. I might use the card for personal spending and later struggle to distinguish it from work costs.
My advice is to assign the app one clear role. I would use it as the work-linked financial checkpoint, then keep a separate note or budgeting method for expenses that need detailed records. This two-layer approach is less glamorous than expecting one app to do everything, but it is safer and easier to audit.
Another useful habit is to check the destination of money before building a routine around it. If I am expecting the app to replace my normal bank account, I would first confirm that its card experience suits my everyday needs. If I only need a convenient way to handle shopper-related funds, the standard is different. The right question is not “Is this the best finance app?” but “Does this remove enough friction from my specific shopper workflow to justify using it?”
The result: convenience with a narrower purpose
When the workflow works, the result is a more direct relationship between shopping activity and spending. I can see why a shopper might prefer that over moving between a general bank app, an Instacart work screen, and a separate rewards page. Fewer mental jumps can make a difference during a busy day, especially when I am trying to get back on the road rather than perform bookkeeping.
The debit-card angle also gives the app a concrete outcome. I am not merely reading financial information; I am considering how the card fits into real purchases. That makes the product easier to evaluate. If the card is convenient for the way I work and spend, the app has earned a place in my routine. If it does not, the rest of the presentation matters much less.
I also appreciate that the app is free to download. That lowers the barrier to testing the workflow, though I would never interpret a free download as meaning that every related financial service or transaction is automatically cost-free. Before committing to regular use, I would review the terms shown during setup and card use, then compare the practical conditions with my existing bank or card.
The public review volume is modest compared with major banking products, so I would treat the rating as useful context rather than a guarantee. A specialized tool can have a good average while still being a poor match for someone whose shopping schedule, phone, or banking habits differ from the typical user.
Where the flow breaks
The first break is audience fit. If I am not an Instacart shopper, the app’s central idea loses much of its value. Even if I want a new debit card, I would probably compare it with a conventional bank app or a general card-management service that is built around my broader financial life rather than a specific work activity.
The second break is scope. I would not rely on this app alone for household budgeting, long-term savings planning, investment decisions, or detailed business bookkeeping. Its shopper-centered design is an advantage for one workflow and a limitation for everything outside that workflow. Trying to force it into a universal finance role would create extra manual work, not remove it.
The third break is the handoff between app information and real-world spending. A balance or card screen is helpful only if I understand when it reflects my activity and how I should act on it. If I need instant certainty for a time-sensitive purchase, I would check the relevant details directly rather than assume that a previous screen tells the whole story. That is not a criticism unique to this app; it is a sensible rule for any financial tool connected to active work.
There is also a device consideration. Android 10 is the minimum operating system, so anyone using an older handset should check compatibility before planning around the service. For shoppers who depend on a single phone throughout the day, compatibility is not a minor detail: an app that cannot run reliably on the work device cannot become part of the workflow.
Who should use it, and who should choose something else?
I would recommend giving it a serious look if I were actively shopping for Instacart, wanted to understand the new debit-card option, and preferred to keep work-related money closer to the service that generated it. It is especially appealing for someone who values a short path from completed work to usable spending and who does not need a full-featured personal bank dashboard.
I would be more cautious if I already have a bank setup that handles deposits, card spending, budgeting, and records cleanly. In that case, adding another financial app may create more places to check rather than fewer. The rewards angle would need to provide a clear everyday benefit before I accepted that extra layer.
I would also skip it as a primary choice if my main goal is detailed financial analysis. A budgeting app may be better for category trends, while a bank app may be better for a complete view of accounts and recurring payments. The specialized nature of this product is not a weakness by itself; it simply means I should judge it against the shopper task it is designed to support.
My practical verdict after following the full path
Instacart Shopper Rewards works best when I follow it from a specific starting condition to a specific outcome: I complete shopper work, review the debit-card side of the experience, decide how the money fits my immediate plans, and use a separate system for anything requiring broader financial records. That complete workflow is more convincing than the store summary alone because it shows where the app belongs in an actual day.
Its strongest quality is focus. Branch Messenger has positioned it around a recognizable shopper need rather than asking it to be everything at once. The trade-off is equally clear: people outside that audience, or people seeking a complete banking and budgeting replacement, may find a more conventional finance app easier to manage.
For me, the sensible approach would be to try it with one controlled routine first, such as checking the card experience after a shopping shift and using it for a clearly understood workday purchase. I would keep my normal bank and records in place until the handoffs feel dependable. The best reason to use this app is not the promise of a new card by itself, but the chance to make a shopper’s money workflow easier to follow.
With that expectation, I see it as a useful, specialized finance app rather than a universal financial home. It is free, accessible to an Everyone-rated audience, and already used by a growing group of people, but its real value depends on whether Instacart shopping is part of my everyday routine. If it is, the app is worth testing. If it is not, I would put my time into a broader banking or budgeting alternative.
Pros
- Rewards can add extra value to regular shopping and delivery activity.
- Progress is easy to track through the shopper app.
- Useful incentives may help offset everyday work-related expenses.
- Rewards are integrated into the existing Instacart shopper experience.
- Offers can encourage shoppers to complete more batches.
Cons
- Eligibility and rewards may vary by location
- account
- or shopper status.
- Some benefits may require meeting specific activity or spending thresholds.
- Reward values and available offers can change without much notice.
- Not every shopper will find the available perks equally useful.
- Extra rewards may not compensate for low-paying or inconvenient batches.
FAQ's for Instacart Shopper Rewards
What is Instacart Shopper Rewards?
Instacart Shopper Rewards is a benefits program designed for eligible Instacart shoppers. Depending on your location, activity, and current program rules, it may provide access to rewards, discounts, savings, or other perks connected with completing batches and using Instacart services. The exact benefits can change, so shoppers should review the terms shown in the app before relying on a particular offer.
Who can participate in Instacart Shopper Rewards?
Eligibility is not necessarily the same for every shopper. Access may depend on your country or region, shopper status, account standing, completed activity, and the specific promotion or benefit being offered. After installing or opening the related Instacart app, sign in with your shopper account and check the Rewards section. If it is unavailable, your account or location may not currently qualify.
Does Instacart Shopper Rewards cost money?
Using the rewards feature itself generally does not require a separate subscription fee, but individual benefits can have their own conditions. Some offers may require a minimum purchase, a qualifying transaction, a specific payment method, or completion of an eligible batch. Always read the expiration date, exclusions, and redemption instructions because a reward is not automatically the same as cash.
How do I earn and redeem rewards in the app?
The available earning and redemption process depends on the current Instacart program. In the app, sign in to your shopper account, open the rewards or benefits area, and review the listed requirements before completing an activity. Some rewards may be applied automatically, while others require activation or redemption. Keep the app updated and save confirmation details if a reward does not appear.
Are Instacart Shopper Rewards available everywhere, and do they expire?
No, rewards and benefits may vary by market, account, campaign, and time period. An offer displayed for one shopper may not appear for another, even in the same city. Many rewards include an expiration date, usage limit, or other restrictions, and program rules can change without creating a permanent entitlement. Check the official in-app terms before planning your shopping or spending around a reward.