
CoverMe - Instant Cash Advance
Android OnlyFree·User Rating
 Analysis by ViaAPK
When an unexpected bill lands before payday, the hardest part is often not finding a financial app but deciding whether it will actually fit the situation. I tested CoverMe - Instant Cash Advance as a finance app built around that exact moment: needing access to cash before the next regular income arrives. Its central appeal is simple, but the practical question is whether the app helps you make a controlled short-term decision or merely makes borrowing feel effortless.
My overall impression is that CoverMe is most useful when the amount you need is modest, the repayment timing is clear, and you already have a realistic plan for getting back to your normal budget. It is free to install, aimed at everyone, and developed by DIONIS K. The current release is version 1.6.3, and it works on devices running Android 7.0 or later. Those details make it accessible to a broad group of users, but accessibility should not be confused with affordability: an advance is still a financial commitment.
The app has attracted a 4.6 average from around 32 thousand ratings, with roughly 2.1 thousand written reviews and over 100 thousand installs. That gives me some confidence that the basic idea is understandable to many people, although popularity is not a substitute for checking the terms shown to you personally. I would treat the app as a short-term tool, not as a replacement for wages, savings, or a proper emergency fund.
Starting with a careful cash-advance workflow
The safest way to use CoverMe is to begin with the problem rather than the maximum amount you might be offered. I would first write down the exact bill, the date it must be paid, and the income that is expected to arrive afterward. Then I would open the app and compare the amount needed with the amount I can genuinely repay without creating another shortage.
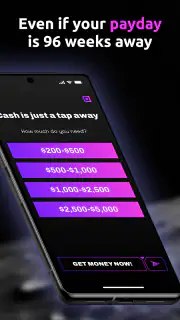
That small pause matters because the store summary presents the app as useful even when payday is a long way away, potentially as far as 96 weeks. I would not read that as a reason to stretch a temporary solution across a lengthy period. A long repayment horizon can make a payment look manageable while keeping the obligation in your budget for much longer than expected. For a one-off utility bill, transport problem, or urgent household purchase, the shortest sensible path is usually easier to understand than a drawn-out commitment.
My preferred first session would be deliberately unhurried. I would review the amount, repayment schedule, total obligation, and any conditions presented before accepting anything. I would also take a screenshot or note of the final figures for my own records. That is not glamorous, but it prevents the common mistake of remembering only the cash received and forgetting the amount that must leave the account later.
A realistic example is a broken phone needed for work. If replacing it immediately prevents missed shifts, an advance might be useful. I would still compare the total repayment with the cost of a cheaper temporary handset, a repair, or asking the employer about an early wage option. CoverMe makes the borrowing route convenient, but convenience should be the final step in the decision, not the first.
News Worth Your Time
Brain Test 2 Suits the Stop-and-Start Rhythm of Modern Phones
Google Play Games Makes Android Gaming Easier to Navigate, Not Easier to Love
WhatsApp Under Pressure: How Well It Recovers When Messages Fail
UNO!™ Beyond the Table: How Rivalry Keeps Players Coming Back
LinkedIn: Dominating the Professional Networking Arena
Unlocking the Full Potential of Pixel Art - Color by Number
Roblox: A Creative Revolution in Gaming
Why Gallery Stands Out in the Photo App World
How Pi Network is Revolutionizing Social Cryptocurrency
Google TV's Ecosystem Strategy: Redefining Streaming
How Little Panda: Princess Makeup Thrives with New OS Updates
Why Decor Life - Home Design Game Stands Out in Creative Simulation
The same approach applies to a late bill. If I know money will arrive soon and the advance bridges a specific gap, the app may be a practical option. If I am already relying on advances to cover groceries, rent, and previous repayments, I would stop and look for a different solution. Repeated borrowing can hide a monthly budget problem that an instant-cash product cannot fix.
What I would check before accepting an advance
I would pay particular attention to the difference between the amount requested and the amount that will ultimately be repaid. Those figures answer different questions. The first tells me whether the app can solve the immediate problem; the second tells me whether the solution fits my next budget. I would also check the expected repayment date against the actual timing of my income rather than assuming a deposit will arrive early.
Another useful habit is to consider what happens if the expected income is delayed. If one late payment would leave me unable to cover essentials, I would not proceed. A cash advance should reduce a temporary timing problem, not transfer the same problem into a more expensive or stressful date.
I would also avoid applying while distracted or in a rush. Financial screens can be easy to skim, especially on a small phone. Reading each confirmation page and saving the final details gives me a clearer record of what I agreed to. The app is designed for speed, but responsible use requires slowing down at the exact point where speed is most tempting.
Settings and account details worth reviewing
CoverMe is not the kind of app I would install and immediately treat as a set-and-forget service. Before using it, I would inspect every available account, notification, and repayment-related option inside the version installed on my phone. I would want reminders to be useful rather than overwhelming, and I would make sure the contact and payment information displayed in the app is current.
Keeping personal details accurate is especially important in a finance app. A changed phone number, outdated email address, or old bank information can create unnecessary confusion when an application or repayment needs attention. I would review those details before requesting money, not after a problem appears.
I would also check the app’s notification behavior. Reminders can help me prepare for a repayment, but I would not rely on a notification as my only record. My own calendar entry, with the expected amount and date, is a better backup. This is one of the most useful habits for repeat users: let the app remind you, but keep an independent reminder that remains under your control.
Privacy deserves a practical check as well. I would read the permission prompts and only continue when I understand why the app needs the access it requests. I would avoid entering information that is not necessary for the application process, and I would never share a verification code with another person claiming to represent the service. Those precautions are not a criticism of CoverMe specifically; they are basic protection whenever money and identity details meet on a phone.
Because the app is rated for everyone, it may feel approachable to a wide audience. That label describes suitability of content, not financial suitability. I would still keep the app away from a child’s casual use and explain to less experienced family members that pressing through an application can create a real obligation.
Repeatable patterns that make the process less stressful
Experienced use is less about tapping faster and more about repeating the same safe sequence. My pattern would be: identify the exact need, confirm the repayment source, open CoverMe, review the displayed terms, request only the necessary amount, and record the final obligation. Reusing that sequence reduces the chance of making an emotional decision during an emergency.
I would also separate “checking eligibility” from “accepting an advance” in my mind. Opening the app to understand the available route does not mean I have to continue. That distinction gives me room to compare alternatives instead of treating the first available offer as the only answer.
A second helpful pattern is to use the app for one clearly defined purpose at a time. If I need money for a medical item, I would calculate that cost separately from a desire to catch up on unrelated spending. Combining several needs into one request makes it harder to see which expense caused the pressure and whether the total repayment is still comfortable.
For someone paid irregularly, I would build a simple income calendar before using the app. Marking expected freelance payments, benefits, or shifts can reveal whether the proposed repayment date is realistic. If income changes from week to week, I would use the lowest dependable estimate rather than the most optimistic one. That trade-off may mean borrowing less or not borrowing at all, but it makes the decision more honest.
One non-obvious advantage of this workflow is that it creates a stopping point. If the numbers do not work after the repayment is added to the next budget, I have a clear reason to exit. Without that rule, the pressure of an urgent bill can make a convenient application feel inevitable.
Where the app fits beside ordinary alternatives
Compared with a traditional bank overdraft, CoverMe may feel more focused on the immediate cash gap and less tied to a full banking relationship. That can be useful for someone who needs a clear short-term route rather than a permanent credit facility. On the other hand, a bank product may be preferable when the cost is lower, the terms are familiar, or the user already has an agreed buffer.
Compared with borrowing from a friend or family member, an app offers a more private and structured process. That privacy can be valuable, but personal borrowing may be cheaper or more flexible when a trusted person is genuinely able to help. I would not choose an app automatically simply because asking someone feels uncomfortable.
Compared with a credit card, a cash-advance app may suit a person who does not want to use revolving credit for a small emergency. Yet a credit card with a clearly understood grace period could be better for someone who can repay quickly and already knows the costs. The right comparison is not “app versus card” in the abstract; it is the total repayment, timing, and consequences of each option in this particular situation.
Employer-based early-pay services and local assistance programs can also be better alternatives when they are available. They may address the timing issue without adding the same kind of short-term borrowing pressure. I would check those options before accepting an advance, especially for recurring expenses.
Limits that become clearer with repeated use
The biggest limitation is structural: CoverMe can help bridge a gap, but it cannot improve an income that is consistently too small for regular expenses. If the same user returns every pay cycle, the app may become part of the problem even when each individual request seems reasonable. I would set a personal rule that a repeat request triggers a budget review rather than an automatic new application.
Another limitation is that fast access can narrow attention. The app’s purpose naturally directs me toward getting cash, while the more important question may be why the cash is needed. I would therefore compare the advance with delaying a nonessential purchase, negotiating a bill date, selling an unused item, or using an existing emergency fund. These options may be less convenient but can leave the next pay period healthier.
Long repayment periods deserve special caution. The possibility of a schedule extending many months can be useful for someone with a carefully planned obligation, but it can also make a small emergency linger. I would ask myself whether I still want this debt attached to my budget after the original problem is forgotten. If the answer is no, I would look for a shorter or non-borrowing alternative.
I would also avoid judging the app solely by its average rating. A strong rating suggests that many people find the experience usable, but it does not tell me whether my income pattern, banking situation, or emergency is a good match. Finance apps are unusually personal: the same workflow can be helpful for one person and risky for another.
Who should use it, and who should skip it
I think CoverMe is best suited to an adult who has a specific, urgent expense, understands the displayed repayment obligation, and can identify dependable income that will cover it. It is also a reasonable candidate for someone who values a simple mobile process and wants to compare a cash advance with a bank or card option.
I would skip it if I am borrowing for routine living costs with no clear way to catch up, if I am using one advance to repay another, or if the repayment would force me to miss rent, food, utilities, or medication. I would also hesitate if my income date is uncertain enough that the planned repayment could easily arrive before the money I am counting on.
People who prefer face-to-face guidance may be better served by a bank, credit counselor, or trusted financial adviser. Likewise, someone looking for long-term debt management should not expect an instant-cash app to provide the planning and negotiation that a dedicated service can offer.
My verdict after building a safer routine
CoverMe - Instant Cash Advance is a convenient finance app with a clear short-term purpose. I like it most when I treat it as a controlled bridge: one defined expense, one realistic repayment source, and a written record of the final commitment. The free entry point and broad device compatibility make it easy to consider, while the strong user response suggests that the core experience works for many people.
My recommendation comes with a firm condition: do not let the app’s speed replace your judgment. Check the amount you will repay, use independent reminders, keep your account details current, and compare less costly alternatives before accepting money. The most advanced habit is not finding a way to request more; it is knowing when the numbers say to stop.
For a genuine one-time timing problem, I can see why someone would keep this app available. For recurring financial shortfalls, I would choose budgeting help, employer support, a bank option, or another longer-term solution instead. Used selectively and with a clear exit plan, CoverMe can be useful. Used as a routine extension of income, it is not the right tool.
Pros
- Simple application process with minimal paperwork required.
- Funds may arrive quickly after approval
- depending on your bank.
- Repayment dates and loan details are shown clearly in the app.
- Useful for comparing available offers in one convenient place.
- Digital account management avoids branch visits and phone calls.
Cons
- Approval and funding are not guaranteed for every applicant.
- Loan costs can vary and may be high compared with traditional credit.
- Eligibility may depend on personal data
- income
- and banking history.
- Late repayments could lead to extra fees or damage your credit.
- Availability and terms may differ by state or region.
FAQ's for CoverMe - Instant Cash Advance
What is CoverMe - Instant Cash Advance?
CoverMe - Instant Cash Advance is a financial app designed to help eligible users access short-term funds before their next paycheck. After creating an account and providing the requested personal and financial information, the app may display available advance options, repayment details, and applicable fees. Availability, limits, and approval are not guaranteed and can vary by user.
How much money can I borrow with CoverMe?
The amount available through CoverMe depends on factors such as your account information, income, transaction history, eligibility, and repayment record. New users may receive a smaller limit, while returning users could qualify for a different amount. The app should show the exact advance, fees, and repayment schedule before you accept, so review those details carefully.
Does CoverMe charge fees or interest?
CoverMe may apply fees or other costs depending on the advance, transfer method, and your location. The total repayment amount should be presented before you confirm the transaction, but users should read the agreement rather than relying only on promotional wording. Check whether optional services, expedited transfers, subscription charges, or late-payment consequences apply to your account.
How quickly can I receive money from CoverMe?
The delivery time depends on the transfer option you select and the receiving bank or card provider. Some transfers may arrive quickly, while standard delivery can take longer, particularly during weekends, holidays, verification reviews, or technical delays. CoverMe cannot necessarily control processing times after funds have been sent, so avoid relying on an advance for an urgent bill until the deposit is confirmed.
Is CoverMe safe, and what information does it require?
CoverMe may request sensitive details such as your identity information, income, employment, bank account, or debit-card data to verify eligibility and process repayments. Before using the app, review its privacy policy, permissions, security practices, and data-sharing terms. Download it only from an official app store, use a strong password, and contact support promptly if you notice suspicious activity.