
Elektra Go: Money Transfer
Android OnlyFree·User Rating
 Analysis by ViaAPK
Moving money is one of those tasks where convenience matters, but trust matters even more. I spent time looking at Elektra Go: Money Transfer as a finance app and found that its appeal is easy to understand: it is free to install, focused on transfers, and presented as a straightforward way to handle money from a phone. The important question, though, is not whether it feels useful during the first few days. It is whether it deserves a regular place on your phone once the novelty has gone.
My overall impression is that Elektra Go is most interesting for people who already have a practical reason to use Elektra USA’s service. If your routine includes sending money and you prefer a dedicated mobile tool over visiting a physical location or relying on a broader banking app, it can make that process feel more accessible. If you only transfer money occasionally, the decision is less obvious, because another service you already use may be simpler than adding a separate finance app.
What the first week with Elektra Go feels like
The first-week appeal comes from focus. Elektra Go is not trying to be a general budgeting suite, an investment dashboard, or a full replacement for every financial tool. Its identity is tied to money transfers, which gives the experience a clear purpose. I appreciate that kind of narrow design because financial apps can become confusing when they combine too many unrelated tasks.
That focus also changes how I judge it. I am not looking for elaborate charts or a long list of financial products here. I want to know whether the app helps me begin a transfer without unnecessary wandering, whether the information is readable on a small screen, and whether the process gives me enough confidence to review what I am doing before committing. For a transfer app, calm and clarity are more valuable than visual drama.
The app is developed by Elektra USA and is available at no cost. It has an Everyone content rating, so its presentation is intended for a broad audience rather than a narrowly defined financial or professional group. The current release is version 9.8.3, and it runs on Android 8.0 or later. That older operating-system support is useful for people who keep a reliable phone for several years instead of upgrading frequently.
In everyday use, I would approach the first transfer slowly rather than treating it like a casual shopping checkout. I would check the recipient details, review every displayed amount, and make sure the selected destination is correct before confirming. This is not a criticism unique to Elektra Go; it is simply the right habit for any money-transfer service. A clean interface can reduce mistakes, but it cannot replace careful review.
A realistic example is a person who needs to send money to a relative while away from a nearby service location. Instead of planning the trip around opening hours or handling the task only when they are at a computer, that person can use a phone-centered workflow. The value is not just speed. It is the ability to start the task when the need appears, then complete it with the relevant details close at hand.
News Worth Your Time
Brain Test 2 Suits the Stop-and-Start Rhythm of Modern Phones
Google Play Games Makes Android Gaming Easier to Navigate, Not Easier to Love
WhatsApp Under Pressure: How Well It Recovers When Messages Fail
UNO!™ Beyond the Table: How Rivalry Keeps Players Coming Back
LinkedIn: Dominating the Professional Networking Arena
Unlocking the Full Potential of Pixel Art - Color by Number
Roblox: A Creative Revolution in Gaming
Why Gallery Stands Out in the Photo App World
How Pi Network is Revolutionizing Social Cryptocurrency
Google TV's Ecosystem Strategy: Redefining Streaming
How Little Panda: Princess Makeup Thrives with New OS Updates
Why Decor Life - Home Design Game Stands Out in Creative Simulation
That convenience is strongest when the transfer is a recurring part of someone’s life. For a one-off emergency, the app may still help, but the user will probably spend more time becoming familiar with the process and checking requirements. A service already used by the recipient or sender may be more practical in that moment, particularly if the other service offers a familiar contact list or an established transaction history.
One useful first-week tip is to avoid judging the app only by how quickly the opening screen appears. The better test is the full path from intention to confirmation. Notice where the app asks for information, which details must be entered manually, and where the final review happens. That tells me more about whether it will fit a monthly routine than a polished first impression does.
The app’s reception suggests that many users find the basic proposition worthwhile. It holds an average rating of 4.5 from 534 ratings, with 139 written reviews, and it has passed 100K installs. Those figures show meaningful adoption and generally positive feedback, but I would not treat them as a guarantee that every transfer will feel effortless. Finance apps are especially dependent on personal circumstances, recipient needs, and the user’s comfort with digital transactions.
Where it fits beside familiar alternatives
Compared with visiting a physical money-transfer counter, a mobile app can save travel time and make the task easier to fit around work or family responsibilities. The trade-off is that the user becomes responsible for entering and checking more information without a staff member standing nearby. Someone who values face-to-face guidance may still prefer an in-person option, especially for a first transfer or an unusual situation.
Compared with a traditional bank app, Elektra Go has a narrower identity. A bank application may be better if the main goal is to see balances, pay bills, move money between personal accounts, and manage several financial tasks in one place. Elektra Go makes more sense when the transfer itself is the central need and the user does not want to search through a large banking interface.
Compared with a general peer-to-peer payment app, the choice depends on the people involved. A broad payment network can be more convenient when both parties already use the same service and the recipient expects an instant app-based exchange. Elektra Go may be the better fit when its transfer process matches the sender’s established routine or when the connection to Elektra USA is the reason the user is considering it in the first place.
I would not install it simply because every finance app is worth having. I would install it when I can name the repeated task it will handle. That distinction is important: a transfer tool earns space through dependable repetition, not through the excitement of trying another app.
Why the value may hold up from month to month
After the first week, the main benefit becomes habit. If I send money regularly, the app’s value comes from reducing the number of decisions around that task. I know which app to open, what information I need nearby, and which review points deserve attention. A focused tool can become part of a routine in a way that a much larger finance app sometimes cannot.
The strongest recurring use case is a predictable transfer pattern. Someone might send support to a family member, handle a repeated personal obligation, or manage transfers while traveling between places. In those situations, the app is not competing with entertainment or novelty. It is competing with friction: finding a location, remembering a website, locating an old message, or navigating a crowded financial dashboard.
The practical advantage is also psychological. When money tasks are scattered across several services, I am more likely to postpone them or begin the wrong process. A dedicated transfer app gives the task a visible home. That can be valuable for users who prefer a simple routine: open the app, prepare the details, review them, and finish.
Still, recurring value depends on the user’s actual transfer frequency. If I only need this type of service once every few months, I may not remember the workflow well enough for the app to feel faster than an alternative. In that case, keeping it installed could create clutter without producing much benefit. I would rather remove it and reinstall when needed than maintain an app that does not serve a regular purpose, provided that doing so fits my own account and security habits.
A second useful tip is to create a personal pre-transfer checklist outside the app. I would keep the recipient’s exact details, the intended amount, and the reason for the transfer ready before opening Elektra Go. This reduces rushed typing and makes the app’s focused design more effective. It also helps separate preparation from confirmation, which is a safer habit than trying to remember everything while moving through the screens.
Another non-obvious trade-off is the difference between convenience and centralization. A dedicated transfer app may make one task easier, but it also means financial activity is divided between apps. If I need to reconcile transfers with my broader budget, I may still have to check another banking or budgeting tool. Elektra Go can streamline the sending step without becoming the single place where I understand my complete financial position.
That limitation does not make it a poor choice. It simply means I would use it as a specialized instrument rather than expecting it to replace my bank, my budget, and every other payment method. The best long-term setup is often a small collection of tools with clearly separated jobs, not one application forced to do everything.
Who is likely to get the most from it
I see the clearest fit for people who send money often enough to build a routine, prefer handling the task from a phone, and want a finance app centered on transfers rather than a broad collection of services. It may also suit users who are comfortable checking details independently and who value having a mobile option available when visiting a physical location is inconvenient.
It is less convincing for someone whose financial life already revolves around a bank app that handles transfers smoothly. It is also not my first recommendation for a user who needs extensive budgeting, investment tracking, bill management, or a unified account overview. Those needs call for a broader financial platform, while Elektra Go appears most useful when its narrower purpose matches the job.
The age rating and older Android compatibility make it approachable from a device-availability perspective, but accessibility is not the same as suitability. A person may be able to run the app and still prefer a different service because of recipient habits, transfer frequency, or the need for in-person assistance. I would make that comparison before moving an established routine.
The maintenance burden behind a simple transfer app
A finance app can look simple while still requiring responsible maintenance from the user. I would keep the operating system reasonably current, install app updates when they are offered, and avoid using a shared or unsecured phone for sensitive financial tasks. These are ordinary precautions, but they matter more for a transfer tool than for an app used only to read or watch content.
I would also review the app before an important transfer rather than assuming that familiarity removes all risk. Interfaces change, account details can be entered incorrectly, and a recipient’s circumstances can change even when the app itself feels unchanged. A quick pause before confirmation is a small maintenance habit with a large practical benefit.
There is a difference between maintaining the app and maintaining the surrounding routine. The app may be ready, but the user still needs accurate recipient information, a clear record of what was sent, and a way to reconcile the transaction with personal finances. I would save confirmation information in the method I normally use for financial records, rather than relying on memory or assuming that one app will provide every organizational feature I need.
That is one reason I would not describe Elektra Go as completely hands-off. Its purpose may be focused, but the responsibility for a correct transfer remains shared between the service and the person using it. The app can make the process more convenient; it cannot decide whether the recipient details are correct or whether the amount fits the user’s budget.
For a household, maintenance may also involve agreeing on who uses the app and how transfer information is recorded. If several people send money from different phones, a simple shared record can prevent duplicate transfers or confusion. This is a practical workflow improvement that is easy to overlook because the app itself is only one part of the process.
Where fatigue can appear over time
The first source of fatigue is repetition without enough personalization. If I send money frequently but must re-enter the same information each time, the process may begin to feel tedious. I would pay attention to whether the workflow genuinely shortens my routine or merely moves it onto a phone. A dedicated app earns long-term value only when it reduces effort in a noticeable, repeatable way.
The second is divided attention. Mobile transfers are convenient, but phones are full of interruptions. I would avoid beginning a transfer while rushing between tasks, especially if I am copying details from a message. The very convenience that lets me send money anywhere can also encourage me to do it too quickly. My best practice would be to complete the process in one quiet session.
The third is uncertainty around the surrounding transaction. Even when an app is easy to navigate, users may still wonder about timing, recipient access, or what to do if something does not look right. Those questions can make a supposedly quick task feel stressful. My advice is to treat the final review as a deliberate checkpoint and keep any confirmation details until the recipient has acknowledged the transfer.
There is also the fatigue of app accumulation. Because Elektra Go is free, installing it carries little immediate financial hesitation, but free apps still consume attention and maintenance. If I use it only once and already have a reliable alternative, it may not earn permanent space. The right decision is based on repeated usefulness, not on the absence of an upfront price.
One further trade-off concerns device age. Support for Android 8.0 or later is helpful for older phones, but an older device can still have limited performance, storage, or security support outside the app. I would not confuse compatibility with a guarantee of a smooth or secure overall phone environment. For financial activity, the condition of the device and operating system remains part of the decision.
Users who dislike handling financial tasks digitally should also think carefully before switching. A mobile interface can remove travel and waiting, but it removes some of the reassurance that comes from speaking with a person. If I needed guidance for an unfamiliar transfer, I would choose the option that gives me the right level of support, even if it is less convenient.
Does Elektra Go earn lasting space?
My long-term verdict is positive but specific. Elektra Go makes sense as a focused money-transfer app for someone whose routine matches its purpose. Its free availability, broad age rating, support for Android 8.0 and later, and established presence of over 100K installs make it easy to consider. The 4.5 average from 534 ratings also indicates that the core experience has connected with many users.
But I would not recommend it as a universal finance app. If I wanted one place for banking, budgeting, bills, and transfers, I would look toward a broader financial application. If my recipients already use another payment service, that existing network might be more convenient. If I transfer money rarely or strongly prefer personal assistance, a physical or more familiar alternative may serve me better.
For the right user, the app’s lasting value comes from a modest promise: make a recurring transfer task available from the phone and keep the purpose clear. That is enough when it removes a real obstacle from everyday life. It is not enough when the app becomes another unused icon or when the user expects it to manage every part of their financial life.
I would give it a trial built around one real transfer routine, not a casual installation. Prepare the necessary information, complete the process without rushing, record the result, and then ask whether the app made the task easier than the alternative I normally use. If the answer stays yes over several occasions, Elektra Go has earned its place. If the answer is only yes because it was new, the novelty has already revealed its limit.
In short, I see Elektra Go as a practical specialist rather than a complete financial command center. For people who regularly need its particular transfer workflow, that specialization can be exactly what makes it useful. For everyone else, the better choice may be the service already integrated into their daily money habits.
Pros
- Fast transfers between participating Elektra locations and supported accounts.
- Clear transaction tracking helps you monitor transfer status.
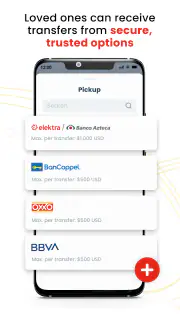
- Useful pickup option for recipients without a traditional bank account.
- Available on both Android and iOS devices.
- Can simplify recurring remittances to family members.
Cons
- Transfer availability depends on the recipient’s country and local partners.
- Fees and exchange rates may vary by destination and payment method.
- Recipients may need valid identification to collect cash.
- Support response times can differ during busy periods.
- Some features require location
- identity
- or financial information.
FAQ's for Elektra Go: Money Transfer
What is Elektra Go: Money Transfer used for?
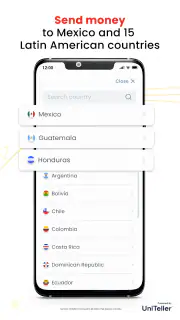
Elektra Go: Money Transfer is designed to help users send and receive money conveniently, manage transfer-related transactions, and access financial services through a mobile device. Depending on your location and account eligibility, the app may support transfers to other users, cash pickup, or deposits to a bank account. Available features can vary by country and service conditions.
Do I need an account or identification to use Elektra Go?
In most cases, you must register an account and provide accurate personal information before completing money transfers. Elektra Go may request identity verification documents, phone confirmation, or additional details to comply with financial regulations and prevent fraud. The exact requirements depend on your country, transfer type, transaction amount, and whether you are sending or receiving money.
Are there fees or limits when sending money with Elektra Go?
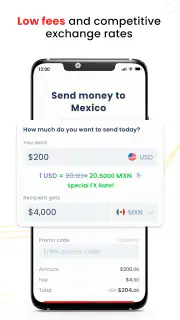
Transfer fees, exchange rates, and transaction limits may apply when using Elektra Go: Money Transfer. The total cost can depend on the destination, payment method, delivery option, currency, and amount being sent. Before confirming a transaction, carefully review the displayed fee, exchange rate, recipient information, and final amount, since conditions may differ by region.
How long does a transfer take, and can I track it?
Transfer speed depends on the selected delivery method and destination. Some transactions may be available quickly, while bank deposits or transfers requiring additional verification can take longer, especially during weekends, holidays, or periods of high demand. The app generally provides transaction details or a reference number that can help you monitor the transfer status.
Is Elektra Go: Money Transfer safe to use?
Elektra Go uses account access controls and transaction verification measures intended to protect users and reduce unauthorized activity. However, users should still take precautions by downloading the app from an official store, using a strong password, protecting verification codes, and checking recipient details before sending money. Never share login credentials or one-time security codes with anyone.