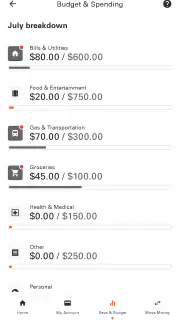
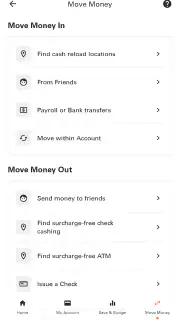
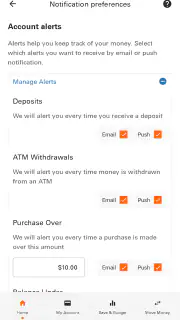
Money Network® Mobile App
Android OnlyFree· User Rating
I found Money Network® Mobile App most useful when I treated it as a quick window into my Money Network Account rather than as a complete replacement for every financial tool I use. That distinction matters. The app is free, aimed at everyone, and built by Fiserv, Incorporated, but its real value depends on whether your everyday money is already connected to Money Network. If it is, the app can make checking your available balance and account activity much less inconvenient than relying on a browser or waiting until you are near a computer.
My review centers on that simple capability: fast access to account information while you are away from home. It sounds modest, yet it can change how confidently you handle small purchases, bills, and unexpected expenses. The app is not trying to be a full budgeting suite in my experience. Its strength is giving me a practical way to look before I spend, especially when the amount available in the account is more important than a long list of extra financial tools.
Why quick account access is the app’s real strength
Money Network® Mobile App belongs in the finance category, but I would not approach it like a general banking super-app. The store summary presents it as a way to reach Money Network Account information anytime and anywhere, and that description fits the role I noticed most clearly. I open it when I need a current view of my money, not when I want to research investments, build a detailed household plan, or compare financial products.
That focused purpose is helpful for people who prefer a direct experience. There are fewer reasons to wander through a complicated financial dashboard when the immediate question is simply, “Can I safely make this purchase?” A quick check can prevent an awkward declined transaction or help me decide whether an expense should wait. For someone who receives or manages funds through a Money Network Account, that kind of access can be more useful than a feature-heavy app that requires several steps to reach the information that matters.
The app has been available since March 26, 2013, and its current version is 20.0.1. It supports Android 7.0 and later, which makes it accessible on many older devices as well as newer phones. That broad compatibility is practical, although users with very old hardware should still expect the experience to depend on the phone’s speed and operating system condition. The application has passed five million installs, with an average rating of 3.1 from roughly seventy-two thousand ratings and thirty-six thousand reviews. I read that combination as a sign of a useful but not universally smooth experience: plenty of people find a purpose for it, while a noticeable group encounters friction.
What the capability changes in everyday use
The biggest difference is timing. Without mobile access, checking account information can become something I postpone until I have a laptop, a stable browser session, or enough time to navigate a website. That delay is not harmless when several small purchases are involved. A balance that looked comfortable earlier can feel very different after groceries, transport, and an automatic payment have all been processed.
With the app available on my phone, I can make the check part of the decision itself. Before paying for an unplanned item, I can open the account view and decide based on what is actually available rather than relying on memory. I find this especially valuable when I am moving between places and do not want to carry a paper record or calculate every transaction manually.
There is also a useful psychological effect. Seeing account information regularly can make spending feel more concrete. I am less likely to treat an amount in my head as “probably fine” when I can pause and look at the account first. That is not the same as a budgeting system, but it is a simple habit that can improve awareness without demanding a complicated setup.
How I would use it in practice
I would begin by installing the app on the phone I actually carry, then signing in to the Money Network Account it is intended to access. The important workflow is not installation itself; it is building a reliable checking habit. I would use it before larger discretionary purchases, after a cluster of small transactions, and whenever I need to confirm the account position before making a payment.
A realistic example is a weekday when I have already paid for breakfast, transport, and a few household items. Later, a friend invites me to dinner. Instead of estimating what remains, I can check the account immediately and decide whether the meal fits comfortably or whether I should choose a cheaper option. That tiny pause is where the app earns its place. It turns account awareness from a task I might remember later into information available at the moment I need it.
I would also use the app as a transaction-review checkpoint. If the available amount does not match my expectation, I can stop and investigate before continuing to spend. The useful insight here is that the app works best as a decision tool before spending, not merely as a place to look after something has gone wrong. Checking first gives the information a practical consequence.
For a more disciplined routine, I would check at consistent points rather than opening it constantly. A morning glance can establish a starting point, while an evening review can help me remember which purchases affected the account. I would not confuse that routine with formal bookkeeping, but it can provide a lightweight record of my own behavior and make unusual changes easier to notice.
Small habits that make the app more useful
One non-obvious advantage of a mobile account tool is that it can reduce memory-based spending decisions. I do not need to remember the balance from yesterday or assume that a recent transaction has already settled. I can check the current account information at the point of choice. That is particularly useful for people whose income or available funds require close attention between pay periods.
A second useful habit is to check after several low-cost purchases rather than dismissing them individually. Small expenses are easy to overlook because none feels important alone. Looking at the account after a series of them gives me a more honest picture of their combined effect. This is not a special budgeting feature; it is a practical way to use the app’s central strength more intelligently.
A third trade-off is worth understanding: frequent checking can improve awareness, but it can also create false confidence if I treat the displayed information as a complete financial forecast. The app helps me see the Money Network Account, yet my wider financial situation may include obligations or accounts outside it. I would use the mobile view as one reliable reference point, not as a complete picture of every financial commitment I have.
Another good workflow is to check before making a purchase that would leave little room for error. When the remaining amount is tight, the value of immediate information rises sharply. When the account has plenty of room, checking may be less important. In other words, the app is most powerful when uncertainty has a real consequence.
The best scenario, and where the limits appear
Who benefits most from the mobile format
The strongest fit is someone who already uses a Money Network Account and wants convenient access during ordinary daily activity. That could include a person managing a limited spending balance, someone who travels between work and home, or anyone who dislikes logging into a desktop site for a quick account check. The app’s free price also removes a direct cost barrier, which makes it easier to try as a companion to the account.
I can also see value for users who are not interested in elaborate financial software. Many finance apps ask me to connect multiple accounts, categorize spending, create targets, and interpret charts. Those tools can be excellent for a person who wants a full financial overview, but they can be unnecessary when the immediate need is simply access to one Money Network Account. This app’s narrower purpose may feel clearer and less demanding.
The best scenario is therefore not “everyone who wants a finance app.” It is “someone who needs a convenient mobile view of this particular account.” If that describes you, the app can remove a recurring point of friction. If it does not, the central benefit becomes much less relevant.
Where it falls short compared with alternatives
Compared with a full-service banking application, Money Network® Mobile App feels more specialized. A typical bank app may combine account access with broader money management, multiple account types, payment tools, planning features, and richer financial history. I would choose that kind of alternative if I wanted one place to manage several institutions or build a detailed view of my finances.
Compared with a dedicated budgeting app, this application is also less suitable for long-term analysis. A budgeting-focused tool is usually the better choice when I want categories, spending trends, shared household planning, or a month-by-month review. I would not install this app expecting it to replace that kind of system. Its advantage is immediacy, not depth.
There is a similar distinction with a mobile browser. A browser can sometimes provide access without adding another dedicated app, and that may be preferable for someone who rarely checks the account. The application becomes more worthwhile when I check often enough that a focused mobile experience saves time and reduces repeated navigation.
The 3.1 average rating is a useful caution before installing. It does not erase the app’s practical purpose, but it suggests that convenience should not be mistaken for a flawless experience. In my view, users should approach it with realistic expectations: it is a focused account-access tool, and the quality of that experience matters more than a long list of promised extras.
Questions I would ask before relying on it
“Is it suitable for managing several unrelated accounts?” I would say no as a primary solution. Its natural role is access to a Money Network Account. If my financial life is spread across multiple banks, cards, and savings products, I would pair it with another tool or choose a broader finance application.
“Can it replace a budget?” Not for me. It can support a budget by making account checks easier, but it does not become a complete spending plan simply because I can view the account on a phone. I would still use a separate method for bills, goals, categories, and future commitments.
“Is it useful if I only check my balance once a month?” Probably less so. Occasional users may find a browser sufficient, while frequent users gain more from having account access close at hand. The value grows with the number of moments when a quick check can prevent an avoidable mistake.
“Will it help me notice unusual account activity?” It can make reviewing account information more convenient, which gives me more opportunities to notice something unexpected. I would still review carefully and avoid assuming that a quick glance is a complete security check. The responsible approach is to investigate anything that does not match my own activity.
“Who should skip it?” I would skip it as a main finance app if I need investment management, detailed budgeting, consolidated accounts, or advanced financial reporting. I would also avoid depending on it as my only money-management method if my decisions involve accounts the app does not represent. Its narrow focus is a strength for the right user and a limitation for everyone else.
My final recommendation
After using it with the right expectations, I see Money Network® Mobile App as a practical companion rather than an all-purpose financial command center. The ability to reach account information quickly can make daily spending decisions calmer and more deliberate. That is a real benefit, especially when I need to know what is available before buying something rather than reconstructing the answer afterward.
At the same time, I would not recommend it simply because it is in the finance category. Its usefulness depends on having a Money Network Account and wanting convenient mobile access to that account. People seeking detailed planning or a consolidated financial dashboard should look toward a broader alternative instead.
For the intended user, the best approach is simple: install it, establish a regular checking routine, and use the information before important spending decisions. I would treat the app as a quick reference, combine it with a separate budget when necessary, and keep its limitations in view. My recommendation is positive for account access, but conditional for full financial management.
With an Everyone content rating, a free price, and support beginning at Android 7.0, it is easy for many people to try. Just remember what makes it valuable: not a large collection of financial features, but the ability to bring one account’s information into the moments when a quick, informed choice matters.
Pros
- Quick access to balance
- transactions
- and available funds
- Convenient mobile check deposit for eligible users
- Card controls help manage spending and protect the account
- Transaction alerts can make unusual activity easier to spot
- Useful for receiving and managing employer or benefit payments
Cons
- Some features may depend on your employer or program eligibility
- Check deposits can be subject to review and processing delays
- Support options may be limited outside business hours
- A compatible device and stable internet connection are required
- Fees may apply to certain transactions or out-of-network services
FAQ
What is the Money Network® Mobile App used for?
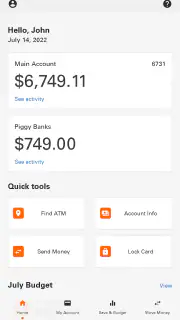
The Money Network® Mobile App is designed to help eligible cardholders manage their Money Network account from an Android or iOS device. After signing in, users can typically review their available balance, monitor transactions, receive account notifications, locate participating ATMs, and manage selected card settings. The exact tools available may depend on the card program, employer, benefits provider, or region connected to the account.
How do I register or sign in to the Money Network® Mobile App?
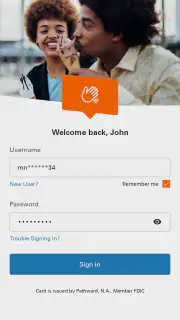
To use the app, you generally need an active Money Network account or eligible Money Network card. Registration may require personal information, card details, identity verification, and creation of login credentials. During testing, the sign-in process was straightforward, although verification codes and security checks may be required. Users should download the official app, keep their contact information current, and avoid sharing passwords or one-time security codes.
Can I use the app to check my balance and transaction history?
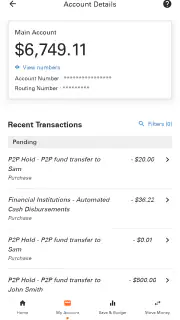
Yes, checking account activity is one of the app’s main purposes. Once signed in, users can usually view their current or available balance and review recent purchases, deposits, withdrawals, fees, and other transactions. The displayed balance can change as transactions are authorized or posted, so it may not always match pending activity immediately. Reviewing the history regularly is useful for spotting unfamiliar charges quickly.
Does the Money Network® Mobile App help me find ATMs or manage my card?
The app commonly includes tools for locating nearby ATMs and accessing card-management features, although the options can vary by account type. Depending on the program, users may be able to review ATM information, lock or unlock a card, report it lost or stolen, update selected settings, or contact support. ATM availability, fees, withdrawal limits, and card controls should always be confirmed within the app and the cardholder agreement.
Is the Money Network® Mobile App safe, and what should I do if I have a problem?
The app is intended to provide secure access to Money Network accounts through login protection and account verification, but users should still follow basic security practices. Install it only from the official Google Play Store or Apple App Store, keep the operating system updated, and avoid signing in on public or unsecured networks. If the app is unavailable, a card is lost, or a transaction looks suspicious, use the official support options printed on the card or shown in the app.