
Skrill - Fast, secure payments
For Android and iOSFree·User Rating
 Analysis by ViaAPK
I find Skrill most useful when I treat it as a dedicated digital wallet rather than a replacement for every way I pay. That distinction shapes how I use it: I keep a clear reason for moving money into or through the app, check the details before confirming, and avoid assuming that a quick transfer is automatically the cheapest option. For someone who regularly sends money or pays online, that simple routine can make the service easier to manage.
A repeatable routine beats tapping in a hurry
My baseline workflow is deliberately simple. I open the app, check the balance and recipient or payment details, review any displayed costs or conversion information, and only then confirm. Afterward, I look at the transaction record and notification rather than relying on memory. That last step is especially useful when I have several payments to keep straight.
A realistic example is splitting a shared expense with someone who uses Skrill. I would first agree on the amount and currency, then verify the recipient details carefully before sending. If the payment involves a currency conversion, I would pause to inspect the rate and total shown in the app. This avoids the small but common mistake of focusing on the amount sent while overlooking what the other person is meant to receive.
That habit also helps when using a digital wallet at online checkout. I treat the checkout screen as a final review, not a formality: confirm the amount, make sure I am using the intended account, and save or check the receipt afterward. If a purchase is urgent, this brief check is still worth the moment it takes.
Settings and checks that matter in daily use
For a finance app, security settings deserve attention before convenience. I would review the available account-protection options, use two-factor authentication where available, and keep access details private. Notifications are useful as an early warning and as a personal record, but they do not replace checking the transaction history when something looks unfamiliar.
I also recommend making a small habit of reviewing account activity after a busy day of payments. A notification can be easy to dismiss, especially when several arrive close together. Looking at the history lets me match each entry to a purchase or transfer and notice a payment I do not recognize while the context is still fresh.
When a payment crosses currencies, I check the displayed conversion information before committing rather than doing mental arithmetic afterward. A rate that looks reasonable is only one part of the decision: the final amount and any applicable charges matter too. If the total is not clear to me, I stop and compare the options before proceeding instead of treating speed as the only priority.
News Worth Your Time
Brain Test 2 Suits the Stop-and-Start Rhythm of Modern Phones
Google Play Games Makes Android Gaming Easier to Navigate, Not Easier to Love
WhatsApp Under Pressure: How Well It Recovers When Messages Fail
UNO!™ Beyond the Table: How Rivalry Keeps Players Coming Back
LinkedIn: Dominating the Professional Networking Arena
Unlocking the Full Potential of Pixel Art - Color by Number
Roblox: A Creative Revolution in Gaming
Why Gallery Stands Out in the Photo App World
How Pi Network is Revolutionizing Social Cryptocurrency
Google TV's Ecosystem Strategy: Redefining Streaming
How Little Panda: Princess Makeup Thrives with New OS Updates
Why Decor Life - Home Design Game Stands Out in Creative Simulation
Where Skrill fits among payment choices
Skrill is a finance app from Paysafe Holdings UK Limited. It is free to install, rated for Everyone, and has been available since 2014. Its current version is 3.174.0-2025112415, and it requires Android 7.0 or later. The app has a 4.6 average from around 228,000 ratings, with more than 10 million installs. Those figures suggest it has a substantial audience, though popularity alone cannot tell me whether it suits a particular payment.
Compared with a bank transfer, a wallet can feel more convenient when both people already use the same service or when an online seller offers it at checkout. A bank app may be the better choice for someone who wants to keep everyday finances in one place or prefers the payment options already attached to their account. For card payments, using a familiar card can be simpler when it is accepted and the total is clear. I see Skrill as an additional route, not an automatic winner over those alternatives.
The app may suit people who make online payments, send money to other users, or deal with more than one currency and value having those activities in a wallet. It is less compelling if you make few digital payments, do not want another account to monitor, or need certainty about the complete cost before choosing a transfer. In those cases, compare the amount you will pay and receive with a bank or card option first. The practical question is not merely whether a payment can be made, but whether this route is the clearest fit for that specific transaction.
Limits, costs, and useful habits
There are trade-offs to keep in view. “Fast” does not mean every transfer will be free, or that every payment will suit every recipient. Costs can depend on the transaction, so I would read the fee and conversion details presented for that payment rather than assume the same terms apply each time. If the displayed total is unclear, I would not confirm until I understood it.
I also would not use a wallet balance as a substitute for a budget. Before moving money into an app, decide what the funds are for and keep track of what remains. That is a small but useful discipline when online shopping and person-to-person payments share the same wallet: separating planned spending from money set aside for another purpose makes accidental overspending less likely.
For repeat payments, I rely on consistency rather than imagined shortcuts. Keep recipient details and the intended currency in mind, check each payment afresh, and review the resulting record. Even when a recipient is familiar, a quick confirmation can prevent a wrong-amount or wrong-person mistake. The few seconds spent verifying details are a better kind of efficiency than rushing and having to resolve an error later.
Who will get the most from it
Skrill makes the most sense to me for someone who has a recurring reason to use a digital wallet: paying online, sending money to a contact who already accepts it, or handling transactions involving different currencies. It can also be handy for people who prefer to separate these payments from their main bank account, provided they are comfortable keeping another account secure and checking its activity.
It is not my first recommendation for someone who only needs an occasional transfer and already has a familiar, straightforward bank or card option. Nor would I choose a payment method just because it appears quick if the recipient cannot use it easily or the total cost is hard to compare. Before relying on Skrill for an important payment, I would make sure the recipient and payment route work for that situation and review the final details in the app.
Getting Started with Skrill
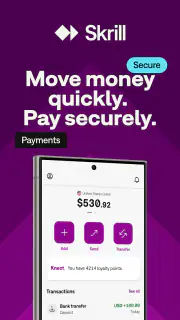
Signing up for Skrill is a breeze. I remember thinking, "Oh boy, here comes another app that’s going to ask for my life’s history," but I was pleasantly surprised. A few taps, and I was in. The interface is as user-friendly as it gets, with a clean design that doesn’t clutter your screen with unnecessary information. It’s like the app just gets me, you know?
Features That Make Life Easier
What I love most about Skrill is its versatility. It’s not just about sending money; it’s about doing it securely and efficiently. Whether you’re sending cash to a friend across town or paying for services overseas, Skrill has got your back. Plus, if you’re into online shopping, Skrill’s integration with various platforms makes checkout as smooth as silk.
And let’s talk about the currency conversion feature. If you’re like me and deal with multiple currencies, this is a lifesaver. No more manual calculations or getting ripped off by lousy exchange rates. Skrill gives you real-time rates, and let me tell you, it feels empowering.
Security You Can Trust
Security is a big deal for me, and I’m sure it is for you too. With Skrill, I feel like my money is protected by a fortress. They’ve got this two-factor authentication that adds an extra layer of security. It’s like having a bouncer for your wallet.
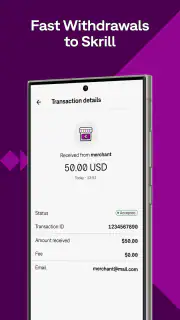
Moreover, the app notifies you of every transaction. This way, you can catch any sneaky activity before it becomes a problem. It’s reassuring to know that Skrill has my back, 24/7.
Handling Fees and Transfers
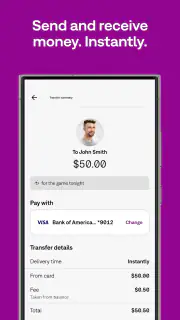
Now, let’s chat about fees because nobody likes those, right? Skrill is pretty transparent about its fees, which I appreciate. While it’s not free, the cost is reasonable, especially when you consider the convenience and security it offers. Think of it as paying a small price for peace of mind.
Transferring money is quick, and you can track your transactions in real-time. Whether you’re sending or receiving, it’s all done in the blink of an eye. I’ve never had to wait long, and that’s a huge plus in my book.
Final Thoughts
In a world where digital payments are becoming the norm, Skrill stands out as a reliable and efficient option. It’s like having a financial assistant that works around the clock, and I can’t imagine going back to the old way of doing things. If you’re looking for a fast, secure, and versatile payment app, give Skrill a shot. You won’t regret it. Trust me, it’s worth every penny.
Pros
- User-friendly interface for easy navigation.
- Supports multiple currencies for global users.
- Provides instant transaction notifications.
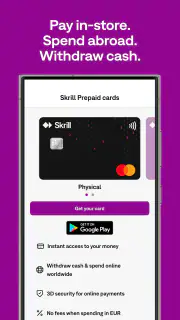
- Offers a prepaid card for offline purchases.
- Highly secure with two-factor authentication.
Cons
- High fees for international transactions.
- Limited customer support availability.
- Verification process can be lengthy.
- Not widely accepted by all merchants.
- Occasional app performance issues.
FAQ's for Skrill - Fast, secure payments
What is Skrill and how does it work?
Skrill is a digital wallet service that allows users to make fast and secure online payments. It works by enabling users to store their payment information in one place, making transactions more convenient. Users can send money to other Skrill users, pay for goods and services online, or withdraw funds to their bank accounts. It's widely used for online shopping, gaming, and trading.
Is Skrill safe to use for online transactions?
Yes, Skrill is considered safe for online transactions. It uses advanced security measures, including two-factor authentication, encryption, and fraud prevention tools, to protect users' financial information. As with any online service, users are advised to keep their passwords secure and monitor their accounts regularly to ensure their safety.
Are there any fees associated with using Skrill?
Skrill charges fees for certain transactions, such as sending money to an email or another Skrill wallet, currency conversion, and withdrawing funds to a bank account. However, receiving money and making purchases with Skrill are typically free. Users should review Skrill's fee structure on their website to understand any costs they might incur.
How can I add funds to my Skrill account?
Users can add funds to their Skrill account through various methods, such as bank transfer, credit or debit card, and other local payment options depending on their region. Once the account is funded, users can use the balance for online purchases, sending money, or withdrawing to their bank account. Skrill provides detailed instructions for each funding method on their platform.
Can I use Skrill internationally?
Yes, Skrill supports international transactions, allowing users to send and receive money across borders. It supports multiple currencies, making it convenient for users who engage in international trade or travel. However, users should be aware of potential currency conversion fees and exchange rates when using Skrill for international payments.