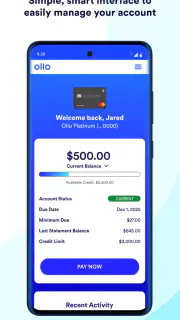

Ollo Credit Card Mobile App
Android OnlyFree·User Rating
 Analysis by ViaAPK
Managing a credit card from a phone sounds simple, but the quality of the experience depends on whether the app helps with the small decisions that happen between purchases: checking what is available, reviewing recent activity, and staying aware of the account before a payment or another charge. That is the role I see for Ollo Credit Card Mobile App, a free finance app from Merrick Bank for people who use an Ollo credit card.
My overall impression is that it is best understood as a focused account-management tool rather than a complete personal-finance platform. It is designed around the card itself, so the experience makes the most sense when I want a direct way to keep an eye on that account instead of combining several banks, cards, investments, or budgets in one place. For a first-time user, that narrower purpose is actually reassuring: there is less to learn, but also less flexibility than I would expect from a broader finance app.
What to expect before you begin
The app belongs to the finance category and carries an Everyone age rating, which fits its practical purpose. It is available at no cost, and the current release is version 4.49.11. The app supports devices running Android 6.0 or later, so compatibility should be comfortable for many older Android phones as well as newer models.
Merrick Bank is the developer, and the app has passed the hundred-thousand-install mark. Its average rating is 3.6, based on a little over three hundred ratings, with more than one hundred eighty written reviews. I would read that as a mixed but usable reception rather than a sign that every cardholder will have the same experience. A finance app can be perfectly useful for one routine and frustrating for another, especially when the user expects a full banking replacement.
The first important expectation is scope. This is for managing an Ollo credit card, not for replacing every financial service on a phone. I would not install it expecting a household budget planner, a general-purpose bank dashboard, or a tool that brings unrelated accounts together. Its value comes from keeping card-related tasks close at hand.
That focus also affects who should choose it. If I already have an Ollo card and want a dedicated mobile route to the account, this is the natural app to try. If I do not have an Ollo card, the app is unlikely to become useful simply because I need a finance app. Someone looking for investment tracking, bill organization across many providers, or a broad spending-analysis system should look at a different kind of product.
The first-time user’s sensible goal
I would begin with one modest goal: reach the account view and confirm that the card information shown there matches what I expect. That is more useful than trying to explore every screen immediately. Once I know the account is connected and recognizable, I can use the app for a real task instead of treating setup as the finish line.
News Worth Your Time
Brain Test 2 Suits the Stop-and-Start Rhythm of Modern Phones
Google Play Games Makes Android Gaming Easier to Navigate, Not Easier to Love
WhatsApp Under Pressure: How Well It Recovers When Messages Fail
UNO!™ Beyond the Table: How Rivalry Keeps Players Coming Back
LinkedIn: Dominating the Professional Networking Arena
Unlocking the Full Potential of Pixel Art - Color by Number
Roblox: A Creative Revolution in Gaming
Why Gallery Stands Out in the Photo App World
How Pi Network is Revolutionizing Social Cryptocurrency
Google TV's Ecosystem Strategy: Redefining Streaming
How Little Panda: Princess Makeup Thrives with New OS Updates
Why Decor Life - Home Design Game Stands Out in Creative Simulation
A good first session should answer practical questions. Can I get into the account without confusion? Can I identify the relevant card? Can I find the current account information I need before making a decision? If those steps feel clear, the app has already earned a place in my routine.
Setting it up without making the first session harder
I recommend installing the app when I have the card and account details nearby. That avoids turning registration or sign-in into a guessing exercise. I would also use the same personal information associated with the card account rather than trying to create a separate identity for the mobile app.
The safest approach is to move slowly through the opening screens and read each prompt before continuing. With a financial account, rushing is rarely worthwhile. I would check the app name and developer before entering anything sensitive, then follow the account-access process presented inside the official application. Once signed in, I would take a moment to confirm that the account context is correct before relying on any displayed information.
One useful habit is to treat the first login as a verification session, not as a full account-management session. I would look for the card and the main account area first, then close the app and reopen it later if I want to test whether returning to the account feels straightforward. That small pause can reveal whether I understand the navigation or whether I was only following the initial prompts.
I would also avoid making an important payment decision while distracted during setup. If the app presents account information that I need for a deadline, I would compare it with the card statement or another trusted account record before acting. The app can make access more convenient, but convenience should not replace checking the exact account details when timing matters.
What a successful setup looks like
For me, setup is successful when I can open the app, recognize the account, and reach the information I came for without repeating the entire registration process. That is a better test than simply completing the first screen. A card-management app earns trust through repeatability: the second visit should feel as understandable as the first.
If I share a phone with someone else, I would be especially careful about leaving the account open. A finance app should be treated differently from a weather or recipe app. I would finish the task, return to the appropriate exit or sign-out option if one is available in the account flow, and use the phone’s own security protections rather than assuming the app alone will prevent access.
Another practical tip is to install updates deliberately instead of ignoring them indefinitely. The installed version is 4.49.11, and keeping the app current is a sensible way to avoid using an outdated release. I would still check the app after an update rather than assuming every control is exactly where I remember it.
Reaching the first meaningful success
The first meaningful success is not merely opening the app. It is completing a small card-related task with confidence. For a new user, I would make that task checking the account before a planned purchase. Open the app, locate the card account, review the information shown, and decide whether the purchase fits what I intended to spend. That simple routine demonstrates the app’s central value better than browsing through menus.
A realistic example would be preparing for a grocery trip. Before leaving, I would open the app and check the account information rather than relying on memory from the last time I used the card. After shopping, I would return later to review the activity and make sure the transaction looks familiar. This two-part habit—check before spending and review afterward—turns the app into a useful checkpoint without requiring a separate budgeting system.
I find this workflow particularly helpful for people who do not want constant financial notifications or a complicated dashboard. The app can serve as a deliberate place to check the card when needed. The trade-off is that it may not provide the broader context someone wants, such as a complete view of cash, savings, and several credit accounts together.
Another good first action is reviewing a recent card transaction after using the account. The point is not to obsess over every purchase; it is to build familiarity with how the account presents activity. Once I know where recent charges appear and how the account information is organized, later checks become quicker and less stressful.
A routine that stays useful
I would use the app at three natural moments: before a larger planned purchase, after an unfamiliar-looking charge, and before handling a card-related deadline. Those moments are specific enough to be useful without turning the app into a constant distraction. The best routine depends on the cardholder, but the principle is the same: open it with a question in mind.
For example, if I notice a charge I do not immediately recognize, I would use the app to inspect the account activity, then compare the details with receipts, subscriptions, or household purchases. I would not assume that an unfamiliar description automatically means fraud, but I also would not ignore it. The app is valuable here as a quick starting point for checking what happened.
I would keep a separate note of any payment or dispute reference that matters to me, if I need one for my own records. A mobile account view is convenient, but it is not a substitute for personal organization when a transaction needs follow-up. This is one of the less obvious trade-offs of a focused card app: it can make checking easy while still requiring the user to take responsibility for important records.
Where new users may feel confused
The most common misunderstanding is likely to come from expecting the app to behave like a full banking hub. Because it sits in the finance category, a new user may imagine tools for every part of personal money management. I would set that expectation aside. Its identity is tied to the Ollo credit card, so the useful path begins with the card account rather than with general financial planning.
A second source of confusion is treating the displayed account information as a complete budget picture. A card balance or recent activity view can help me understand the card, but it does not automatically tell me what I can safely spend after considering rent, cash expenses, other cards, or upcoming bills. I would use the app as one input in a spending decision, not as a replacement for a personal budget.
It is also easy to confuse account access with account resolution. If I see a transaction I do not recognize, opening the app is only the first step. I still need to examine the information carefully and use the appropriate account-support route when the issue cannot be settled by reviewing the activity. The app can make the investigation more convenient, but it cannot remove the need for judgment.
Another point worth remembering is that a mobile app does not change the terms of the credit account. It may make information easier to reach, but it does not make borrowing cost-free or eliminate the importance of payment timing. I would never treat a convenient screen as permission to spend beyond a plan I can realistically manage.
Small habits that prevent bigger mistakes
I would avoid checking the account only after something goes wrong. A brief review before a planned purchase can prevent the awkward situation of discovering that the account does not match my assumption at the checkout. The habit takes little effort and gives the app a clear purpose.
I would also avoid relying on memory when comparing transactions. If a charge seems unfamiliar, I would check the date, merchant context, and my own receipts before reaching a conclusion. That is a more reliable workflow than repeatedly refreshing the same screen or immediately labeling a normal purchase as suspicious.
Finally, I would keep the app’s role separate from my broader financial records. If I use spreadsheets, a budgeting app, or paper notes, I would update those deliberately rather than assuming the card app will organize everything automatically. This separation is not a weakness by itself; it is simply the practical consequence of choosing a dedicated card tool over an all-in-one finance service.
How it compares with the usual alternatives
The closest alternative is often the cardholder’s mobile browser. A website may be enough for someone who checks the account rarely and prefers not to install a dedicated app. The app has the more natural advantage for repeated phone access: it keeps the card-management experience in one place and avoids treating every visit like a general web-browsing task.
On the other hand, a browser can be preferable for people who switch between devices or do not want account-related apps stored on a phone. It may also fit users who already have a carefully organized browser routine. I would choose the app when quick, dedicated access matters more than keeping everything browser-based.
General budgeting apps are another alternative, but they solve a different problem. They are usually better when I need to see several accounts together, categorize spending, or understand household cash flow. The Ollo app is the better fit when my immediate question is specifically about the Ollo card. Choosing between them is not really about which app is universally superior; it is about whether I need card access or financial aggregation.
A bank’s broader mobile app may also feel more powerful because it combines checking, savings, transfers, and cards. That wider scope is useful for people who want one financial home. Yet a dedicated card app can be less overwhelming when I only need to inspect one account. I would favor the broader banking app for multi-account management and this one for a focused Ollo-card routine.
Credit-monitoring services should not be confused with this app either. Monitoring tools focus on credit information and alerts, while a card-management app is centered on using and reviewing a particular account. Someone concerned mainly with credit awareness may need a separate service; someone trying to manage the Ollo card may not need that extra layer for everyday checks.
Who will get the most from it
I think the app is a sensible choice for an Ollo cardholder who wants a straightforward mobile checkpoint. It suits people who prefer checking their own account before spending, reviewing activity after purchases, and keeping card tasks separate from a more complicated financial system. It is also approachable for first-time users who would rather learn one focused account view than navigate a large banking platform.
It is less suitable for someone who wants a single dashboard for multiple cards and bank accounts. It is also not the right starting point for a person seeking detailed budgeting, investment tools, or a complete financial plan. In those cases, a broader finance product will likely provide more context, even if it takes longer to learn.
My advice is to judge it by a narrow but important test: does it make your Ollo card easier to check at the moments when you actually need to check it? If yes, its focused design is a strength. If you keep searching for household budgets, unrelated accounts, or advanced financial analysis, you are asking it to be something it was not designed to be.
My recommendation after using it
Ollo Credit Card Mobile App makes the most sense as a dedicated companion for an Ollo credit card. I appreciate the direct purpose because it gives a first-time user a clear path: install it, establish account access, confirm the card view, and use that view for a real pre-purchase or post-purchase check. That path feels more useful than installing it simply because it is labeled as a finance app.
The free price and broad device compatibility make trying it easy, while the 3.6 average suggests that expectations should remain realistic. I would not promise a flawless experience or present it as a replacement for every other money tool. Its strongest quality is focus, and its main limitation is the same focus: it is built around one card relationship rather than a complete picture of personal finances.
For a new user, I would start with one account check, then return after the next card purchase to review the activity. If those two visits feel clear and dependable, keep it as part of a simple card routine. If your real need is budgeting across several accounts, use a broader finance solution alongside it or instead of it. In my view, that is the honest way to approach this app: use it for the Ollo card tasks it handles directly, and choose another tool when your financial questions extend beyond that account.
Pros
- Quickly view balances
- transactions
- and available credit.
- Mobile payment options make card use more convenient.
- Purchase alerts can help users monitor account activity.
- Digital statements reduce paper clutter and are easy to access.
- In-app support provides a convenient way to contact the issuer.
Cons
- Some features may require a stable internet connection.
- Not all account services may be available within the app.
- Notifications can occasionally arrive late or be inconsistent.
- Users may need to verify their identity during sensitive actions.
- Credit card terms and fees are not always easy to understand in-app.
FAQ's for Ollo Credit Card Mobile App
What is the Ollo Credit Card mobile app used for?
The Ollo Credit Card mobile app is designed to help cardholders manage their account from an Android or iOS device. After signing in, users can typically review balances, check available credit, view recent transactions and payment history, make payments, and manage account details. It is intended for existing Ollo customers, so having an eligible card and valid login credentials is generally required.
How can I make a payment through the Ollo Credit Card app?
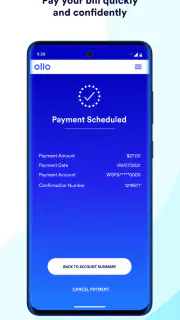
Once you are signed in, the payment section allows you to choose a payment amount, select an available bank account, and schedule a one-time payment or follow the options provided for recurring payments. Before confirming, carefully check the funding account, payment date, and amount. Payment processing times can vary, and submitting a payment does not always mean your available credit will update immediately.
Is the Ollo Credit Card app safe to use?
The app is built for managing sensitive credit-card information, so users should access it only through the official Google Play Store or Apple App Store and keep their device operating system updated. Use a strong, unique password and avoid signing in over unsecured public Wi-Fi. Never share verification codes or login details, and contact Ollo through an official support channel if you notice suspicious activity.
Can I use the app to view transactions, statements, and account activity?
Yes, the app is intended to provide convenient access to important account information, including recent purchases, payments, balances, available credit, and electronic statements when those features are available for your account. Reviewing activity regularly can help you identify unfamiliar charges quickly. Keep in mind that some transactions may initially appear as pending and can change when the merchant completes processing.
What should I do if I cannot log in or the Ollo app is not working?
If you cannot access the app, first confirm that your internet connection is stable and that you are entering the correct username and password. Updating the app, restarting your device, or reinstalling it may resolve common technical problems. If you are locked out, have forgotten your credentials, or see an error that continues, use the official account-recovery or customer-service options rather than relying on unofficial websites or third-party contacts.