
OneBlinc - Financial tools
Android OnlyFree·User Rating
 Analysis by ViaAPK
When an unexpected bill arrives before payday, the problem is often timing rather than a complete lack of income. OneBlinc is a finance app from OneBlinc built around that exact gap: it lets eligible users access wages early and send the money to a linked account. I found the idea straightforward, but the useful part is learning where it fits in a normal budget and where it does not.
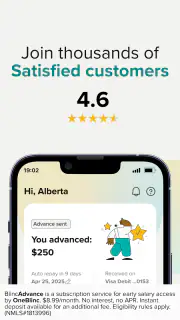
The app is free to download and aimed at everyone, which makes it easy to try without treating it like a complicated banking product. Its store summary describes access to up to 250 dollars in wages through a linked account. That wording matters: this is best understood as a short-term cash-flow tool, not a replacement for savings, a long-term loan solution, or a complete personal-finance system.
How the everyday OneBlinc workflow feels
The basic experience starts with connecting the account that should receive the money and then checking what access is available. I would approach this as a planning step rather than an emergency button. Before requesting anything, I would look at the next pay cycle, the bill that needs covering, and the amount that can be repaid without creating another problem later.
That habit is especially important because early wage access changes timing, not the underlying amount of money earned. If I use it for a utility bill today, the next payday may feel smaller because part of those wages has already been brought forward. The app can help smooth a short interruption, but it cannot make a recurring shortfall disappear.
A realistic example is a paycheck arriving after a scheduled payment. I might use OneBlinc to cover the payment, then record that amount in my budget as money already spent from the upcoming wage. That small manual step prevents the common mistake of seeing the next deposit as fully available and spending twice.
The linked-account approach also makes the destination important. I would check the account details carefully before confirming anything, particularly if I use several bank accounts or recently changed banks. A cash-access app is only helpful when the receiving account is current and usable.
OneBlinc’s current version is 7.12.0, and the app supports Android 7.0 or later. That broad Android compatibility is useful for people who keep an older phone, although I would still install it only through the official app marketplace and keep the operating system updated when possible. Finance apps deserve the same security attention as banking apps, even when their main job is narrower.
News Worth Your Time
Brain Test 2 Suits the Stop-and-Start Rhythm of Modern Phones
Google Play Games Makes Android Gaming Easier to Navigate, Not Easier to Love
WhatsApp Under Pressure: How Well It Recovers When Messages Fail
UNO!™ Beyond the Table: How Rivalry Keeps Players Coming Back
LinkedIn: Dominating the Professional Networking Arena
Unlocking the Full Potential of Pixel Art - Color by Number
Roblox: A Creative Revolution in Gaming
Why Gallery Stands Out in the Photo App World
How Pi Network is Revolutionizing Social Cryptocurrency
Google TV's Ecosystem Strategy: Redefining Streaming
How Little Panda: Princess Makeup Thrives with New OS Updates
Why Decor Life - Home Design Game Stands Out in Creative Simulation
What I would check before making the first request
First, I would make sure my employment and wage information can be recognized through the setup process. The practical question is not simply whether the app installs; it is whether my situation qualifies for the service and whether the requested account can be linked successfully. Eligibility and available access can be more important than the headline amount.
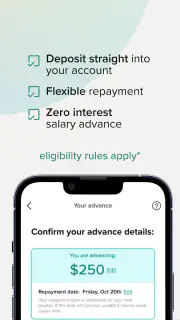
Second, I would read every confirmation screen instead of tapping through quickly. I want to know the amount being accessed, the destination account, and the timing shown for the transaction. If the app presents any service conditions or repayment details, those deserve a pause. A few seconds of checking is worthwhile when the action affects the next payday.
Third, I would begin with the smallest amount that solves the immediate issue. Requesting the maximum simply because it is available can turn a manageable timing problem into a tighter following week. This is one of the most useful ways to use the app responsibly: match the request to a specific expense rather than to a vague feeling of having extra room.
The app has a 4.6 average from around 4.8 thousand ratings, with around 671 written reviews and over 100 thousand installs. Those figures suggest that many people find the concept useful, but they do not remove the need to judge the service against my own income pattern. A positive rating cannot tell me whether my employer, account setup, or timing will work smoothly.
Settings and account details worth reviewing
OneBlinc is not the kind of tool I would open once and leave unattended. I would revisit the linked-account details whenever I change banks, switch payroll arrangements, or close an old account. An outdated destination can create avoidable friction at exactly the moment I need clarity.
I would also review notification behavior on my phone. Alerts are valuable when they help me notice a request, account change, or transaction, but too many notifications can become background noise. The best setup is one that makes money movement hard to overlook without encouraging me to open the app every time I feel short on cash.
Privacy and device security deserve a practical check as well. I would use a screen lock, avoid sharing login details, and be cautious when accessing financial information on a public network. These are not special tricks inside OneBlinc; they are sensible habits for any app handling wage and account information.
Another setting-related habit is keeping the app current. New versions can improve compatibility and fix problems, especially on older Android devices. Since the listed minimum is Android 7.0, the app may be accessible on phones that are no longer recent, but an older device can still have outdated security support. Compatibility should not be confused with complete protection.
Faster patterns for repeat users
Experienced use is less about tapping faster and more about making the same decision consistently. I would create a simple rule: only request money for a named expense, and write that expense beside the expected payday. That turns OneBlinc from an impulse tool into part of a repeatable cash-flow routine.
A second useful pattern is a two-check process. Before requesting access, I would confirm the bill amount and then confirm the amount already committed from the next wage. If those two numbers do not fit comfortably, I would reduce the request or look for another solution. This takes less time than repairing an overdrawn budget afterward.
I would also avoid using the app to cover ordinary spending that can wait. Groceries, transport, or a necessary prescription may justify early access when the timing is awkward, but entertainment and unplanned shopping are different. The distinction is not moral; it is mathematical. A temporary advance is easier to manage when it protects an essential payment rather than expanding discretionary spending.
For someone paid on a regular schedule, the most repeatable workflow is to check the calendar before the need becomes urgent. I would look ahead at rent, utilities, subscriptions, and other fixed payments, then decide whether a timing gap is real. This reduces the chance of making a rushed request late at night or during a stressful moment.
There is also a useful comparison habit. I would check whether moving the bill date, asking the provider for a different payment arrangement, or using an existing emergency fund is cheaper and less disruptive. OneBlinc is convenient when the issue is a short delay in wages, but a fee-free change to a payment schedule may be the better answer when available.
Where the app is strong—and where its limits matter
The strongest part of OneBlinc is its focus. It does not ask me to learn a full investing platform or rebuild my entire financial life before addressing a short-term wage-timing issue. For a worker who has earned money but needs access before the normal deposit, that narrow purpose can be more useful than a general budgeting app.
It is also more direct than relying on a credit card for a small gap. A credit card can remain available for future purchases, while early wage access is tied to money already being earned. That does not automatically make it cost-free or risk-free, but it can make the decision easier to frame: I am bringing forward income rather than adding an open-ended balance to a revolving account.
On the other hand, I would not choose this app as my main budgeting tool. It does not replace a spending plan, a savings account, or a conversation with a creditor. If my income is consistently too low for my fixed expenses, repeatedly accessing wages early may hide the size of the problem and leave each following payday under pressure.
I would also be cautious if my pay varies significantly or if my employment situation is changing. The more uncertain the next wage amount, the harder it is to decide what can safely be accessed now. In that situation, a larger emergency reserve, a nonprofit financial counselor, or a direct arrangement with the bill provider may be more appropriate.
The maximum described by the store summary is up to 250 dollars, but that should not be treated as a guaranteed personal allowance. The useful question is how much I can take without damaging the next budget, not how close I can get to the ceiling. A smaller request can be the more financially mature choice.
Who should use it and who should look elsewhere
I see OneBlinc working best for someone with a predictable wage cycle, a specific short-term expense, and a linked account that is kept up to date. It can be particularly practical when a necessary payment falls just before payday and waiting would cause a genuine inconvenience.
I would recommend more caution for anyone already using several cash-advance services. Combining advances can make the next deposit look committed before it arrives. In that case, adding another app may increase complexity rather than provide relief. Listing every upcoming deduction on paper first is a better starting point.
Someone looking for long-term debt consolidation, credit building, investment guidance, or detailed expense categorization should choose a product designed for that purpose. OneBlinc’s value is its focused wage-access workflow, not a promise to cover every part of personal finance.
The age rating of Everyone makes the app broadly accessible from a content perspective, but financial responsibility still depends on the individual user. I would not interpret that rating as a recommendation for every financial situation. Anyone unsure about the effect on a future paycheck should pause and calculate before proceeding.
What to do when setup or a request stalls
If linking an account does not go smoothly, I would first check the details I entered and confirm that I selected the account I actually want to receive funds. I would also make sure the app and phone are connected reliably, then close and reopen the app before trying again. Repeating the same attempt without checking the basics can waste time and make it harder to tell what changed.
If the account or wage information is not recognized, I would avoid guessing at entries just to move forward. I would review the information for mistakes and use the app’s available support route if the issue remains. A failed eligibility or connection step is not something to fix by entering inaccurate details; it is a reason to pause and clarify the setup.
For a request that appears delayed, I would check the status shown in the app and verify the receiving account rather than submitting another request immediately. Duplicate attempts can create confusion about what is pending. If the status does not answer the question, contacting OneBlinc support with a concise description of the step, account destination, and time of the attempt is more useful than sending repeated vague messages.
When the problem may be outside the app
Sometimes the app is not the source of the delay. A bank account may be temporarily unavailable, a bank may take time to show an incoming transaction, or a scheduled bill may process earlier than expected. I would check the account directly and contact the bill provider if a payment deadline is close, instead of assuming that a screen in the app can resolve every issue.
This distinction matters most when the money is needed for a deadline. OneBlinc can be a useful option to consider, but I would not make a critical payment plan that depends on funds arriving at an exact moment unless the timing displayed is clear. When a deadline is tight, asking the provider about an extension or alternate payment date can be a safer parallel step.
I would also separate technical trouble from a budget problem. If the app works but the amount available does not cover the expense, taking money from another source may only shift the pressure. A payment arrangement, spending adjustment, or advice from a qualified counselor may address the underlying issue better than trying another cash-access service.
My final view after using the workflow
I like OneBlinc most when I treat it as a controlled bridge between earned wages and a near-term essential payment. The app is free, focused, and easier to understand than many broader financial products. Its 4.6 average and growing install base show that the basic idea resonates with users, though my decision would still depend on account compatibility, timing, and personal budgeting.
The key is to build a habit around it: keep the linked account current, check the next payday before requesting money, take only what a named expense requires, and record that amount as already spent. Those steps are more important than finding a clever shortcut because they protect the following week from the most common mistake—forgetting that early access is still part of the same income.
My recommendation is therefore positive but specific. If your problem is a temporary mismatch between when wages are earned and when a necessary bill is due, OneBlinc is worth considering. If the same shortage appears every pay cycle, I would use that pattern as a warning and look for a broader solution instead. In my experience, the app works best as an occasional, deliberate tool—not as a permanent substitute for savings or a sustainable budget.
Pros
- No credit check is required for some eligibility assessments.
- Automatic repayment can simplify managing advances and scheduled payments.
- The app may help users avoid overdraft fees with timely access to funds.
- Clear transaction tracking makes it easier to monitor borrowed amounts.
- Useful financial tools can support short-term budgeting between paychecks.
Cons
- Eligibility and available amounts may vary significantly by user.
- Membership or service fees can reduce the value of frequent borrowing.
- Repayment timing may create pressure before the next paycheck arrives.
- Not all banking institutions or employers may be supported.
- The service is not a substitute for long-term financial planning.
FAQ's for OneBlinc - Financial tools
What is OneBlinc, and what financial tools does it offer?
OneBlinc is a personal finance app designed to help eligible users manage short-term cash needs and everyday money more conveniently. Depending on your account and location, its tools may include paycheck advances, spending or debit features, budgeting assistance, credit-building options, and financial insights. Available services, limits, fees, and eligibility requirements can vary, so review the terms shown in the app before accepting any offer.
Who can use OneBlinc, and what are the eligibility requirements?
OneBlinc is not automatically available to everyone. Eligibility may depend on factors such as your age, residence, identity verification, employment or income information, banking activity, and other criteria used by the service. You may need to connect a qualifying bank account and provide accurate personal details. Approval is not guaranteed, and downloading the app does not mean that every feature will be unlocked.
Does OneBlinc charge fees or interest for its financial services?
The cost of using OneBlinc depends on the specific product or feature you choose. Some services may include membership charges, transfer fees, expedited-delivery fees, or other costs, while the pricing of credit-related products may be disclosed separately. Before confirming a transaction, carefully check the fee schedule, repayment terms, and any applicable disclosures because costs and conditions can change over time.
How quickly can I receive money through OneBlinc?
The time required to receive funds depends on the service selected, your eligibility, bank processing times, verification status, and whether you choose a standard or expedited delivery method. Some transfers may arrive quickly, while others can take longer, especially around weekends or holidays. The app should display an estimated delivery date and any additional fee before you complete the request.
Is OneBlinc safe to use, and what should I know about privacy?
OneBlinc may use security measures such as account authentication, encryption, identity verification, and monitoring designed to protect user information and transactions. However, no online financial service is completely risk-free. Read the privacy policy and account agreement before linking a bank account, use a strong unique password, enable available security protections, and never share verification codes or login details with anyone.