
Cash Advance Now - PayDaySay
Android OnlyFree·User Rating
 Analysis by ViaAPK
When I look at a finance app that offers quick access to borrowed money, I do not judge it only by how fast the opening screen feels. I want to know what the app lets me control, what information it asks me to provide, and whether the borrowing process encourages a calm decision or a rushed one. Cash Advance Now - PayDaySay is aimed at people who need a small payday cash advance and want to handle the request from a phone rather than start with a traditional bank visit.
My overall impression is cautious but practical. The app can make sense as a starting point when an unexpected bill arrives before payday, yet it is not something I would treat like a normal budgeting tool or a permanent source of income. The important question is not simply whether it can help someone get money quickly. It is whether the user can clearly understand the offer, repayment expectations, and information choices before accepting anything.
What Cash Advance Now - PayDaySay is really for
Cash Advance Now - PayDaySay is a free finance app from PayDaySay, with an Everyone age rating and support for Android devices running version 6.0 or later. It was released on December 28, 2022, and the current version is 1.26. Those details make it accessible to a broad range of Android users, including people with older phones who may not be able to install newer finance applications.
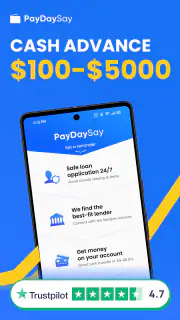
The app’s purpose is narrow: it helps users look for an instant payday cash advance when they need extra money. That focus is useful because the experience is not presented as a full banking replacement. I would open it for a short-term cash need, not to manage investments, track household spending, or replace a checking account.
There is already a meaningful distinction between a cash-advance service and a conventional personal loan. A traditional lender may be better suited to a larger planned expense, while a cash-advance app is built around urgency and a smaller gap between today and payday. That convenience can be valuable, but urgency also makes it easier to overlook conditions. I would therefore use the app as a comparison and application tool, not as permission to borrow automatically.
The app has attracted a 4.6 average from around 15 thousand ratings and more than 100 thousand installs. That level of adoption suggests that many Android users have found the service worth trying, but popularity should not be confused with suitability. Borrowing decisions remain personal, and a highly rated app can still be the wrong choice for someone who cannot comfortably repay the advance.
How I would use it during an ordinary cash shortage
Imagine that a utility payment is due a few days before payday and the household budget has no spare room. I would first write down the exact amount needed and the date when repayment would be realistic. Only then would I open the app and see whether the available option matches that need. This small step matters because a fast application can make an amount feel affordable simply because it is displayed immediately.
News Worth Your Time
Brain Test 2 Suits the Stop-and-Start Rhythm of Modern Phones
Google Play Games Makes Android Gaming Easier to Navigate, Not Easier to Love
WhatsApp Under Pressure: How Well It Recovers When Messages Fail
UNO!™ Beyond the Table: How Rivalry Keeps Players Coming Back
LinkedIn: Dominating the Professional Networking Arena
Unlocking the Full Potential of Pixel Art - Color by Number
Roblox: A Creative Revolution in Gaming
Why Gallery Stands Out in the Photo App World
How Pi Network is Revolutionizing Social Cryptocurrency
Google TV's Ecosystem Strategy: Redefining Streaming
How Little Panda: Princess Makeup Thrives with New OS Updates
Why Decor Life - Home Design Game Stands Out in Creative Simulation
I would read every screen before continuing, especially any explanation of repayment, eligibility, fees, authorization, or the handling of personal information. If the final amount owed is unclear, I would stop rather than guess. The best use of the app is a controlled request for a defined shortfall, not a vague search for “extra money.”
One practical advantage of a focused app is that it can keep the process in one place instead of requiring several unrelated searches. The trade-off is that the convenience may reduce the natural pause people get when speaking with a bank employee or comparing several written loan proposals. I would create that pause myself by taking a screenshot or note of the key terms before accepting anything, where the device and app permit it.
Trust starts with visible choices, not the rating
For this kind of product, trust depends on what I can verify while using it. I pay attention to whether the app explains why a piece of information is needed, whether the next step is optional or required, and whether I can review an application before submitting it. Clear labels are more useful than reassuring language because they show me what action I am actually taking.
I also look for a straightforward way to correct an entry. A typo in income, employment details, or a payment date could affect an application, so I would not rush through a form simply because the app is designed for speed. If there is a review screen, I would treat it as essential rather than decorative.
Another trust signal is the ability to leave without accidentally committing. I want a visible distinction between checking an offer and accepting it. If a button uses vague wording, I would read the surrounding text carefully and avoid tapping through on autopilot. The most important control is the one that lets me understand the commitment before I make it.
At the same time, I would not claim that a good interface guarantees a good financial outcome. An app can be easy to navigate while the underlying borrowing decision remains expensive or unsuitable. My confidence would come from understandable terms and deliberate user choices, not from the clean appearance of the screens or the number of ratings.
Information-sensitive moments deserve extra attention
A cash-advance application naturally involves sensitive financial and identity details. That is why I would slow down at every point where the app requests personal information, account-related information, or permission to access something on the phone. I would read the wording instead of assuming that every request is necessary for every user.
I would also install the app only from a trusted app marketplace and keep the operating system updated when possible. Since the app supports Android 6.0 and later, compatibility with an older phone does not remove the need for basic device security. A screen lock, current security updates, and avoiding public Wi-Fi during a financial application are sensible precautions.
My approach would be especially careful if the app moves me to another service or asks me to continue outside the main interface. I would check the name of the organization shown on each screen and make sure I understand who is receiving the information. A familiar-looking design is not enough reason to share details without reading.
There is also a privacy habit that many people skip: after finishing, I would review saved passwords, browser tabs, downloaded documents, and notification previews. A phone can expose financial information through lock-screen alerts or automatic autofill. These are not problems unique to PayDaySay, but they matter more when the task involves borrowing and personal finances.
What I would verify before accepting an advance
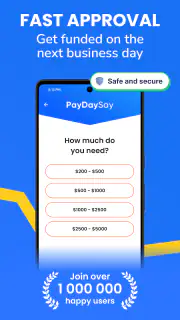
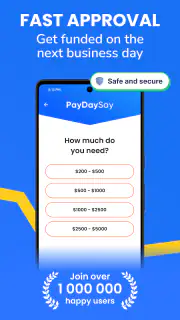
The phrase “instant” describes the intended convenience, not a guarantee that every person will receive money immediately. Eligibility, identity checks, account details, and the final offer can all affect the experience. I would avoid planning a bill payment around money that has not actually been approved and delivered.
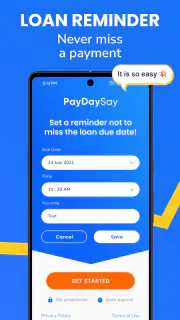
Before accepting, I would confirm the total repayment amount, the due date, any applicable fees, and what happens if the payment cannot be made on time. I would also check whether repayment is automatic or requires a manual action. These details are more important than the headline amount because they determine how the advance affects the next payday.
If the app presents several choices, I would compare the total cost rather than choosing the largest available amount. Borrowing only what is necessary reduces the chance that a short-term solution creates a larger shortage later. I would also keep a written record of the accepted terms, the expected repayment date, and any confirmation shown after submission.
A useful personal test is simple: after repayment, will I still be able to cover food, transport, housing, utilities, and other essentials? If the answer is no, the app is not solving the underlying problem. It is moving the pressure forward. In that situation, I would look for a payment extension, employer support, a local assistance program, or a cheaper borrowing option before accepting an advance.
Where the app fits beside ordinary alternatives
Compared with asking a bank for a conventional personal loan, a cash-advance app may feel more direct for a small, urgent need. A bank or credit union may be a better fit when I need a larger amount, a longer repayment period, or a relationship with a financial institution that can explain the terms in person. The extra formality can be inconvenient, but it may also encourage more careful comparison.
Compared with a credit card, an advance can be easier to separate from everyday spending, but the cost and repayment structure may work very differently. A credit card may offer a grace period for purchases, while a cash advance from any source can create its own charges or deadlines. I would compare the total cost and timing, not assume that one product is automatically cheaper.
Compared with borrowing from a friend or family member, PayDaySay offers a more private and formal route, but it can create a financial obligation that still arrives on a fixed schedule. Personal borrowing may avoid some formal application steps, yet it can strain relationships. Neither option is universally better; the right choice depends on cost, privacy, reliability, and the ability to repay.
Compared with payday lenders reached through a web search, a mobile app may feel more convenient and easier to revisit. That convenience is also why I would resist applying to several services at once. Multiple applications can make it harder to track terms, repayment dates, and who has received my information. I would compare deliberately, then choose one path rather than treating every offer as available spending money.
Small controls that make a big difference
My first practical tip is to separate browsing from accepting. I would explore the available process without mentally counting the requested amount as money I already have. This protects against a common mistake: making a purchase or promising a payment before the advance is confirmed.
My second tip is to use a dedicated note for the transaction. I would record the requested amount, the final amount borrowed, the repayment date, the total due, and any support contact shown in the app. This is more reliable than trusting memory, especially when several bills are due around the same time.
My third tip is to plan the repayment on the same day as the application. If the money is intended to bridge a gap until payday, I would identify the exact income that will cover it and remove the repayment amount from my future budget immediately. If that leaves no room for essentials, I would treat that as a warning to decline.
I would also avoid sharing an account with another person while completing a financial application. Using a personal device and a private connection makes it easier to review what is being entered and reduces the chance of someone else seeing notifications or confirmation screens. Afterward, I would check the app’s settings and the phone’s permission manager so I understand the choices currently enabled.
Who should consider it, and who should skip it
I can see Cash Advance Now - PayDaySay being useful for an Android user with a specific, short-lived cash gap, a dependable upcoming payday, and enough room in the next budget to repay the advance. It may also suit someone who prefers handling an initial request digitally and wants a focused finance app rather than a broad banking platform.
I would skip it if I needed money for an ongoing expense, if my income date was uncertain, or if I was already relying on one advance to repay another. It is also not the right tool for long-term debt consolidation, building savings, or solving a recurring income shortfall. In those cases, a nonprofit adviser, credit union, employer resource, or structured repayment plan may be more appropriate.
People who are uncomfortable entering sensitive information on a phone should not feel pressured to use it simply because it is convenient. A traditional institution with face-to-face assistance may be a better choice if personal explanation and direct support are priorities. Likewise, anyone who cannot identify the total repayment cost should pause and seek clarification before proceeding.
My cautious verdict after weighing convenience and control
Cash Advance Now - PayDaySay is best understood as a focused doorway to a short-term borrowing option, not as free money and not as a substitute for financial planning. Its free availability, broad age rating, older Android compatibility, and strong user rating make it approachable, while the developer PayDaySay gives the product a clear identity rather than making it feel like an anonymous tool.
Still, the responsible experience depends heavily on the user. I would judge the app by the clarity of each request, the visibility of the final terms, the ability to review or cancel before commitment, and the control I have over my information. I would never let the promise of speed replace checking the repayment amount and date.
My recommendation is therefore conditional: try it only for a defined, genuinely temporary need, and treat every screen as a financial decision rather than a routine sign-up. If the terms are clear and the repayment fits comfortably into the next budget, it may be a useful option to investigate. If the cost is unclear, the information requests feel excessive, or repayment would create another crisis, I would choose a slower and more transparent alternative instead.
In short, Cash Advance Now - PayDaySay can be practical when used with restraint. I would keep the borrowing amount as small as possible, preserve a record of the agreement, review account and permission controls, and remember that the app’s convenience is valuable only when it leaves me in a stronger position after payday.
Pros
- Simple application process with minimal paperwork
- Clear repayment schedule helps users plan their budget
- Useful for covering unexpected short-term expenses
- Accessible to users with limited traditional credit history
- Online service avoids visiting a physical lender
Cons
- Interest and fees may make borrowing expensive
- Short repayment periods can create financial pressure
- Approval and loan terms vary by applicant
- Late payments may lead to additional charges
- Availability and terms depend on your location
FAQ's for Cash Advance Now - PayDaySay
What is Cash Advance Now - PayDaySay?
Cash Advance Now - PayDaySay is a financial service app designed to connect users with potential lenders or cash advance providers. After submitting personal and financial information, the app may display available loan offers based on eligibility. It is important to understand that PayDaySay may act as a lending service or connection platform, and approval, loan amounts, rates, fees, and repayment terms can vary by applicant and provider.
Can I get an instant cash advance through PayDaySay?
The app may provide a quick application process and users can often receive a decision shortly after submitting their details, but approval and funding are not guaranteed. Processing times depend on the lender, your bank, the information provided, and when the application is completed. Some requests may be reviewed manually, so “instant” should be understood as fast processing rather than guaranteed immediate money.
How much does a PayDaySay loan cost?
The total cost depends on the lender and the terms offered to you. Before accepting anything, carefully review the annual percentage rate, interest, origination or service fees, late-payment charges, repayment schedule, and the final amount you will repay. Short-term advances can be expensive, particularly when fees are high or repayment is extended, so compare the offer with other borrowing options.
What information is required to apply?
Applicants may be asked for identifying information, contact details, employment or income information, banking details, and permission to verify financial data. Providing accurate information is essential because incorrect details can delay processing or affect eligibility. Since financial information is sensitive, review the app’s privacy policy, data-sharing practices, permissions, and security information before submitting an application.
Is Cash Advance Now - PayDaySay safe and available to everyone?
The app may use security measures to handle submitted information, but no online service should be treated as completely risk-free. Availability, eligibility, minimum income requirements, state restrictions, and lender participation can differ. Download the app only from an official store, verify the company and lender disclosures, avoid paying unexpected upfront fees, and never accept terms you do not fully understand.