
Cash Advance: Get 250 Fast
Android OnlyFree·User Rating
 Analysis by ViaAPK
When I look at a finance app such as Cash Advance: Get 250 Fast, I do not judge it only by how quickly it presents a borrowing option. I also ask whether the experience is understandable when someone is stressed, using a smaller phone, dealing with limited dexterity, or trying to complete a task in a noisy or distracting place. That broader test matters here because a payday loan or cash advance decision can affect a person’s budget well beyond the moment of application.
This is a free finance app from KOMPANIIA LORENS PP, aimed at people looking for a cash advance through a simple mobile process. It is rated for Everyone, has reached over 100 thousand installs, and holds a 4.7 average from around 25 thousand ratings. Those figures suggest that the basic experience is approachable for many users, but they should not be mistaken for a guarantee that the borrowing option suits every financial situation.
How the app feels to read and navigate
I focus here on how the app’s narrow, cash-advance purpose affects the reading experience, especially when someone is reviewing a financial choice under pressure. I also consider practical ways to make that review less error-prone, before turning to the situations where this focused approach is useful—and where a broader tool may serve better.
A straightforward starting point
My first impression is that the app’s appeal comes from reducing the number of decisions presented at once. Rather than feeling like a full banking dashboard packed with accounts, charts, transfers, and investment tools, it focuses on the cash-advance journey. That narrow purpose can help someone who wants to understand the next step without learning an entire financial platform.
For readers who find dense finance interfaces tiring, this is an important strength. A focused screen is easier to scan than a traditional banking app where a loan request competes with balances, card controls, notifications, and promotional panels. I would still slow down before accepting anything, but the limited scope makes it easier to keep attention on the immediate task.
The wording also matters. A cash advance is not the same as ordinary spending money, and the most useful part of the experience should be the information that explains what the user is agreeing to. I recommend reading every amount, repayment detail, and condition shown in the process instead of treating a short path as permission to move quickly. Simple navigation is helpful only when it is matched by careful reading.
What I would check before moving forward
I would use the app when I already knew why I needed the money and how I expected to repay it. That preparation makes the interface easier to use because I am not trying to solve a financial problem and interpret a borrowing offer at the same time. Before opening the application, I would write down the amount needed, the date income is expected, and the bills that must remain covered.
News Worth Your Time
Brain Test 2 Suits the Stop-and-Start Rhythm of Modern Phones
Google Play Games Makes Android Gaming Easier to Navigate, Not Easier to Love
WhatsApp Under Pressure: How Well It Recovers When Messages Fail
UNO!™ Beyond the Table: How Rivalry Keeps Players Coming Back
LinkedIn: Dominating the Professional Networking Arena
Unlocking the Full Potential of Pixel Art - Color by Number
Roblox: A Creative Revolution in Gaming
Why Gallery Stands Out in the Photo App World
How Pi Network is Revolutionizing Social Cryptocurrency
Google TV's Ecosystem Strategy: Redefining Streaming
How Little Panda: Princess Makeup Thrives with New OS Updates
Why Decor Life - Home Design Game Stands Out in Creative Simulation
This small workflow is more useful than relying on the app alone. It gives me a reference point when reviewing the offer and reduces the chance of treating the maximum available amount as the amount I should take. The name suggests a fast advance, but speed should not replace a personal affordability check.
The app is currently listed as version 1.2.2 and supports Android 7.0 or later. That broad operating-system range makes it relevant to people who keep an older Android phone rather than upgrading regularly. At the same time, an older device may have a smaller display, slower response, or less comfortable touch interaction, so I would pay extra attention to whether text and controls remain easy to distinguish on the particular phone being used.
Useful reading habits for a borrowing app
I would not rely on color alone to understand an important status or button. If a screen uses visual emphasis to separate the next step from supporting information, I would also read the labels carefully. This is especially important for users with reduced color perception or anyone viewing the screen under bright sunlight, where subtle differences can disappear.
Another practical habit is to pause after each screen rather than tapping through automatically. In a shopping app, an accidental tap may be harmless. In a finance app, the same habit can lead to overlooking a condition or confirming something before it has been understood. I found the focused design more comfortable when treated as a sequence of review points, not as a race to completion.
Motor and sensory considerations during use
People with limited finger movement, hand tremors, or difficulty making precise taps may find any mobile borrowing process demanding. A focused interface can reduce visual clutter, but it does not automatically solve touch-target problems. I would use the largest comfortable display available, hold the phone securely, and avoid completing an application while walking or carrying something else.
Voice input or system-level magnification may help some Android users, depending on the phone and settings, but I would not assume that every part of the app responds perfectly to those tools. The safest approach is to test the early screens without entering sensitive information, then decide whether the text, controls, and transitions are manageable.
For people with low vision, the most important question is whether the full financial explanation can be read without rushing. Increasing system text size can improve comfort, but enlarged text may also change how much content fits on a screen. That creates a trade-off: larger lettering may be easier to see while requiring more scrolling and more deliberate checking that no important section has been skipped.
Users with hearing loss are less likely to depend on sound for a basic finance workflow, but anyone with sensory sensitivities may still prefer a quiet, controlled setting. Notifications, interruptions, and bright surroundings can make it harder to compare numbers accurately. I would silence distractions, use adequate lighting, and review the final information once more before submitting anything.
For users who rely on a screen reader, the practical experience may depend on how the app exposes headings, buttons, fields, and changing messages to Android’s accessibility services. I would not assume that a popular rating means full compatibility with every assistive technology. A good personal test is to move through the opening screens using the preferred accessibility setup and confirm that each action has a clear spoken label before continuing.
Situational access: when the focused design helps
A realistic use case is a person who notices an essential household bill is due before the next paycheck. They may be away from their computer, using an older Android handset, and need to review a possible short-term option from a quiet corner at work or while traveling. The app’s mobile-first focus is convenient in that situation because it does not require learning a broad banking system first.
That convenience has limits. I would not begin the process in a crowded bus, on a weak connection, or while distracted by children or work messages. A rushed environment makes it easier to miss a term, enter information incorrectly, or misunderstand the difference between receiving money and being able to repay it comfortably. The app may be available at the moment of need, but the decision still deserves a calm setting.
It can also be useful for someone who prefers a phone over a desktop website. A mobile screen keeps the task close at hand, and the app’s narrow purpose may feel less intimidating than navigating a lender’s larger web presence. For a person who already manages finances through a smartphone, that consistency can lower the practical barrier to starting an application.
On the other hand, someone who needs to compare several borrowing choices may be better served by a browser, spreadsheet, or established banking application. Those alternatives are often more suitable for placing repayment amounts, fees, dates, and other conditions side by side. I would use this app to examine one option, not as my only research tool when the decision is financially significant.
How it compares with familiar alternatives
Compared with a conventional bank app, this product is more specialized. A bank application usually combines everyday money management with lending, which can be useful when I want to see how a repayment fits into my existing balance and scheduled payments. The trade-off is a busier interface and potentially more navigation before reaching the relevant service.
Compared with a lender’s website, a dedicated app can feel more convenient for repeat mobile users. The phone format is designed for quick access, while a website may be easier for people who need a larger screen, browser zoom, or several windows open for comparison. Neither format removes the need to inspect the terms carefully; they simply support different working styles.
Compared with asking a bank, credit union, or trusted financial counselor, an app is less personal. A human adviser may be able to discuss alternatives and help identify whether a cash advance is sensible in a particular budget. The app is therefore strongest when I already understand my circumstances and need a direct way to review a short-term option. It is weaker when I am unsure whether borrowing is the right answer at all.
Remaining barriers that affect inclusive use
The biggest barrier is not necessarily the number of taps. It is the financial pressure surrounding the task. A person facing an urgent expense may focus on getting money quickly and give less attention to repayment obligations. The app’s simple path can feel reassuring, but that same simplicity may encourage premature confidence if the user does not stop to examine the complete offer.
Language and financial vocabulary can create another barrier. Someone who is comfortable with everyday English may still struggle with terms connected to advances, repayment timing, or eligibility. I would keep a notes app or paper nearby and rewrite each important condition in plain language before agreeing. If I cannot explain the total obligation to myself, I would not continue.
Privacy is also part of accessibility. A user may need to complete the process in a shared home, public place, or workplace where other people can see the screen. I would avoid displaying sensitive details openly, use the phone’s privacy settings, and postpone the application if I could not review it discreetly. Convenience is not worth exposing personal financial information to bystanders.
Older hardware can introduce friction beyond screen size. A slower phone may make transitions feel less immediate, and a user with motor difficulties may interpret a delayed response as a failed tap and press again. I would wait for each screen to finish loading before repeating an action. That small adjustment can prevent duplicate inputs and reduce anxiety during a sensitive process.
The app is free to install, which removes an upfront download cost, but that should not be confused with borrowing being cost-free. The relevant question is what the complete advance requires the user to repay and whether that obligation fits the budget. I would treat the free app as access to a financial service, not as free money.
Who should use it, and who should choose another route
I can see this app working well for an Android user who wants a focused cash-advance application, prefers mobile steps, and can review financial details independently. It is also a reasonable fit for someone using an older supported phone, provided the display and touch controls remain comfortable. The Everyone age rating makes the app broadly approachable, but age suitability does not replace adult judgment about borrowing.
I would suggest a different route for anyone who needs long-term debt support, detailed budgeting, or help comparing multiple forms of credit. A bank, credit union, nonprofit adviser, or full budgeting tool may provide better context. I would also avoid depending on this app when the repayment plan is uncertain, when existing debts already consume the available income, or when the advance would simply postpone the same shortfall to the next pay period.
People who need strong assistive-technology compatibility should test the interface with their own settings before entering personal details. The app may be usable, but accessibility cannot be inferred from a high rating or a simple layout. A short trial of navigation, text scaling, and touch accuracy is more reliable than assuming the experience will match another finance app.
My inclusive verdict
After looking at it as both a finance tool and a mobile experience, I think Cash Advance: Get 250 Fast is most appealing because it keeps its purpose narrow. The free download, support for older Android versions, and focused workflow can make a short-term cash-advance option easier to reach than a crowded banking platform. Its strong user response, with a 4.7 average and around 25 thousand ratings, reinforces that many people find the basic experience accessible enough for their needs.
Still, I would recommend it with a clear condition: use the simplicity to organize your review, not to skip it. Read every financial detail, compare the obligation with your real income, and choose a quiet moment where you can see and understand the screen. If you need broader financial guidance, enlarged-screen comparison, or personal support, another option may be more inclusive for your circumstances.
My final view is cautiously positive. The app can remove practical friction for a user who already knows what they are considering, and its current version gives Android users on older systems a chance to access the service. But the most important accessibility feature is the user’s ability to make an informed decision. If the repayment terms are not completely clear, the right next step is to pause rather than borrow faster.
Pros
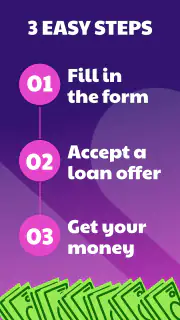
- Simple application process with minimal information required.
- Fast eligibility checks can save time in urgent situations.
- Loan details are presented before accepting an offer.
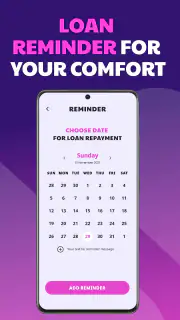
- Useful repayment reminders help users track upcoming due dates.
- Available on mobile
- making it convenient to apply anywhere.
Cons
- Fees and borrowing costs may be high compared with traditional loans.
- Approval and advance amounts can vary based on personal eligibility.
- Repayment deadlines may be short and difficult for some users.
- Late payments could lead to additional charges or financial stress.
- Availability and terms may differ depending on your location.
FAQ's for Cash Advance: Get 250 Fast
What is Cash Advance: Get 250 Fast and how does it work?
Cash Advance: Get 250 Fast is a financial app designed to help eligible users request a small cash advance through their mobile device. After creating an account, you may be asked to provide personal, employment, income, and banking information so the service can assess eligibility. Approval, advance amounts, fees, and repayment terms are not guaranteed and can vary by applicant and location.
Can everyone get a $250 cash advance through the app?
No. The advertised amount should not be understood as an automatic guarantee. Eligibility may depend on factors such as your age, residence, income, employment status, bank account activity, identity verification, and other requirements established by the provider or its lending partners. Before accepting an offer, carefully review the amount you will receive, applicable fees, repayment date, and any additional conditions.
How quickly will the money arrive after approval?
The app promotes fast access to funds, but delivery time can depend on approval, verification, banking hours, weekends, holidays, and the transfer method selected. Some users may receive funds quickly, while others may experience delays or require additional documentation. Any instant-transfer option may also involve an extra charge, so check the final cost before confirming the request.
Are there fees or repayment requirements I should know about?
Potential costs may include service charges, subscription fees, expedited-transfer fees, interest, or other expenses depending on the offer and the provider’s terms. Repayment is generally scheduled for a specific date, and missing it could lead to additional charges, collection activity, or negative consequences for your finances. Read the agreement in full and confirm the total repayment amount before proceeding.
Is Cash Advance: Get 250 Fast safe to use with my personal and banking information?
As with any financial application, users should review the privacy policy, permissions, developer identity, customer support details, and data-sharing practices before submitting sensitive information. Download the app only from an official store, avoid entering credentials through suspicious links, and use a secure connection. Never provide more information than necessary, and contact support if you notice unauthorized activity or unclear charges.