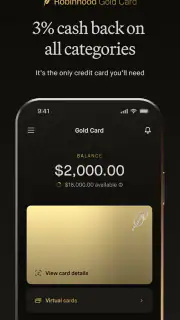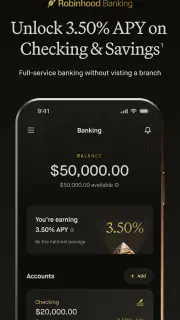

Robinhood Banking
Android OnlyFree·User Rating
 Analysis by ViaAPK
Managing money on a phone is convenient, but convenience only matters when the app remains understandable under pressure. I spent time looking at Robinhood Banking as a finance app from that angle: how easily I could find important areas, how much effort common tasks demanded, and how well the experience might suit people using different devices, abilities, or everyday routines. Developed by Robinhood, it presents itself as a banking-focused product rather than a general-purpose budgeting lesson, so the quality of its navigation and the clarity of its financial information matter more than flashy presentation.
The app is free and aimed at Everyone, which makes its broad audience easy to understand. It was released on Mar 19, 2024, and the current version is 2.18.7, with Android support beginning at 7.0. Its store summary is “Credit Card & Banking,” while the shorter description calls it “Robinhood Banking.” Those labels set a fairly direct expectation: this is for people who want banking tools in a mobile environment, not for someone looking for a full financial education course or a replacement for every specialist service.
My overall impression is positive, with an important qualification: the app is most useful when you already know what banking action you want to take. It can feel approachable for routine money management, but anyone who needs extensive guidance, highly customized presentation, or a traditional branch-style experience should examine the fit carefully before making it their only banking option.
How clearly the app communicates and guides you
I approach app guidance as more than a tidy screen: it should help me understand what I’m looking at before I act. In this section, I’ll consider how clear wording and a measured routine can make everyday checks easier, while noting where a user may still need to slow down and interpret financial details for themselves.
Readability and navigation in everyday use
The strongest part of a mobile banking experience is not a clever feature; it is knowing where to look when you need an answer. With Robinhood Banking, I found the banking-first framing helpful because it keeps the main purpose visible. Instead of approaching it as a broad financial dashboard full of unrelated tools, I would open it with a specific question in mind: What is my available balance? What happened to a recent transaction? Which banking area should I check next?
That approach also reveals a limitation. New users can understand the general purpose quickly, but understanding the consequences of a financial action still requires care. A clean interface can make a task look simple without making every term simple. I would not rush through prompts involving transfers, card activity, account movement, or any other action that changes where money sits. The app is easier to use when I pause to read the full screen rather than treating each step as a button hunt.
For readers who rely on larger text, high contrast, screen magnification, or other device-level adjustments, the practical test is whether the layout remains usable after those changes. I would set up the phone before judging the app: increase text size gradually, check whether labels remain visible, and confirm that important information is not lost behind cramped spacing or truncated wording. A banking app should be tested with the display settings you actually use, not with the phone left in its default state.
News Worth Your Time
Brain Test 2 Suits the Stop-and-Start Rhythm of Modern Phones
Google Play Games Makes Android Gaming Easier to Navigate, Not Easier to Love
WhatsApp Under Pressure: How Well It Recovers When Messages Fail
UNO!™ Beyond the Table: How Rivalry Keeps Players Coming Back
LinkedIn: Dominating the Professional Networking Arena
Unlocking the Full Potential of Pixel Art - Color by Number
Roblox: A Creative Revolution in Gaming
Why Gallery Stands Out in the Photo App World
How Pi Network is Revolutionizing Social Cryptocurrency
Google TV's Ecosystem Strategy: Redefining Streaming
How Little Panda: Princess Makeup Thrives with New OS Updates
Why Decor Life - Home Design Game Stands Out in Creative Simulation
One useful habit is to separate checking from acting. I would first open the relevant banking view, review the balance or activity, and only then begin a transfer or other financial task. This two-step routine reduces the chance of confusing a pending item with money that is ready to use. It also gives users who process information more slowly a calmer workflow instead of forcing them to make a decision while scanning several pieces of information at once.
Making financial information easier to understand
Robinhood Banking benefits from plain, familiar banking language, but familiarity is not the same as universal clarity. Terms that feel obvious to experienced account holders may still be unclear to someone opening a first account, learning English, or managing money after a long break. I recommend reading labels in context and checking the surrounding explanation before confirming anything that affects funds.
The app is a better match for people who prefer short, focused interactions than for users who want a guided tutorial at every stage. I could imagine a newcomer being comfortable with checking routine activity while still wanting outside help before making a more consequential decision. That is not a flaw unique to this product; it is a reminder that a concise banking interface cannot replace financial understanding.
Visual simplicity can help users with attention-related difficulties because fewer competing elements make it easier to focus on the immediate task. At the same time, a minimalist presentation can hide the difference between similar actions if the wording is not read carefully. My advice is to avoid tapping from memory. Read the action, read the destination, and review the final confirmation. That small pause is especially valuable when multitasking.
Motor and sensory considerations
Mobile banking places a lot of responsibility on touch interaction. Users with tremors, limited dexterity, joint pain, or difficulty performing precise gestures may find any finance app tiring if controls are small or closely grouped. I would use the app with the phone held securely, avoid completing sensitive actions while walking, and take advantage of the operating system’s touch and display settings where they help. Those adjustments are not a substitute for accessible design, but they can make routine navigation less demanding.
Voice control and screen-reading tools can also change the experience substantially. I would test whether the phone identifies each control in a meaningful order and whether status information is announced clearly. Financial screens often combine headings, amounts, dates, and action buttons, so the order in which assistive technology encounters them matters. If a user cannot confidently tell which amount belongs to which transaction, the app should not be treated as ready for independent use in that workflow.
For sensory sensitivity, the most important question is whether the app lets you complete a task without unnecessary urgency. Banking should not encourage impulsive tapping. I prefer to use it in a quiet setting, with notifications reviewed later rather than acted on immediately. Users who are sensitive to visual density or frequent alerts may want to keep the app for deliberate account checks instead of allowing every phone interruption to dictate their attention.
A realistic example is a commuter who notices a card transaction while standing on a crowded train. The best response is not to investigate deeply while balancing a bag and navigating noise. I would note the alert, wait until I can sit down, and then open the transaction details with both hands free. That workflow is safer for users with motor limitations and sensible for anyone handling financial information in public.
Using the app across different situations
The same banking task can feel different at home, at work, or while travelling, so I’ll look at how context affects comfort and confidence. I’ll also consider when a phone-based workflow is a sensible fit and when another way of managing money may be more practical.
Situational access at home, work, and on the move
Accessibility is not only about permanent disability. A person may have one free hand while carrying groceries, poor lighting during a power interruption, temporary eye strain, or limited concentration after a long workday. Robinhood Banking makes the most sense when used as a deliberate tool rather than something to operate hurriedly in every environment.
At home, I would use a larger display setting if needed, keep the phone at a comfortable viewing distance, and complete account checks when interruptions are limited. At work, privacy becomes part of accessibility: someone may be able to read the screen but not safely discuss or display financial details around colleagues. In public, glare, noise, unstable connectivity, and shoulder-surfing risks can make a seemingly easy task much harder.
The app is particularly suitable for a person who wants to check banking activity during a short, planned session. It is less suitable for someone whose daily routine requires complex financial administration in changing environments. If you need to coordinate several accounts, reconcile detailed records, or work with a keyboard and large monitor, a desktop banking site or dedicated finance software may be more comfortable than a phone-centered workflow.
Another practical use case is helping a family member review routine banking activity. I would not simply hand over the phone and assume the interface will be self-explanatory. Instead, I would let the person control the device, explain unfamiliar terms without taking over, and agree on which actions they are comfortable performing independently. This preserves dignity and reduces the risk of a helper making an unintended financial decision.
Who will feel at home with Robinhood Banking?
I think the app suits people who want a straightforward mobile entry point for banking and who are comfortable checking details before confirming actions. It may also appeal to existing Robinhood users who prefer keeping their financial activity within a familiar ecosystem, although I would still judge it on the banking tasks I personally need rather than on brand familiarity.
The product has visible traction in its category, with a 4.9 average from around 25 thousand ratings and roughly 2.3 thousand written reviews. It has also passed the 100 thousand install mark. Those figures suggest that many people find the experience worthwhile, but they cannot predict whether the app will work well with your particular reading settings, assistive technology, or banking habits. A high average is encouraging; it is not a substitute for testing the workflows that matter to you.
The Everyone age rating makes the app approachable in terms of audience classification, but financial responsibility still varies widely by age and experience. A younger or inexperienced user may need a trusted adult or financial educator to explain what an action means. The rating should not be mistaken for a promise that every banking concept will be easy for every person.
Where another option may be better
A conventional bank app may be preferable if you already depend on a broad set of established banking services, branch support, or a familiar accessibility workflow. A budgeting app may be better if your main goal is categorizing expenses and seeing long-term spending patterns. A desktop service may win for users who need a physical keyboard, a wide screen, or simultaneous views of several records.
That comparison does not make Robinhood Banking weak. It clarifies its role. I would choose it for convenient mobile banking access, not because one app should replace a budget planner, a tax tool, a spreadsheet, and a human support channel. People with complex financial arrangements should be especially cautious about consolidating everything into a single mobile experience.
Remaining barriers and friction
The largest remaining barrier is the gap between visual simplicity and financial complexity. A user may reach the right screen quickly but still need more context to interpret what they see. This affects people with limited financial literacy, cognitive disabilities, language barriers, or simply little time. I would treat every confirmation screen as a decision point, not as a formality.
Another concern is dependence on the phone itself. If the device is unavailable, damaged, low on battery, difficult to see, or being shared with someone else, mobile access becomes inconvenient or impossible. That matters for users who rely on alternative devices or who cannot comfortably perform precise touch actions. Before moving important banking activity into the app, I would make sure I have a practical backup plan for account access and support.
Privacy can also become an accessibility issue. A person who needs screen magnification may have to hold the phone closer or enlarge information, making it more visible to people nearby. Someone using spoken output may not be able to review financial details privately in a public place. I recommend checking sensitive information in a controlled setting and avoiding account actions on shared or unsecured devices.
Version awareness matters as well. The current version is 2.18.7, and updates can change labels, layouts, or the way a device interacts with the app. I would recheck the most important workflow after an update instead of assuming that a familiar sequence remains identical. This is especially important for users who depend on a carefully configured screen reader, magnification setting, or alternative input method.
Three habits that make the experience more inclusive
- Use a confirmation pause: read the account, amount, recipient, and timing before approving a transaction, even when the screen looks familiar.
- Test with your real device settings: try the app using the text size, contrast, zoom, voice control, or screen reader setup you depend on every day.
- Separate alerts from decisions: treat a notification as a prompt to review, not an instruction to act immediately in a noisy, rushed, or public situation.
These habits are simple, but they address problems that a store summary cannot show. They also help users who do not identify as disabled but experience temporary fatigue, distraction, poor lighting, or limited privacy. In my view, inclusive use often comes from combining the app with a deliberate personal routine.
My inclusive verdict
Robinhood Banking is a credible choice for people who want free mobile banking access and prefer a focused, phone-based routine. I like that its purpose is easy to grasp, and I can see why the product has attracted a strong response from users. The developer, Robinhood, has positioned it clearly enough that a reader can understand the basic direction without wading through a long explanation.
Still, I would not recommend choosing it solely because it is free, highly rated, or marked for Everyone. The right question is whether you can comfortably read its financial information, operate its controls, and verify important actions with your own accessibility setup. If you need extensive guidance, complex account management, a large-screen workflow, or dependable human assistance, a traditional bank or another specialized tool may serve you better.
For me, the best use is controlled and intentional: open the app when I have privacy, enough time to read, and a clear banking task. Used that way, it can reduce friction without encouraging careless decisions. Robinhood Banking is worth trying for accessible-minded mobile banking, provided you test it with your real needs rather than assuming a polished interface works equally well for everyone.
Pros
- Commission-free stock
- ETF
- and options trading
- Clean interface makes investing easy for beginners
- Supports recurring investments and fractional shares
- Real-time market data and customizable watchlists
- Offers cash management features and a debit card
Cons
- Limited customer support options compared with traditional banks
- Investment choices are narrower than at many full-service brokers
- Options and margin trading can expose beginners to high risk
- Cash sweep and interest rates may change over time
- Availability and features vary by location and account eligibility
FAQ's for Robinhood Banking
What is Robinhood Banking, and what services does it offer?
Robinhood Banking refers to the banking features available through the Robinhood financial app, including spending, cash management, direct deposit, bill payments, and access to eligible savings or cash-sweep programs. It is designed to work alongside Robinhood’s investing tools, allowing users to manage cash and investments from one account. Available features can vary by country, account type, eligibility, and current Robinhood policies.
Is Robinhood Banking a real bank, and is my money protected?
Robinhood is primarily a financial services and investing platform rather than a traditional bank. Depending on the product, customer funds may be held through partner banks or placed in eligible programs that provide applicable protections. Coverage, limits, and terms can differ between products and locations, so users should carefully review the current account agreement, disclosures, and protection details before depositing significant amounts of money.
Can I use Robinhood Banking for direct deposit, debit card purchases, and bills?
Eligible Robinhood customers may be able to receive paychecks or government payments through direct deposit, use a Robinhood-issued debit card for everyday purchases, and pay bills from available cash. In my review, these features were convenient when enabled, but availability and processing times depend on account verification, payment networks, employer or biller support, and Robinhood’s current eligibility requirements. Always confirm limits before relying on the account for essential payments.
Are there fees for using Robinhood Banking?
Robinhood Banking may offer several services without monthly maintenance fees, but that does not mean every transaction is free. Users should check for possible charges involving out-of-network ATM withdrawals, expedited transfers, card replacement, international usage, returned payments, or other optional services. The app displays relevant information, but fee schedules and terms can change, so reviewing the latest disclosures before signing up is strongly recommended.
What information and verification are required to open a Robinhood Banking account?
To use Robinhood’s banking or cash-management features, applicants generally need to provide personal information such as their legal name, address, date of birth, tax identification details, and government-issued identification. Robinhood may also request additional documents or information to comply with identity-verification and financial regulations. Approval is not guaranteed, and access may be restricted by age, residency, account status, or other eligibility conditions.