Schwab Mobile
Android OnlyFree· User Rating
I approached Schwab Mobile as a practical finance app rather than a simple market-watching tool. Its purpose is to bring investing, research, trading, and banking tasks into one mobile experience, which can be convenient when I want to check an account and act without moving between several services. At the same time, an app that puts serious money decisions in my pocket needs to be judged by more than its feature list. The important questions are whether it fits my habits, whether its mobile workflow feels comfortable, and whether its free access delivers enough value for the way I manage money.
The app comes from The Charles Schwab Corporation and has been available since May 25, 2011. It is a free finance app for Everyone, with more than five million installs and an average rating of 3.1 from roughly twenty-nine thousand ratings. Those figures suggest a widely used product with a mixed user experience. I would not treat the rating alone as a verdict, but I would take it as a reason to pay attention to friction, especially if I expect a smooth, effortless experience for every financial task.
How Schwab Mobile fits into everyday money management
Free access matters, but it is not the whole value question
The clearest cost advantage is straightforward: Schwab Mobile is free to download and use as an app. That makes it easy to try without paying an app purchase fee or committing money merely to access the mobile interface. For someone who already uses Schwab services, this free access can make the phone a useful extension of an existing financial relationship.
That point needs a careful distinction. Free app access is not the same as every financial activity being cost-free, nor does it promise that every investment product or transaction has identical terms. I would separate the price of the app from the costs and conditions attached to the accounts, investments, or trades I might use through it. The app itself does not require a purchase, but my financial decisions still deserve the same attention I would give them on a desktop site or through a representative.
This is also why I would avoid judging value by the word “free” alone. A no-cost app that helps me make a rushed or poorly understood decision is not automatically good value. Schwab Mobile is most useful when it reduces the time and effort involved in routine account work while leaving me enough information to make a deliberate choice.
One place for several financial jobs
The strongest idea behind the app is consolidation. Instead of using one application to look at investments, another to research securities, and a separate channel for banking, I can approach those activities from the same mobile environment. That does not mean I will perform every task from my phone, but it does reduce the need to remember which service handles which part of my financial life.
I find that especially useful for short sessions. I might open the app to review an account, inspect a research page, and then decide whether I need to do anything immediately. The value is not just speed; it is continuity. Seeing related financial information together can make it easier to connect a cash decision with an investment decision instead of treating them as unrelated chores.
There is a tradeoff in that all-in-one approach. A broad app can feel less focused than a specialist tool built around one activity. Someone who only wants a very simple spending overview may find the investing and trading emphasis unnecessary. Someone who wants advanced research may still prefer a larger screen. The convenience comes from coverage, not from making every part of finance equally deep or equally comfortable on a phone.
A realistic use case: a quick check before acting
Imagine I am away from my desk and remember that I need to review an investment account before making a personal budgeting decision. With Schwab Mobile, I can use the same app to inspect the relevant account information and research context, then decide whether the matter is urgent or can wait until I have more time. That is a sensible mobile workflow because it uses the phone for awareness and a measured next step, rather than treating a small screen as a replacement for careful planning.
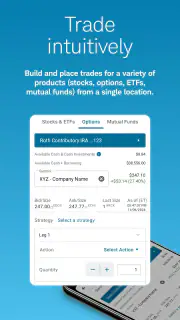
If I do decide to trade, I would slow down rather than rely on a quick tap. Mobile convenience can make an action feel smaller than it really is. I would verify the account, the security, the order details, and the final review screen before submitting anything. The app can make access easier, but it cannot remove investment risk or turn an uncertain decision into a safe one.
Research is more useful when I arrive with a question
The research side is most valuable to me when I use it to investigate a specific idea. For example, I might want to understand a company before deciding whether it belongs on a watchlist, or compare an investment with the broader goal I have in mind. Opening research pages without a question can quickly become passive scrolling, especially on a phone where information is presented in compact sections.
My practical tip is to decide what I need to learn before opening the research tools. Am I checking a holding I already own, exploring a possible purchase, or simply monitoring a market move? That small distinction helps me avoid confusing information volume with insight. The app can put research within reach, but the quality of the result still depends on how carefully I interpret it.
Banking and investing together can clarify priorities
Having banking and investment activity in one app can be helpful when I am deciding where available cash belongs. A quick account review may remind me that money intended for a near-term bill should not be treated like long-term investment capital. In that situation, the app’s value is not that it pushes me toward a trade; it helps me see the surrounding financial picture before I act.
This combined view can also expose a weakness in my own habits. If I tend to check market movements more often than my cash position, an all-in-one finance app may encourage a broader review. I would still keep a clear boundary between monitoring and acting. A convenient banking screen should support planning, not tempt me to move money impulsively just because the option is nearby.
Where the mobile format creates friction
Finance interfaces have a difficult balance to maintain. They need to expose enough detail for responsible decisions without making ordinary tasks feel like a professional trading terminal. On a phone, that balance is even harder because compact screens can turn comparisons, charts, and order details into a sequence of taps and scrolls.
My main reservation with Schwab Mobile is therefore not its overall purpose but the possibility of friction when a task becomes more involved. A quick balance check is naturally suited to mobile. A detailed investigation, multi-step comparison, or careful review of a complicated decision may be more comfortable on a desktop. I would use the app as a mobile companion, not assume it is always the best screen for every Schwab task.
The mixed average rating reinforces that caution. A 3.1 average across about twenty-nine thousand ratings indicates that many people use the app but that satisfaction is far from uniform. Ratings cannot tell me whether a problem is caused by a particular device, workflow, account situation, or expectation, so I would not turn that number into a precise technical diagnosis. I would read it as a reminder to test the app personally before making it central to my financial routine.
Who receives the most value
I see the best fit in an existing Schwab customer who wants convenient mobile access to investing, research, trading, and banking in one place. That person is likely to appreciate the reduction in app switching and the ability to handle short financial tasks while away from a computer. The free app access also lowers the barrier to trying the mobile workflow without adding a separate software purchase.
It can also suit a self-directed investor who is comfortable checking information, thinking through decisions, and accepting responsibility for the final action. The app gives that user a practical way to stay connected to accounts and research. The key is comfort with self-service. I would not choose it simply because the app makes trading accessible; I would choose it because I already have a clear process for deciding when not to trade.
A person who mainly wants basic banking may find the investment material more than necessary. Likewise, a frequent trader who depends on a highly specialized desktop setup may prefer a tool designed around a larger workspace and a narrower purpose. Schwab Mobile is also not the right answer for someone looking for financial guidance to replace their own judgment. Access to research is not the same as personalized advice.
Useful habits that improve the experience
I would begin by treating the app as a review tool before treating it as an action tool. On a normal day, I could check the relevant account information, note anything that needs attention, and close the app without placing an order. That habit separates observation from impulse and makes the mobile experience more useful for planning.
For research, I would keep a short written question beside me and record the conclusion in my own words. This prevents me from opening several pages and later forgetting why I looked at them. It is a simple workflow, but it turns the app from a stream of market information into part of a repeatable decision process.
Before any transaction, I would use the final review stage as a deliberate pause. I would check that I am in the intended account, confirm the action, and make sure the order reflects my plan rather than a momentary reaction. This is particularly important on a phone, where a fast interface can make a consequential step feel routine.
I would also keep desktop use in reserve for decisions that require side-by-side reading or extended concentration. That is not a failure of the mobile app; it is a sensible division of labor. The phone is excellent for access and timely checks, while a larger screen can be better for detailed review. Expecting one device to be ideal for every financial task is what creates unnecessary frustration.
How it compares with common alternatives
Compared with a banking-only app, Schwab Mobile offers a wider financial scope because it brings investment research and trading into the same general experience. That makes it more useful for someone whose money is divided between everyday banking and a portfolio. The compromise is that a banking-only app may feel simpler when all I want is a quick cash-related task.
Compared with a dedicated investing app, Schwab Mobile’s appeal is the connection between investing and banking rather than a single-minded focus on market activity. A specialist investing app may feel more streamlined for someone who only wants portfolio monitoring or trading tools. I would choose between them based on whether consolidation or specialization matters more in my routine.
Compared with a desktop brokerage website, the app wins on immediate access and loses some comfort whenever I need a broad, detailed workspace. I would not expect the phone version to replace every desktop habit. Its value is strongest when I need to check, research, or manage something while mobile, not when I am deliberately sitting down for a long financial review.
My final decision: useful access, not a reason to trade more
My view is that Schwab Mobile offers credible value because the app itself is free and brings several important financial activities together. Its strongest benefit is practical: I can approach investing, research, trading, and banking from one mobile location instead of dividing those tasks across unrelated tools. For the right Schwab customer, that convenience can justify keeping it installed.
I would skip it if I only need a minimal banking experience, dislike self-directed investing, or expect a phone app to provide the same working space as a full desktop setup. The mixed user rating also makes me recommend a personal trial rather than an automatic endorsement. I would test the tasks I actually perform, especially research and transaction review, before depending on it for everything.
For me, the sensible recommendation is to use Schwab Mobile as a controlled access point: check accounts, research with a clear purpose, handle suitable routine tasks, and reserve complex decisions for a calmer setting. The best value comes from convenience with discipline, not from making more financial moves simply because they are easy to reach. On that basis, I would recommend trying it to Schwab customers who want one free mobile finance app, while advising everyone else to compare its broad approach with a simpler banking tool or a more specialized investing alternative.
Pros
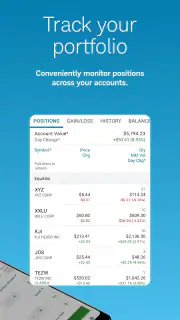
- Clear portfolio overview with balances
- holdings
- and performance data.
- Quick stock
- ETF
- and mutual fund order placement.
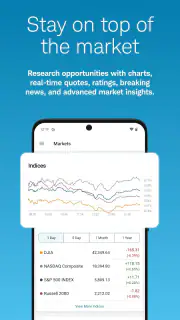
- Useful research tools
- quotes
- charts
- and market news.
- Secure login options
- including biometric authentication.
- Convenient mobile check deposit and account transfers.
Cons
- Some advanced trading features are easier to find on the website.
- Real-time data and certain quotes may require account eligibility.
- The interface can feel dense for first-time investors.
- Options trading may be unavailable until approval is granted.
- App performance can vary during periods of heavy market activity.
FAQ
What is Schwab Mobile, and what can I do with it?
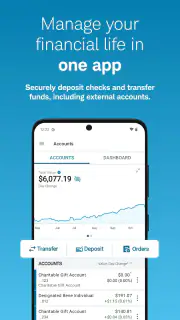
Schwab Mobile is Charles Schwab’s official mobile app for managing eligible brokerage, retirement, banking, and other Schwab accounts from an Android or iOS device. After signing in, you can review balances and positions, monitor market information, research investments, place trades, transfer money, deposit eligible checks, view statements, and contact Schwab support. Available features may vary depending on your account type, location, and Schwab services.
Is Schwab Mobile safe to use for banking and investing?
Schwab Mobile includes security features designed to protect account access and financial activity, such as encrypted connections, secure sign-in, device authentication, and optional biometric login where supported. You should still use the latest version of the app, avoid public or unsecured Wi-Fi when handling sensitive information, enable available security alerts, and never share your password or verification codes. No financial app can eliminate every security risk.
Can I buy and sell stocks through Schwab Mobile?
Yes, eligible Schwab brokerage customers can generally use the app to research securities, review quotes and charts, and submit orders for stocks, ETFs, mutual funds, options, and other investments supported by their account permissions. Before placing a trade, carefully check the symbol, order type, quantity, duration, and estimated costs. Market conditions, account restrictions, approval levels, and temporary service interruptions can affect order execution.
Does Schwab Mobile charge fees for using the app?
Downloading and using Schwab Mobile is generally free for Schwab customers, although normal mobile data charges from your carrier may apply. The app itself does not mean every transaction or investment service is free. Depending on what you trade or request, commissions, fund expenses, margin interest, wire fees, foreign transaction costs, or other account-related charges may apply. Always review Schwab’s current pricing information before proceeding.
Can I deposit checks and transfer money with Schwab Mobile?
The app may allow eligible users to deposit checks by photographing both sides of the check and to transfer money between linked Schwab accounts or external financial institutions. Availability, limits, processing times, and eligibility depend on your account and Schwab’s policies. Make sure the images are clear, retain the check until the deposit is confirmed, and verify recipient and transfer details because some transactions may not be reversible.