
Together Loans
Android OnlyFree·User Rating
 Analysis by ViaAPK
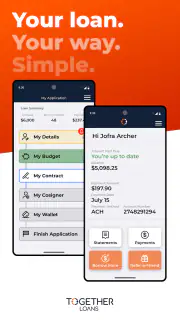
Managing a loan is rarely difficult because of one huge task. The friction usually comes from small questions: when a payment is due, where the current balance appears, whether a recent action went through, or how to contact the lender without searching through old messages. Together Loans is designed around that everyday problem. It is a free finance app from Transform Credit Inc that brings loan management into one mobile space, rather than making you rely on a browser, paperwork, or scattered account details.
I approached it as a first-time borrower would: install it, look for the information that matters most, and try to understand what a useful first session should accomplish. The experience makes the most sense when you already have a Together loan and want a convenient way to stay on top of it. It is not a general budgeting tool, a comparison service, or a replacement for broader personal-finance software. Its value is narrower, and that focus is also its main strength.
What to expect before you begin
The app sits in the finance category and is aimed at people who need to manage an existing loan. Its store summary describes an all-in-one place for Together Loans, which is a better way to understand its role than expecting a full banking dashboard. I would install it when my main goal was keeping loan information and related actions close at hand, not when I wanted to track groceries, investments, credit cards, or several lenders in one view.
It is free to install, and the age classification is Everyone. That makes the initial decision straightforward from a download perspective, although a free app does not change the financial obligations attached to a loan. I would still read every confirmation carefully and treat the app as a channel for managing borrowing, not as advice about whether borrowing is affordable.
The current release is version 9.1.2, and the app supports devices running Android 7.0 or later. In practical terms, that gives it a fairly broad compatibility range for Android users. The public response is encouraging without being overwhelming: it holds a 4.3 average from around six hundred ratings, with more than two hundred written reviews, and has passed one hundred thousand installs. I see that as useful reassurance that people are using it, but not as a reason to assume every account will behave identically.
One important expectation to set is that a loan-management app is only as helpful as the account information connected to it. If you are downloading it because you are considering a loan but do not have a relevant Together account, it may not offer the experience you are looking for. If you already have that relationship, the app’s focused design should feel more relevant than a generic financial tracker that cannot show lender-specific details.
The right reason to install it
My strongest reason for choosing Together Loans would be convenience between payment dates. A borrower may not need to open the app every day, but having a dedicated place to check the loan can prevent the familiar cycle of hunting for emails, logging into a general website, or wondering whether an action was recorded. That is especially useful if the loan is one of several monthly commitments and I want a quick, deliberate check rather than a vague memory.
News Worth Your Time
Brain Test 2 Suits the Stop-and-Start Rhythm of Modern Phones
Google Play Games Makes Android Gaming Easier to Navigate, Not Easier to Love
WhatsApp Under Pressure: How Well It Recovers When Messages Fail
UNO!™ Beyond the Table: How Rivalry Keeps Players Coming Back
LinkedIn: Dominating the Professional Networking Arena
Unlocking the Full Potential of Pixel Art - Color by Number
Roblox: A Creative Revolution in Gaming
Why Gallery Stands Out in the Photo App World
How Pi Network is Revolutionizing Social Cryptocurrency
Google TV's Ecosystem Strategy: Redefining Streaming
How Little Panda: Princess Makeup Thrives with New OS Updates
Why Decor Life - Home Design Game Stands Out in Creative Simulation
The app is less suitable for someone who wants to compare several borrowing options, build a complete debt-repayment plan, or see a combined picture of household finances. Those jobs call for a budgeting app, a spreadsheet, or a broader financial service. Together Loans should be judged on how well it reduces the effort of dealing with its specific loan relationship.
Setting up the first useful session
After installation, I would begin with the account details associated with the loan and keep any relevant agreement information nearby. This is a small but worthwhile preparation step: it avoids stopping halfway through because I cannot remember which details belong to the account. I would also use the official account information rather than guessing, particularly when a financial app asks me to identify or connect an existing loan.
The first setup should be approached as an orientation exercise, not a race. I would look for the main loan overview, identify where the balance or repayment information is presented, and find the path for taking action. The goal is to learn the app’s vocabulary and layout before I need it urgently. A few calm minutes now can make a meaningful difference when a payment question appears close to a deadline.
I would also check that the account shown is the one I expect before acting. This is an easy detail to overlook when a person has more than one borrowing product or has recently changed personal information. A quick review of the displayed details is a safer habit than assuming the first screen tells the whole story.
How I would reach the first successful action
For a new user, the first meaningful success is not simply opening the app. It is confirming that the correct loan is visible and completing one useful task with confidence. Depending on what is available for the account, that might mean reviewing the current loan information, checking repayment details, or managing the loan through the relevant in-app option. I would choose the least complicated action first, then verify the result rather than immediately moving through several screens.
A good personal workflow is to pause after each confirmation screen and note what changed. If I reviewed information, I would make sure it matches my records. If I carried out a loan-related action, I would look for a clear indication that it was accepted or recorded. I would not close the app simply because the screen changed; financial actions deserve a final check.
This is also where the app’s focused purpose becomes practical. Instead of opening a general finance app and searching through categories, I can start from the loan itself. That reduces the number of decisions between opening the app and finding the information I came for. For a first-time user, the best result is a repeatable routine: open the app, confirm the account, review the relevant detail, complete the action if needed, and check the outcome.
A realistic example would be a borrower who receives a reminder that a payment is approaching while commuting home. Rather than searching an inbox for the original agreement, I would open Together Loans, check the loan information, and use the available account-management route. Before leaving the session, I would confirm the displayed status and keep any important confirmation details. The app does not remove the responsibility to manage money, but it can make that responsibility easier to handle in the moment.
Small habits that make the app more useful
- Use it as a checkpoint, not a replacement for your own records. I would keep a simple note of important dates and amounts, then use the app to verify the current account view. That gives me a second reference without pretending that one screen is a complete financial plan.
- Separate checking from decision-making. I can use the app to understand the loan and manage the account, but I would decide whether an action fits my budget before tapping a confirmation button. Convenience should shorten the process, not rush it.
- Build a repeatable review routine. Checking after a payment or before a planned action is more useful than opening the app randomly. A consistent routine helps reveal whether the information I expect to see is appearing correctly.
These habits are more valuable than simply knowing where buttons are. They turn a lender-specific app into part of a responsible process. The app can centralize access to the loan, while I remain responsible for checking affordability, timing, and the effect on my wider budget.
Common points of confusion
The first likely confusion is assuming that “all in one place” means all personal finances. In this case, I would interpret it as the loan and its management, not a universal account hub. If I wanted a single screen combining rent, utilities, savings, credit cards, and borrowing, this would not be the right primary tool. Its narrow scope is intentional, so comparing it with a full budgeting app on the number of categories would be unfair.
Another possible misunderstanding is treating the app as a loan adviser. It can help me access and manage information connected with the loan, but it should not be used as a substitute for reading the agreement or assessing whether a new commitment is sensible. If I were unsure about an amount, a date, or the meaning of a loan term, I would verify it through the appropriate official support route rather than infer an answer from a general screen.
I would also avoid assuming that a completed tap always means the entire process is finished. With financial actions, there may be a confirmation step or a status that needs checking. My practical rule is simple: after doing anything important, look for the resulting account state and retain the confirmation information shown. If something appears inconsistent, stop and investigate instead of repeating the action.
People may also wonder whether the app is useful without constant use. In my view, it is better suited to occasional, purposeful sessions than continuous monitoring. A loan normally has specific moments when attention matters: reviewing the account, preparing for a repayment, checking a recent action, or resolving a question. Opening it only when there is a reason is not a weakness; it is consistent with the app’s focused job.
There is a further trade-off compared with managing a loan through a mobile browser. A dedicated app can be quicker to reach and easier to make part of a routine, while a browser may feel more convenient for someone who avoids installing finance apps. I would choose Together Loans when I expect to return to the same loan regularly and want a dedicated mobile route. I would choose the browser or direct support instead when I am using a shared device, troubleshooting an unusual account issue, or prefer not to keep lender apps installed.
Who should use it, and who should skip it?
I would recommend trying it to an existing Together borrower who wants a clearer mobile path to loan management. It is particularly sensible for someone who often loses track of account emails, prefers checking information on a phone, or wants to confirm loan details without opening a broader financial service. The free price also removes a common barrier to testing whether the workflow suits you.
I would skip it as my main finance app if I needed detailed spending analysis, multiple-provider debt tracking, savings goals, or a complete household budget. I would also be cautious about relying on it alone if I need extensive planning tools. A dedicated loan app can show the relevant account, but it cannot by itself tell me how that loan fits into every other monthly obligation.
That distinction matters because a focused app may feel simpler precisely because it leaves out unrelated areas. For a borrower who wants less clutter, that is a benefit. For someone expecting a full financial command center, it may feel limited after the first session. The right choice depends on whether the problem is “How do I manage this loan?” or “How do I manage all my money?”
What I would do after the first session
Once I had confirmed that the correct loan appeared and understood the main management path, I would make the app part of a small monthly routine. I would review the account at a sensible point before a repayment, check the result afterward, and avoid making repeated changes simply because the interface makes them easy to reach. That approach keeps the app useful without turning it into a source of unnecessary checking.
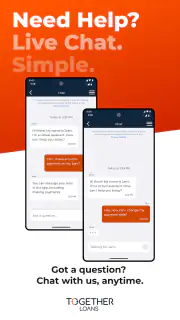
If I encountered a detail that did not match my own records, I would first compare the account information carefully and make sure I was looking at the intended loan. If the issue remained, I would use the appropriate official support channel connected with the lender rather than relying on guesswork or advice from unrelated finance apps. The app is most valuable when it gives me a reliable starting point for resolving a question.
I would also keep my expectations realistic about what an update can change. Version 9.1.2 is the current release, but an updated interface does not remove the need to review confirmations or understand the loan agreement. Updating is sensible for access to the latest app experience, while careful financial checking remains a separate responsibility.
My final view is positive but specific. Together Loans is a practical companion for managing an existing Together loan on Android, not a universal money-management solution. Its free, focused approach can make routine account checks and loan-related actions less scattered, especially for a first-time user who wants a clear path from installation to a confirmed result. I would recommend it when that is the problem you need to solve. If your goal is broader budgeting or comparing financial products, I would pair it with a different tool rather than expecting this app to do everything.
For me, the strongest test is whether I can open it with a clear purpose, find the relevant loan, complete one action carefully, and leave knowing what happened. If it provides that dependable routine, it earns a place on the phone. Just remember that the app organizes access to the loan; it does not replace the judgment needed to manage borrowing responsibly.
Pros
- Simple way to compare loan options in one place.
- May help users with limited credit explore available lenders.
- Online application process can save time and avoid branch visits.
- Loan details are presented before accepting an offer.
- Useful for checking potential borrowing options from a mobile device.
Cons
- Approval is not guaranteed after submitting an application.
- Available rates and terms may vary by applicant and lender.
- Some offers may include high interest or additional fees.
- Sharing financial information with multiple lenders may concern privacy-focused users.
- Loan availability and eligibility can depend on location and credit history.
FAQ's for Together Loans
What is Together Loans, and how does the app work?
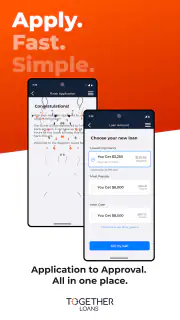
Together Loans is a lending service designed to help users explore borrowing options and manage loan-related requests from a mobile device. Depending on your location and eligibility, the service may collect personal and financial information, show available loan offers, or connect you with lending partners. It is important to understand that submitting an application does not guarantee approval, and the final lender determines the terms.
Is Together Loans available to everyone, and what eligibility requirements apply?
Eligibility depends on factors such as your age, residency, income, employment situation, credit profile, and the information provided during the application. Requirements can also vary according to the lender and the type of loan requested. Before downloading or applying, check whether Together Loans operates in your country or state, and review the official conditions carefully because availability may be limited.
How much can I borrow, and what will the loan cost?
The amount available through Together Loans is not necessarily the same for every user. Loan limits, interest rates, fees, repayment periods, and annual percentage rates may depend on your creditworthiness and the lender reviewing your request. Read the complete offer before accepting anything, paying particular attention to the total repayment amount, late-payment charges, and any origination or administrative fees.
Is Together Loans safe to use, and what personal information is required?
Loan applications commonly require sensitive details such as your name, contact information, address, income, employment data, identification information, and banking details. Use only the official app or website, verify the developer or provider, and review the privacy policy before submitting information. Avoid services that request upfront payment for guaranteed approval or pressure you to share unnecessary credentials.
How are repayments handled, and what should I do if I cannot pay on time?
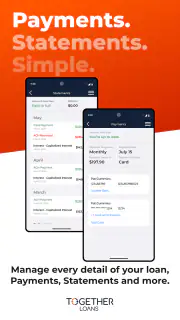
Repayment arrangements depend on the lender and the specific agreement you accept. Your offer should explain the payment schedule, available methods, due dates, and consequences of missed payments. Set reminders and keep enough funds available before each installment. If you expect difficulty paying, contact the lender as early as possible to ask about assistance, rather than ignoring notices or taking another costly loan.