
Borrow Cash Instantly WeDollar
Android OnlyFree·User Rating
 Analysis by ViaAPK
When an unexpected bill arrives, the hardest part is often not finding a finance app but deciding whether a fast cash advance is actually the right tool. I approached Borrow Cash Instantly WeDollar with that question in mind. It is a free finance app from Voronkov Moner App, built around the idea of requesting borrowed money through a mobile experience rather than starting with a traditional bank or searching through several lending services.
That narrow purpose is both its appeal and its warning sign. The app may be useful when speed and convenience matter more than exploring a broad range of financial products. At the same time, borrowing should never be judged only by how quickly an application can be opened. I would look at the repayment obligation, the total cost shown during the process, the information requested, and whether the amount fits comfortably into my next budget before treating an instant advance as a solution.
How I would decide whether WeDollar fits
My first decision criterion is urgency. If I need help covering a short gap between two predictable income dates, a focused cash-advance app can feel more practical than arranging a conventional loan. If the problem is a recurring shortage, however, borrowing through an app may only move the pressure forward. In that situation, a budgeting tool, a conversation with a bank, or a longer-term financial plan may be a better direction.
The second criterion is clarity. Before accepting any offer, I would want to see exactly what I receive, what I repay, when repayment is expected, and whether any applicable charges are displayed in plain language. A polished interface cannot replace those answers. WeDollar’s value depends less on the promise of instant access and more on how understandable the borrowing decision feels at each step.
The third criterion is fit for the situation. A person dealing with a one-time timing problem may evaluate the app differently from someone carrying several balances already. I would also separate a genuine emergency from an impulse purchase. Fast access can reduce waiting, but it can also make it easier to commit before thinking through the next paycheck.
There is a practical reason to make this assessment before installing. Finance apps often involve personal information and sensitive decisions, so I prefer to know my purpose first: the exact bill, the amount required, and the date by which I can repay it. That small preparation makes it easier to stop if the final terms do not match my plan.
The borrowing workflow matters more than the slogan
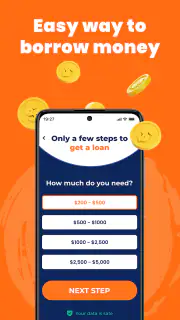
WeDollar presents itself as a way to borrow money instantly with cash-advance options. In everyday use, I would treat that as an invitation to examine the flow rather than a guarantee that every request will produce the same result. Approval, availability, and the final conditions can depend on the application process and the individual situation. The sensible approach is to read every screen instead of tapping through simply because the process feels quick.
News Worth Your Time
Brain Test 2 Suits the Stop-and-Start Rhythm of Modern Phones
Google Play Games Makes Android Gaming Easier to Navigate, Not Easier to Love
WhatsApp Under Pressure: How Well It Recovers When Messages Fail
UNO!™ Beyond the Table: How Rivalry Keeps Players Coming Back
LinkedIn: Dominating the Professional Networking Arena
Unlocking the Full Potential of Pixel Art - Color by Number
Roblox: A Creative Revolution in Gaming
Why Gallery Stands Out in the Photo App World
How Pi Network is Revolutionizing Social Cryptocurrency
Google TV's Ecosystem Strategy: Redefining Streaming
How Little Panda: Princess Makeup Thrives with New OS Updates
Why Decor Life - Home Design Game Stands Out in Creative Simulation
One useful habit is to write down the repayment amount before confirming anything. I would compare it with my expected income after rent, food, transport, and existing commitments. This is a more meaningful test than asking whether the requested amount looks small. A modest advance can still cause trouble if its repayment lands on an already crowded week.
Another helpful habit is to keep the purpose specific. If I opened the app because a utility payment was due, I would request only what addresses that gap, not treat the available borrowing route as extra spending room. This reduces the risk of turning a short-term bridge into a larger obligation.
What makes the app appealing for a narrow problem
The clearest strength is focus. WeDollar is not presented as a general investing dashboard, a full banking replacement, or a complex money-management suite. Its identity is centered on borrowing and instant cash advances. For someone who already understands the need and wants a mobile-first starting point, that focus can be easier to navigate than a broad finance app filled with unrelated tools.
It is also free to install, which removes an initial download barrier. That does not mean borrowing is free, and I would never interpret the app’s free price as a statement about the cost of an advance. Those are separate questions. I would judge the financial commitment only from the terms presented for the specific request.
The app is listed for Everyone, which makes its presentation approachable for a broad audience. Even so, an age label should not be mistaken for financial suitability. A simple interface may help people understand the process, but responsible borrowing still requires maturity, income awareness, and the ability to read the repayment details carefully.
Its current version is 2.0.2, and the app supports Android 7.0 or later. For someone using an older Android phone, checking the operating-system requirement before planning around the app is worthwhile. Compatibility is a small detail, but it becomes important when the need for money is time-sensitive and there is no room to discover an installation problem at the last minute.
Three practical ways I would use it responsibly
My first realistic scenario would be a short timing mismatch: an essential payment is due before a known income deposit, and I have already checked that the repayment will fit after necessary expenses. In that case, I would use WeDollar as a temporary bridge, record the repayment date in my calendar, and avoid taking another advance to cover the first one.
A second use case is comparison shopping within the borrowing category. I would open WeDollar alongside the usual alternatives I already trust, such as a bank’s short-term option or a credit-union conversation, then compare the actual repayment obligation rather than the speed of the application. The fastest route is not automatically the least expensive or safest route.
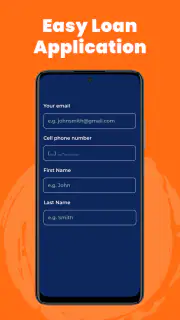
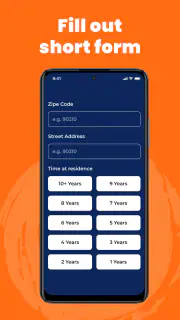
A third use case is simply learning whether the requested amount and conditions are realistic before committing. I would prepare my identification and financial details, move slowly through the review screens, and stop if the information appears unclear. That makes the app part of a decision process instead of an automatic button for emergency spending.
One less obvious trade-off is that convenience can reduce the natural pause that comes with visiting a branch or speaking to a financial adviser. I would deliberately recreate that pause by writing down three things: why I need the money, how I will repay it, and what I will do if my income arrives late. If I cannot answer the third question, I probably should not borrow yet.
Where traditional and broader alternatives may be better
WeDollar makes the most sense when the problem is immediate and limited. A conventional bank may be preferable when I need a larger, more structured loan, want an established relationship, or need to discuss several financial products together. A credit union or local adviser may suit someone who values personal guidance more than an entirely mobile process.
A budgeting app is a better alternative when the real issue is not a single emergency but repeated overspending. It can help identify patterns without adding a new repayment obligation. Likewise, negotiating a bill extension, asking an employer about an available advance, or speaking directly with the service provider may solve a temporary gap without entering a borrowing cycle.
I would also be cautious if I already have several active repayments. In that case, another instant advance can make the calendar harder to manage, even if the new amount looks manageable on its own. The right comparison is not “Can I get this money?” but “Will this decision leave my overall monthly commitments healthier or tighter?”
There is no universal winner among these categories. WeDollar’s advantage is directness and a finance experience organized around cash access. A bank may win on familiarity or broader account support. A budgeting tool may win when prevention matters more than borrowing. The best choice depends on whether I am solving a one-off timing issue or trying to change an ongoing financial pattern.
Questions I would answer before confirming a request
I would first ask whether the amount is genuinely necessary. If the purchase can wait, waiting is usually the cleaner financial choice. If it cannot wait, I would identify the minimum amount required instead of borrowing a rounded figure for convenience.
I would then ask when repayment will happen and whether that date is dependable. A plan based on uncertain income is fragile. I would also consider what happens if an expected deposit is delayed, because a cash advance does not remove the original uncertainty; it adds a new deadline to it.
Another question is whether I understand the total obligation. I would not rely on a headline such as “instant” or “cash advance.” I would read the final screen for the amount received, the amount due, the timing, and any other relevant condition. If those details are difficult to understand, I would pause rather than assume the best.
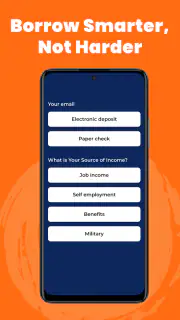
Finally, I would ask whether I am comfortable sharing the information required to evaluate a financial request. I would review each permission or data request in context and avoid treating access to my information as a minor formality. The convenience of a mobile application should not replace ordinary caution.
Reputation, access, and the cost of changing your approach
WeDollar has an average rating of 4.7 from around thirty thousand ratings, with more than one thousand written reviews and over one hundred thousand installs. Those figures suggest that many people have tried the app and that the overall public response is positive. I still would not use popularity as a substitute for reading the terms of my own request, because a good general impression cannot guarantee that every borrower’s circumstances are alike.
The developer is Voronkov Moner App, and the app is available at no purchase price. For me, the low entry barrier makes comparison easier: I can examine the experience without paying simply to install it. The real cost decision begins only when borrowing terms are presented, so I would keep the installation decision separate from the acceptance decision.
Switching from a bank or another finance service also has a cost that is easy to overlook: attention. I may need to learn a new workflow, check how repayment is organized, and maintain another financial relationship. If my existing provider already offers a clear short-term solution, moving to a separate app may add complexity without delivering enough benefit.
On the other hand, if my current option is slow, difficult to use, or poorly suited to a small emergency, a dedicated cash-advance experience may save time. I would make that switch only after comparing the complete obligation, not merely the first screen. Speed is valuable when a deadline is real, but clarity is more valuable when the consequences last beyond that deadline.
My recommendation for different kinds of users
I would recommend giving WeDollar a careful look to someone who needs a focused mobile route for a short-term cash gap, has a realistic repayment plan, and is prepared to inspect every condition before accepting. The app’s free access, finance-specific purpose, and straightforward positioning make it a reasonable candidate for comparison with other borrowing options.
I would not recommend it as a default response to regular money shortages, discretionary shopping, or existing repayment stress. In those cases, a budget review, direct negotiation, or advice from a bank or credit union may be more useful. Borrowing can solve timing, but it cannot repair an income-and-expense mismatch by itself.
My final test would be simple: after reviewing the request, can I explain the purpose, the repayment date, and the total obligation in one clear sentence? If yes, and the repayment comfortably fits my budget, WeDollar may be worth considering. If not, I would choose the slower option that gives me more time to understand the decision.
Overall, I see this as a focused tool rather than a complete financial solution. Its strongest case is a controlled, short-lived emergency where speed genuinely matters and the borrower remains in charge of the numbers. Used with that discipline, it can be a practical option. Used as an automatic answer whenever money feels tight, it is the wrong category of solution.
Pros
- Fast application process with minimal paperwork required.
- Clear repayment terms help users understand their borrowing obligations.
- Useful for handling short-term financial emergencies.
- Mobile access lets users manage applications from almost anywhere.
- May offer flexible loan amounts depending on eligibility.
Cons
- Interest and service fees can make short-term borrowing expensive.
- Approval and loan terms may vary based on personal credit information.
- Late payments could result in additional fees or credit consequences.
- Availability may be limited by location and eligibility requirements.
- Users should review privacy permissions before submitting financial details.
FAQ's for Borrow Cash Instantly WeDollar
What is Borrow Cash Instantly WeDollar?
Borrow Cash Instantly WeDollar appears to be a financial app designed to connect users with short-term borrowing or cash-advance options. Its availability, loan products, and eligibility requirements may vary by location and user profile. Before applying, review the provider information carefully and confirm whether the app is acting as a lender, broker, or referral service.
Can I really receive money instantly through WeDollar?
The word “instantly” should not be interpreted as a guarantee. Application review, identity verification, banking hours, eligibility checks, and the selected payment method can all affect how quickly funds arrive. Some users may receive a decision quickly, while others may experience delays or be asked for additional documentation before any money is deposited.
How much does borrowing through Borrow Cash Instantly WeDollar cost?
Before accepting an offer, carefully check the annual percentage rate, interest, origination or service fees, late charges, repayment schedule, and total amount due. The cost can differ significantly depending on the lender and your personal circumstances. Never rely only on an advertised loan amount or payment estimate; read the complete agreement and all disclosures.
What personal information does the app require?
A borrowing application may request information such as your name, contact details, identification, income, employment, bank account, and payment information. Only provide sensitive data after confirming that the app is legitimate, securely connected, and transparent about how information is used. Review its privacy policy and permissions, and avoid submitting details through unofficial download links.
Is Borrow Cash Instantly WeDollar safe and available in my country?
Safety and availability depend on the official publisher, local financial regulations, and the specific version of the service offered in your region. Download the app only from a trusted store, verify the developer name, read recent user reviews, and check whether the company is properly registered where required. Also confirm that repayment terms are manageable before borrowing.