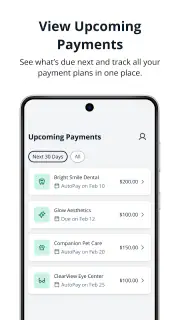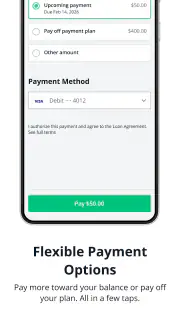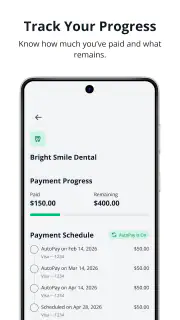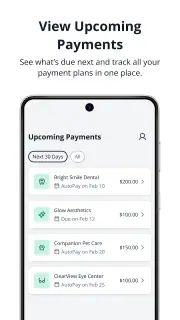

Cherry: The Smarter Way to Pay
Android OnlyFree·User Rating
 Analysis by ViaAPK
When a planned payment is easier to manage than a surprise charge, the right tool can make a noticeable difference. I tested Cherry as a finance app built around organizing payment plans and paying according to a schedule, and I found its appeal fairly clear: it is aimed at people who want a more deliberate way to handle planned expenses instead of treating every payment as a one-off task.
Cherry is free to use, comes from Cherry Technologies, Inc., and is suitable for Everyone. It has reached over one hundred thousand installs, with an average rating of four point five from more than one hundred ratings. Those figures suggest a useful level of early interest, although the relatively small review pool means I would treat the rating as encouraging rather than definitive.
From an upcoming payment to a manageable plan
I find the most useful way to judge a payment-planning app is to follow one real expense from the moment it comes to mind through the point when I’m ready to act. That makes it easier to see whether the schedule reduces last-minute scrambling or merely adds another place to check. From there, I’d look at how a plan fits into the rest of an ordinary month.
Starting with the expense in front of you
The most natural way to use Cherry is to begin with a payment that already has a purpose. That might be an expense you want to organize before committing, or an existing plan that you need to keep track of. Instead of forcing the user to remember every detail mentally, the app gives the situation a dedicated place in a finance-focused workflow.
That distinction matters. A normal banking app is usually designed to show money moving in and out. A notes app can record a reminder, but it does not make the reminder feel connected to a payment routine. Cherry sits between those habits by focusing on plans and timing. In my experience, that makes it more useful for someone who thinks in upcoming obligations rather than only in completed transactions.
The first practical tip is to enter a plan while the details are still fresh. Waiting until a payment is almost due makes any finance tool feel like a last-minute alarm. Adding it earlier lets you use the schedule as a planning aid, not merely as a record of something you forgot. This is one of the app’s more valuable ideas, even though it is easy to overlook when approaching it as just another payment utility.
Building a schedule that matches real life
Once the expense is identified, the important question becomes how the payment should fit into your routine. Cherry’s central promise is not simply to show a balance; it is to help you manage a plan and pay on your schedule. That makes the timing of each obligation the key part of the experience.
News Worth Your Time
Brain Test 2 Suits the Stop-and-Start Rhythm of Modern Phones
Google Play Games Makes Android Gaming Easier to Navigate, Not Easier to Love
WhatsApp Under Pressure: How Well It Recovers When Messages Fail
UNO!™ Beyond the Table: How Rivalry Keeps Players Coming Back
LinkedIn: Dominating the Professional Networking Arena
Unlocking the Full Potential of Pixel Art - Color by Number
Roblox: A Creative Revolution in Gaming
Why Gallery Stands Out in the Photo App World
How Pi Network is Revolutionizing Social Cryptocurrency
Google TV's Ecosystem Strategy: Redefining Streaming
How Little Panda: Princess Makeup Thrives with New OS Updates
Why Decor Life - Home Design Game Stands Out in Creative Simulation
I would approach setup with a simple rule: use a schedule that reflects when you can realistically act, rather than choosing a date that looks tidy on screen. A plan that matches your actual payday or budgeting rhythm is easier to maintain than one that requires constant adjustment. This is especially helpful for people who handle several planned expenses and need to see them as a sequence instead of a pile of unrelated reminders.
There is also a useful trade-off here. A scheduled approach can create calm because it makes the next step visible, but it requires honest input from the user. Cherry cannot make an unrealistic plan comfortable. If the timing does not fit your income pattern, the app may organize the problem without solving it. I see that as a limitation of the workflow rather than a defect: the app helps structure a decision, but you still have to make a sensible one.
Checking the plan before paying
Before moving forward, I would review the plan as a whole rather than looking only at the next payment. This is where Cherry can be more helpful than a basic reminder. The point is to understand the path from the starting obligation to the eventual completion, including whether the schedule feels manageable alongside other commitments.
That broader check is particularly useful when several expenses compete for attention. A calendar reminder might tell you that something is due, while a plan-oriented finance app encourages you to think about the payment as part of a longer sequence. My advice is to use that moment to ask whether the schedule is still realistic, whether the expense remains a priority, and whether another payment is likely to land at the same time.
For a person who prefers complete control over every transaction, this stage may feel less satisfying than working directly inside a bank or card application. Cherry is better suited to organizing the intention behind a payment. It should complement careful financial judgment, not replace it.
The handoff from planning to action
The most important handoff in this workflow is the move from a planned obligation to an actual payment. Planning tools can be excellent at making the next step visible, but the user still needs confidence that the action is happening in the right place and at the right time. I would therefore treat Cherry as the planning layer and verify the final payment details before confirming anything.
This habit protects against a common mistake: confusing a well-organized schedule with a completed transaction. A plan can be accurate and still require a separate action. Keeping that distinction clear makes the app safer to use as part of a broader money routine. I would check the amount, timing, and destination at the handoff rather than assuming that saving a plan automatically settles the obligation.
That is also where Cherry differs from the usual alternatives. A bank app is generally stronger for direct account activity and transaction history. A spreadsheet is more flexible for custom calculations and long-term comparisons. A reminder app is quicker for a single deadline. Cherry’s advantage is the middle ground: it gives a payment-related task more structure than a reminder without asking the user to build a financial system from scratch.
A realistic everyday scenario
Imagine I have a planned expense arriving during a busy month, alongside rent, household costs, and another scheduled commitment. With a basic reminder, I might note one date and then forget how that payment fits with everything else. With a spreadsheet, I could create a detailed model, but that would take more effort than the expense deserves.
Using Cherry, I would start by recording the planned payment, set its schedule around my normal budgeting routine, and review the upcoming sequence before the payment becomes urgent. When the time arrives, I would use the plan as a prompt, verify the final details, and then confirm the payment through the appropriate process. Afterward, I would return to the plan to keep my view of the remaining schedule accurate.
The benefit is not dramatic automation; it is reduced mental juggling. The app gives the expense a path: identify it, schedule it, review it, act on it, and keep track of what remains. For me, that is a more realistic promise than expecting a finance app to solve every budgeting problem.
Where the workflow is strongest
Cherry works best when the user has a specific payment plan that deserves more attention than a simple calendar entry. It is a good fit for people who want to spread attention across scheduled obligations, especially when timing matters as much as the amount. The free price also lowers the barrier to trying that workflow without first committing money to a new finance service.
I can also see it helping users who dislike overly complicated budgeting software. Some finance apps present so many categories, charts, and account views that a single payment becomes difficult to isolate. Cherry’s narrower purpose can feel more approachable because the user starts with a plan rather than an entire financial history.
Another non-obvious strength is the way it encourages a pre-payment pause. That pause is valuable because it creates a chance to notice conflicts before they become urgent. If I see that two planned payments overlap, I can reconsider the schedule while there is still time. A notification after the fact would be less useful.
Where the flow breaks down
The same focus can become a weakness for users who want a complete financial command center. If your main need is investment tracking, detailed spending analysis, account aggregation, or advanced budgeting, Cherry is unlikely to be the only tool you need. Its value comes from managing plans and payment timing, not from replacing every finance feature in your life.
There is also some unavoidable friction at the handoff to payment. A user may still need to confirm details elsewhere, and that extra step can feel less seamless than paying directly inside a banking app. I consider that an important expectation to set: Cherry can organize the route, but the final action should still be checked carefully rather than treated as invisible automation.
People who rarely have planned payments may not gain much from installing it. If your expenses are simple, predictable, and already covered by your bank’s tools, another app may add more maintenance than value. Likewise, users who prefer a highly customizable spreadsheet may find Cherry too focused, while users who want instant one-tap payment may prefer a direct payment provider.
Practical habits that make it more useful
I would keep each plan understandable at a glance. Use a clear description that distinguishes one obligation from another, and review the schedule whenever your monthly routine changes. The app is most useful when it reflects your current situation, not when it becomes a collection of outdated intentions.
I would also separate planning from confirmation. First use Cherry to decide when a payment belongs in your routine. Then, at the handoff, verify the final details through the payment channel you are using. This two-stage habit may feel slower, but it reduces the chance of acting on an old schedule or mistaken assumption.
A third useful habit is to review plans in batches. Rather than opening the app only when an alert appears, choose a regular moment to look at upcoming obligations together. That turns Cherry from a reactive reminder into a small planning checkpoint. It is especially helpful when several payments are close together and the main risk is not forgetting one item, but underestimating the combined effect.
How the current release feels
The current version is 1.3.0, and my overall impression is of a focused finance app rather than an overloaded personal-finance suite. Its strongest quality is clarity of purpose: the experience is centered on plans and scheduled payments, so the user can approach it with one concrete task in mind.
That focus also means I would not judge it by the standards of a full bank application. A bank app wins when I need immediate account balances, transaction controls, or a definitive record of money already moved. Cherry wins earlier in the process, when I am deciding how a planned payment should fit into my schedule.
The app was released on February 20, 2026, so its public track record is still relatively young. Its early reception is positive, with a four point five average and more than one hundred ratings, while the install count has passed one hundred thousand. I would read that as a promising start, not as proof that it will suit every financial routine.
Who should use it, and who should skip it
I would recommend Cherry to someone who regularly manages planned payments and wants a dedicated schedule instead of scattered reminders. It is also worth considering if you find full budgeting suites intimidating but still want more structure than a note or calendar event can provide.
I would skip it if your priority is comprehensive account management, detailed spending reports, or direct banking controls. In those cases, your existing bank app or a broader finance platform may be the better primary tool. I would also skip it if you have very few scheduled obligations and already remember them reliably, because adding another workflow may not improve anything.
My final take on the payment journey
Cherry succeeds by making the middle of a payment journey more deliberate. You begin with an upcoming obligation, shape it into a schedule, review how it fits with other commitments, and then hand off the final action with the details still fresh. That sequence is more useful than a generic promise to “manage money” because it addresses a specific everyday problem: keeping planned payments from becoming last-minute surprises.
It is not a replacement for a bank, a full budget, or careful financial judgment. The handoff to actual payment deserves attention, and users with broader finance needs may quickly outgrow its focused approach. Still, for the right person, the simplicity is the point. Cherry is most valuable when you need a clear payment plan, not another complicated dashboard.
As a free Finance app from Cherry Technologies, Inc., it is easy to try and simple to position alongside the tools you already use. I would recommend starting with one real upcoming expense, following it from setup through confirmation, and then deciding whether the scheduled workflow genuinely reduces effort. In my experience, that is the fairest test of its value: not how many features it appears to have, but whether it helps you reach the payment with fewer surprises and a clearer next step.
Pros
- Splits eligible purchases into manageable installment payments.
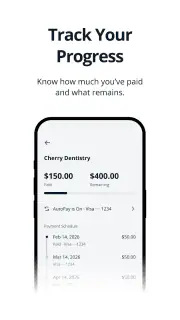
- Clear repayment schedules help users plan upcoming expenses.
- Useful for shoppers seeking flexible payment options at checkout.
- Digital application process is generally quick and convenient.
- Can help spread larger costs without using a traditional credit card.
Cons
- Late or missed payments may lead to fees or account restrictions.
- Approval and spending limits depend on personal financial information.
- Not every retailer or purchase qualifies for Cherry financing.
- Installments can encourage spending beyond your original budget.
- Terms and availability may vary by location and merchant.
FAQ's for Cherry: The Smarter Way to Pay
What is Cherry: The Smarter Way to Pay?
Cherry is a healthcare financing and payment platform that allows eligible patients to divide the cost of certain medical, dental, cosmetic, and wellness treatments into manageable installments. Instead of paying the full amount upfront, you can apply for a payment plan through participating providers. Available options, approval decisions, repayment periods, and total costs may vary depending on your application and the provider’s terms.
How does Cherry financing work?
After choosing a participating healthcare provider and selecting Cherry as a payment option, you generally complete an application with information needed to assess eligibility. If approved, the app or provider presents available payment plans before you accept one. Review the installment amount, schedule, fees, and total repayment carefully. Cherry then facilitates the payment arrangement while you repay according to the agreed schedule.
Does using Cherry affect my credit score?
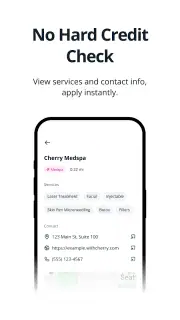
Cherry may use different types of credit checks or financial information during the application process, and the effect can depend on the specific financing product and your circumstances. Approval is not guaranteed, and terms may differ between applicants. Before submitting an application, read the disclosures shown in the app or provided by the clinic to understand whether a credit inquiry, reporting, or other eligibility review may apply.
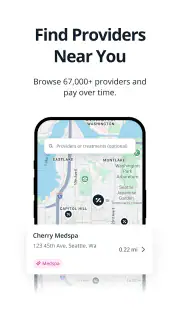
What treatments and providers can I use Cherry with?
Cherry is not accepted at every clinic or for every service. Its availability depends on whether the healthcare provider participates in the Cherry network and whether the treatment qualifies under the provider’s financing arrangements. It may be offered for services such as dental work, elective procedures, vision care, or wellness treatments, but coverage varies. Confirm eligibility, pricing, and payment options directly with the provider before booking.
Are there fees, interest, or other costs with Cherry payment plans?
The cost of a Cherry plan depends on the offer you receive, the repayment term, the provider, and applicable financing conditions. Some plans may advertise promotional or low-cost options, while others can include interest or other charges. Carefully compare the amount financed with the total amount you will repay, check for late-payment consequences, and make sure the scheduled installments fit your budget before accepting.