
Cashli: Cash Advance & Rewards
Android OnlyFree·User Rating
 Analysis by ViaAPK
Cashli: Cash Advance & Rewards caught my attention because it addresses a very specific financial moment: needing a small amount of money before the next payday. I approached it less like a general budgeting tool and more like a short-term cash option that might also give me a reason to return. That distinction matters. An app can feel useful during one urgent week without becoming something I want on my phone permanently.
Cashli is a free finance app from Cashli Funds, available for users aged Everyone. It has reached over one hundred thousand installs and holds a 4.1 average from around 4.9 thousand ratings, with roughly 2.8 thousand written reviews. Those figures suggest that the idea has found a real audience, but they do not change the basic question I would ask before installing it: will the convenience of a cash advance outweigh the attention and discipline required to use one responsibly?
My answer is cautiously positive for a narrow group of users. If you occasionally face a timing problem between income and an unavoidable expense, Cashli may be worth investigating. If you are looking for a complete money-management system, dependable long-term savings help, or a replacement for a conventional bank, I would look elsewhere. Its appeal is immediate and practical; its lasting value depends heavily on whether you treat it as an emergency tool rather than extra income.
What the first week feels like
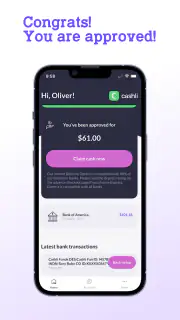
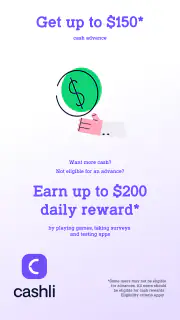
The first impression is shaped by urgency. The app’s central promise is access to up to 150 bucks, which makes the purpose easy to understand without a long learning curve. I do not have to decode a complicated investment dashboard or build a detailed spending plan before seeing why someone might want it. For a person dealing with a bill that arrives a few days before payday, that directness is the strongest part of the experience.
That convenience also creates the first important trade-off. A small advance can solve a short gap, but it does not improve the underlying balance of a monthly budget. I would use Cashli only after identifying the exact expense, the date money should arrive, and the realistic way the advance will be handled afterward. Opening the app because I am stressed, rather than because I have a specific plan, would make the product much less useful.
The rewards angle gives the app a second reason to exist. It can make the experience feel less like a single-purpose emergency button and more like a service I might revisit. Still, I would not install it solely for the possibility of rewards. Rewards are most valuable when they fit naturally into something I already need to do; they are not a good reason to spend more time, money, or attention than the benefit is worth.
One practical tip is to separate the decision into two questions. First, do I need a short-term advance at all? Second, does Cashli offer a sensible way to manage that need? Keeping those questions apart prevents the app’s friendly rewards framing from making borrowing feel casual. That is a small mental habit, but it is more important here than any attractive first-session experience.
News Worth Your Time
Brain Test 2 Suits the Stop-and-Start Rhythm of Modern Phones
Google Play Games Makes Android Gaming Easier to Navigate, Not Easier to Love
WhatsApp Under Pressure: How Well It Recovers When Messages Fail
UNO!™ Beyond the Table: How Rivalry Keeps Players Coming Back
LinkedIn: Dominating the Professional Networking Arena
Unlocking the Full Potential of Pixel Art - Color by Number
Roblox: A Creative Revolution in Gaming
Why Gallery Stands Out in the Photo App World
How Pi Network is Revolutionizing Social Cryptocurrency
Google TV's Ecosystem Strategy: Redefining Streaming
How Little Panda: Princess Makeup Thrives with New OS Updates
Why Decor Life - Home Design Game Stands Out in Creative Simulation
Who gets the most value right away
I see the clearest fit for someone with predictable income and a temporary timing mismatch. Imagine a user whose utility payment is due shortly before a regular paycheck, while the amount needed is modest and the next income date is certain. Cashli may be useful as a bridge if the user understands the repayment implications and does not already rely on several similar services.
It may also suit someone who wants a simple, focused financial app rather than a full personal-finance suite. The limited scope can be an advantage: fewer dashboards and fewer categories mean less setup before dealing with the immediate problem. For a first-time user, that simplicity is easier to approach than a traditional credit product filled with unfamiliar terminology.
I would be more hesitant for anyone whose income changes sharply from week to week, whose existing bills already consume nearly everything, or who is using one advance to cover another. In those situations, the app may relieve today’s pressure while increasing next month’s. A credit union, a direct conversation with a bill provider, a conventional bank product, or free debt advice could be a better route, depending on the circumstances.
Questions I would settle before requesting money
The most important details are not the headline amount. Before using the advance, I would read every screen related to eligibility, repayment, timing, and any applicable cost or obligation. The exact amount I can access may differ from the maximum, and the practical value depends on when the funds arrive and what happens afterward. I would never assume that “up to” means the full amount is available to every user.
I would also check what information the app asks me to provide and why, then review the permissions and terms presented during setup. Financial apps deserve a slower installation process than casual entertainment apps. If I do not understand a condition, I would stop before accepting it rather than relying on the store summary or a quick glance at the first screen.
Another useful habit is to record the advance outside the app. A note in my regular budget, calendar, or banking routine can show the future impact more clearly than a balance displayed in one separate service. This is particularly helpful when several bills fall close together. Cashli can be the place where I request help, but it should not become the only place where I remember the obligation.
Does it still earn space after the novelty fades?
I’d judge Cashli by whether it stays useful for an occasional, clearly planned cash-flow gap rather than by how often it draws me back. That makes a simple personal check worthwhile: after each use, note whether it reduced stress without creating a harder squeeze later. If that balance changes, the next section’s focus on readability and navigation becomes especially important, because clarity helps me make a deliberate choice instead of a rushed one.
Month-to-month value depends on restraint
After the first urgent use, Cashli has to justify its place through recurring value. That is where my enthusiasm becomes more measured. The advance function is inherently occasional for a financially stable user. If I need it every month, the problem is probably not a single awkward payday gap. It is a budget shortfall, and an advance app cannot permanently correct that.
The rewards component may encourage continued engagement, but I would judge it by effort rather than excitement. A reward is worthwhile when it arrives as a by-product of sensible activity and does not push me toward unnecessary spending, repeated checking, or borrowing I would otherwise avoid. If maintaining the benefit requires constant attention, the app starts to feel like another task rather than financial help.
This is the non-obvious long-term trade-off: a product can be free to install while still costing time, focus, and future flexibility. I would measure its value by the amount of stress it removes, not by how often I open it. If I spend several minutes each week chasing a small benefit, while also worrying about repayment, the balance may not be favorable.
For month-to-month use, I would create a simple rule: only open Cashli when I have a planned reason. That might be reviewing an existing obligation, checking a reward that is already relevant, or handling a genuine short-term gap. I would avoid turning the app into a daily financial ritual. This keeps the service in its proper role and reduces the chance that frequent engagement makes borrowing seem normal.
Maintenance is light, but financial responsibility is not
The app itself appears easier to maintain than a full budgeting platform because its purpose is narrower. I do not need to build a complete household ledger to understand why it exists. That makes it less demanding than apps that require constant transaction categorization, account linking, or detailed goal updates. For a user who dislikes financial administration, this focused design can be refreshing.
However, the low setup burden should not be confused with low responsibility. I still need to monitor my bank balance, remember future deductions or repayments, and make sure an advance does not collide with rent, food, transport, or other essentials. The app can reduce friction at the point of access, but it cannot make a tight budget safe by itself.
I would also review the app periodically rather than leaving it forgotten on my phone. Cashli Funds lists the current version as 1.0.19, and the app requires Android 8.0 or later. Keeping the application updated is sensible for any financial service, but I would also revisit its terms and notification behavior after updates. A financial tool deserves occasional housekeeping even when I am not actively using it.
One practical workflow is to set a personal “exit check” after each advance. Once the money has served its stated purpose and the resulting obligation is settled, I would ask whether the app helped with a one-off timing issue or whether I am beginning to depend on it. That short review turns an impulsive tool into a controlled part of my financial routine.
Where fatigue can appear
The first source of fatigue is repetition. An advance feels helpful when the situation is unusual; it feels discouraging when the same gap returns every pay cycle. The more often I need to solve the same problem, the less convincing the app’s convenience becomes. At that point, I would want to examine income timing, recurring bills, overdraft habits, and available support instead of simply repeating the same action.
The second is uncertainty. Users naturally want to know how much they can receive, when it will arrive, and what they will need to do later. If any of those answers require careful reading or depend on personal eligibility, the experience may feel less immediate than the headline suggests. That is not necessarily a flaw, because financial decisions should include conditions, but it does mean I would avoid planning an essential payment around money that has not been confirmed.
The rewards framing can create a different kind of tiredness. If I have to keep checking, completing actions, or thinking about the app to receive value, the mental overhead may exceed the benefit. I would be especially cautious if rewards encourage spending or make me feel that I must stay active to avoid missing something. A good financial habit should make my life calmer, not turn small incentives into another source of pressure.
There is also a comparison problem. Traditional banks may offer more established account tools, clearer integration with everyday money, or products designed around longer-term credit needs. Budgeting apps may provide better visibility into recurring expenses and savings goals. Cashli’s advantage is focus and accessibility, not breadth. Choosing it over those alternatives makes sense only when the immediate cash-advance use case is the one I actually need.
How it compares with familiar alternatives
Compared with an overdraft, Cashli may feel more intentional because I can approach it as a separate request instead of allowing a bank balance to fall below zero automatically. But that separation is useful only if I understand the full terms and keep track of the future impact. An overdraft may be more convenient for some existing bank customers, while Cashli may be more approachable for someone seeking a dedicated short-term option.
Compared with a credit card, the app is narrower and potentially easier to understand at a glance, but it does not provide the same broad purchasing flexibility. A credit card can be useful for established users who pay the balance reliably and understand their agreement. Cashli is better considered for a defined, short-lived need rather than as a general payment method.
Compared with a budgeting app, Cashli addresses liquidity rather than visibility. A budgeting tool can help me discover that subscriptions, irregular bills, or poor timing are causing the problem. Cashli may help me get through the immediate moment, but it is not the substitute for that diagnosis. In my view, the two categories solve different parts of the same situation, and the budgeting option is better when the issue keeps returning.
Compared with borrowing from friends or family, Cashli offers a more formal and private route, which some users will value. Personal borrowing can also carry emotional pressure, so a dedicated service may feel cleaner. On the other hand, a trusted person may offer flexibility that an app cannot. I would choose based on clarity, safety, and the relationship involved, not on convenience alone.
Who should skip it
I would skip Cashli if I could not explain exactly how an advance would fit into my next income cycle. I would also avoid it if I were already behind on essential payments, using multiple short-term services, or hoping the app would create extra spending room. Those are signs that the right solution needs to be broader than a temporary cash bridge.
I would also choose another option if my main goal were building savings, tracking every account, planning debt repayment, or learning where my money goes. Cashli’s focused purpose is not a weakness for the right user, but it becomes a limitation when I expect a complete financial command center.
Finally, I would not keep it installed just because it is free. A free finance app still deserves a clear role. If I have no realistic need for a short-term advance and the rewards do not fit my habits, removing it may be the better maintenance decision. Fewer financial prompts can be valuable when my finances are already stable.
My long-term verdict
Cashli earns a place on my shortlist as a targeted emergency option, not as a permanent answer to everyday cash flow. Its strongest qualities are the clear focus on a small advance, the approachable presentation, and the added rewards angle. The free price and Everyone age rating make it easy to consider, while the current Android requirement keeps compatibility straightforward for users on Android 8.0 or newer.
The app’s lasting value depends on boundaries. I would use it for a specific, temporary need, read the conditions carefully, record the obligation in my normal budget, and avoid treating rewards as a reason to borrow or spend. That workflow preserves the useful part of the service while limiting the habits that can make short-term finance products stressful.
My recommendation is therefore conditional but genuine: Cashli is worth exploring if you have predictable income, a clearly defined short gap, and the discipline to treat an advance as a future commitment. It is not the app I would recommend for rebuilding a budget or solving recurring financial strain. Its best role is a controlled bridge, not a second paycheck.
After the novelty fades, that is the standard I would apply. If the app helps me handle an occasional timing problem without demanding constant attention, it has earned useful space. If I find myself checking rewards, requesting advances repeatedly, or postponing a larger financial fix, it is time to step back and choose a broader alternative. In that sense, Cashli can be helpful precisely when I use it sparingly.
Pros
- Fast cash advances can help cover unexpected expenses.
- Rewards provide extra value for completing eligible activities.
- Simple application process with a user-friendly interface.
- Repayment terms and fees are shown before accepting an advance.
- Useful budgeting features may help users monitor short-term finances.
Cons
- Advance availability and limits may vary by user and location.
- Fees can make borrowing expensive compared with traditional options.
- Late repayment may affect future eligibility or add extra costs.
- Rewards may require significant time or activity to accumulate.
- Requires sensitive personal and financial information during signup.
FAQ's for Cashli: Cash Advance & Rewards
What is Cashli: Cash Advance & Rewards, and how does it work?
Cashli: Cash Advance & Rewards is a financial app designed to help eligible users access potential cash advances while also offering rewards-related features. After creating an account, you may be asked to provide personal, employment, income, or banking information so the service can assess eligibility. Available amounts, fees, repayment terms, and approval decisions can vary by user and location.
Is Cashli a guaranteed loan or a free money app?
No. Cashli should not be treated as guaranteed income, free money, or an automatic loan approval service. Access to a cash advance depends on eligibility requirements, verification, and the terms presented inside the app. Before accepting an offer, carefully review any applicable subscription charges, service fees, transfer costs, repayment dates, and other conditions to understand the total amount you may owe.
What information does Cashli require, and is it safe to use?
The app may request identifying, financial, employment, device, and bank-account information to provide its services or connect users with financial products. Before registering, read the privacy policy and permissions carefully, and confirm why each piece of information is needed. Use only the official Google Play or App Store listing, avoid sharing login codes, and contact support if you notice suspicious activity.
How quickly can I receive money through Cashli?
The timing of a cash advance can depend on approval, identity verification, banking details, weekends, holidays, and the delivery method selected. Some users may receive funds quickly, while others may experience delays or may not qualify at all. Any instant or expedited transfer option could involve an additional fee, so check the final confirmation screen before accepting the transaction.
Are there repayment requirements, fees, or subscription costs to consider?
Potentially, yes. Depending on the product or offer available to you, Cashli may involve repayment obligations, transfer fees, membership or subscription charges, or other costs. The exact terms can change and may differ by state or country. Read the agreement and fee disclosure in full, confirm the repayment date, and cancel unwanted subscriptions through the correct account or app-store settings.