
Jim: sell & get paid instantly
Android OnlyFree·User Rating
 Analysis by ViaAPK
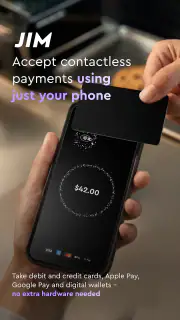
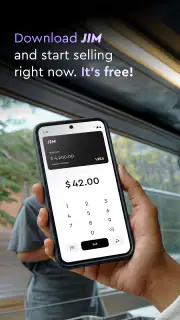
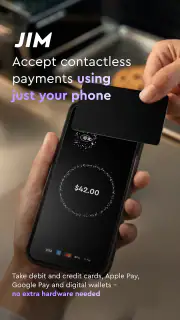
Jim: sell & get paid instantly is a finance app from CloudWalk that turns an Android phone into a card reader. I approached it as a practical tool for small sellers rather than as a general banking app, and that distinction matters. Its purpose is narrow but useful: accept card payments while working away from a permanent checkout counter.
My first impression is that Jim makes the most sense when mobility is part of the job. A market stall, a home-based service, a pop-up table, or a person who occasionally sells directly to customers can benefit from having payment acceptance in the same device they already carry. I would not choose it simply because it is free; I would choose it because the phone-based workflow fits the way I collect money.
The app is free and rated for Everyone, which makes it approachable for a broad audience. It has an average rating of 4.3 from around 2.2 thousand ratings, with over 100 thousand installs. Those figures suggest that Jim has attracted a meaningful early audience, although I would still judge it by the payment routine I actually need rather than by popularity alone.
Where Jim fits in a real selling routine
I find Jim most useful when it becomes one dependable step in a broader selling routine, rather than something I open only when a customer asks about cards. I’d decide where the phone sits, how I check a completed payment, and what I’ll do if the app or connection isn’t ready; those small choices make mobile selling calmer. That routine also makes it easier to see which settings deserve attention before the next sale.
A useful alternative to a traditional terminal
The clearest advantage is portability. A conventional card terminal is a separate object to charge, carry, protect, and remember. Jim places the payment task on a phone, so the seller can keep the catalog, customer conversation, and transaction process close together. For someone who sells at changing locations, that can remove a surprisingly large amount of friction.
I can imagine using it at a weekend craft table. Instead of sending a customer away to find cash or asking them to complete a transfer later, I could open the payment flow on the phone, handle the sale at the table, and continue serving the next person. The benefit is not just speed; it is having a single, familiar device available when the sale happens.
That same setup can help a mobile professional. A tutor, repair worker, stylist, photographer, or independent food seller may finish a job somewhere without a fixed checkout. Jim is more relevant in that moment than a full retail system designed around shelves, staff accounts, inventory, and a permanent register.
News Worth Your Time
Brain Test 2 Suits the Stop-and-Start Rhythm of Modern Phones
Google Play Games Makes Android Gaming Easier to Navigate, Not Easier to Love
WhatsApp Under Pressure: How Well It Recovers When Messages Fail
UNO!™ Beyond the Table: How Rivalry Keeps Players Coming Back
LinkedIn: Dominating the Professional Networking Arena
Unlocking the Full Potential of Pixel Art - Color by Number
Roblox: A Creative Revolution in Gaming
Why Gallery Stands Out in the Photo App World
How Pi Network is Revolutionizing Social Cryptocurrency
Google TV's Ecosystem Strategy: Redefining Streaming
How Little Panda: Princess Makeup Thrives with New OS Updates
Why Decor Life - Home Design Game Stands Out in Creative Simulation
What the phone-based approach changes
Using a phone as a reader also changes the responsibilities of the seller. Battery level, connectivity, screen visibility, and device security become part of accepting payment. I would prepare the phone before opening for business, keep it charged, and avoid treating the app as a magical replacement for every piece of payment equipment.
This is one of the important trade-offs. A dedicated terminal is built around payments and may feel more natural during a long queue. Jim is more convenient when I value light equipment and occasional mobility. If I process customers continuously for hours, I would compare the comfort and reliability of a dedicated device with the convenience of using my existing phone.
The app runs on Android 7.0 or newer, so compatibility is fairly broad for Android users. Still, operating-system support is only the starting point. The phone itself needs to be in good working order, and I would test the complete payment flow before relying on Jim at an event where a failed transaction would be embarrassing or costly.
Why the developer and app maturity matter
CloudWalk is the developer behind Jim, and the current version is 1.4.19. The app was released on January 5, 2026, which places it in an early stage of its public life compared with long-established payment tools. I see that as a reason to test carefully, not as an automatic warning.
A newer app can have a cleaner workflow and may be designed around current phone habits. At the same time, a seller should avoid assuming that a growing install base means every unusual business situation has already been covered. I would begin with small, low-pressure transactions and learn how the app behaves before making it the only payment route at a busy event.
Trust starts with the moment money is involved
Finance apps deserve a different standard from ordinary utilities. I am comfortable judging Jim by its clear purpose, but I would not install it casually on a shared phone or hand the device to another person without thinking about account access. The phone becomes part of the payment environment, so physical access and screen privacy matter.
My practical habit would be to use a dedicated business profile on the phone when possible, keep the operating system maintained, and lock the device whenever it is not in my hand. I would also separate personal notifications from customer-facing payment moments. A message preview appearing during a sale is not a payment failure, but it is an avoidable privacy problem.
Trust also depends on knowing what I am approving at each stage. Before accepting a transaction, I would read the amount and customer-facing confirmation carefully rather than tapping through automatically. That small pause is especially valuable when the seller is distracted, the queue is long, or several products have similar prices.
Controls I would check before the first sale
Jim’s value depends on the account and payment controls available during actual use. Before taking live payments, I would look through the app’s account area and transaction screens to understand how I can review activity, recognize completed payments, and manage access to the account. These are not glamorous features, but they are what make a finance tool usable after the customer has left.
I would pay particular attention to the difference between a payment that is merely being processed and one that is clearly completed. A seller should not rely only on a customer’s screen or verbal confirmation. The safest routine is to check the status shown in the seller’s own app before handing over an expensive item or marking an order as settled.
Another useful habit is to keep a simple external sales note for the day. Jim may handle the payment step, but a seller still needs a way to match the transaction with the product, customer, or appointment. That record can be a basic notebook or a separate business system. It prevents the common mistake of expecting a card reader to replace bookkeeping.
I would also decide in advance who is allowed to use the phone. If an assistant helps at a stall, the seller should establish a clear handoff routine and avoid leaving the account open while walking away. A payment app is not just another point-of-sale screen; it is access to a financial workflow.
Data-sensitive moments deserve attention
Payment activity is sensitive even when the interface looks simple. I would read the app’s permission prompts and privacy choices as they appear on my device, granting only what is necessary for the payment experience I intend to use. I would not approve a request automatically just because the app belongs to the finance category.
The most important moment is installation and first setup. That is when I would slow down, read the account terms and privacy explanations presented in the app, and note what information is requested. If a prompt is unclear, I would pause rather than guess. This is a better approach than trying to reconstruct the app’s data behavior after a problem occurs.
The second sensitive moment is a shared selling environment. A phone used by several people can expose account screens, transaction details, notifications, or customer information. I would keep the device facing the seller, limit unnecessary previews, and close the session when the work period ends.
The third is a lost or replaced phone. Before depending on Jim, I would understand how account recovery works and make sure I can reach the relevant support route from another device if needed. I would also keep the phone protected with its normal screen lock. A payment app should never be treated as safe merely because the phone is usually in my pocket.
How much control does the seller retain?
Good payment software should help me make deliberate decisions rather than rush me through them. In practice, user agency means being able to inspect the amount, choose when to start a transaction, recognize its result, and keep track of what happened afterward. I would use Jim only if those moments feel understandable on my own phone.
That is why I would run a rehearsal before serving customers. I would open the app, explore the main screens, check how a transaction is presented, and practice ending the flow without pressure. The goal is not to create a fake payment or mislead anyone; it is to learn where the important confirmations appear and how quickly I can find the information I need.
I would also create a short staff rule: no one starts a payment without confirming the amount, no one treats a screenshot as final proof, and no one leaves the account open after the shift. These rules cost nothing and make a phone-based setup much less dependent on memory.
For customers, clarity matters too. I would say the amount aloud before completing the sale and let the customer see the relevant confirmation without exposing unrelated account information. This creates a cleaner interaction and reduces the chance that a hurried tap turns into an incorrect charge.
Where Jim is stronger than usual alternatives
Compared with cash, Jim removes the need for the customer to carry the exact amount and can make an informal sale feel more complete. Compared with asking for a later transfer, an immediate card workflow can reduce the risk of forgotten payments. Compared with a traditional terminal, the phone format is easier to carry and may be more suitable for sellers who do not need a permanent checkout.
Its strongest use case is therefore occasional or mobile selling. I would recommend considering it for a person who already owns a compatible Android phone and wants to accept card payments without adding a separate terminal to every outing. The fewer objects I need to transport, the easier it is to set up a temporary sales point.
Where another option may be better
Jim is not automatically the best choice for a full retail operation. If I needed inventory control, employee permissions, detailed receipts, integrated accounting, advanced reporting, or a checkout shared by several workers, I would look at a broader point-of-sale platform. A phone card reader can solve payment acceptance without solving the rest of the business.
I would also compare it with a dedicated terminal if my work involved a long queue, heavy daily usage, or a phone that must remain available for calls and customer messages. Separating business payments from personal phone use can be worth the extra equipment. The right decision depends less on the headline convenience and more on how often I sell and how costly interruptions would be.
Cash remains useful as a backup, particularly in places where connectivity or battery life is unpredictable. I would not abandon every alternative after installing Jim. A practical seller can use the app as the main option while keeping a clear contingency plan for a dead battery, a damaged phone, or a customer who cannot complete the preferred payment method.
Small workflow details that make a difference
One non-obvious benefit of a mobile reader is that it can change how I organize the selling area. I would keep the phone in a consistent position, away from loose merchandise and drinks, and make the payment step visible but controlled. That reduces the chance of dropping the device or letting a customer accidentally navigate away from the transaction screen.
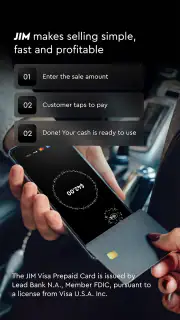
I would separate product selection from payment confirmation. First I would agree on the item and total, then enter or review the amount, then let the customer complete the payment. Mixing those stages while answering questions or packing goods is an easy way to make an avoidable mistake.
Another useful trade-off is speed versus verification. The app’s purpose is quick payment, but I would not sacrifice a clear completion check to save a few seconds. For low-value, familiar sales, the routine may feel nearly instant. For higher-value purchases, I would spend the extra moment reviewing the amount and status.
Finally, I would review the day’s transactions while the details are still fresh. If a customer asks about a payment later, a same-day check is easier than trying to remember a crowded event. This turns Jim from a simple acceptance tool into one part of a more disciplined sales process.
Who should install it?
I think Jim is worth considering for independent sellers, service providers, and small operators who want a lightweight way to accept card payments from an Android phone. It is especially appealing when sales happen in changing locations and the seller already values a compact setup.
I would be more cautious if the phone is old, shared by a family, used heavily for unrelated work, or regularly short on battery. I would also hesitate if the business needs a complete register rather than a payment reader. In those cases, a dedicated terminal or a broader retail system may provide a better fit even if it costs more or requires extra equipment.
The Everyone age rating makes the app broadly accessible, but adults responsible for a business should still establish their own account and device rules. An age classification does not replace careful handling of financial access, customer information, and transaction records.
My cautious verdict
After looking at Jim as a real selling tool, I see a focused app with a compelling idea: make card acceptance available through a phone instead of forcing every seller to carry a separate terminal. Its free price lowers the barrier to trying that approach, and CloudWalk’s app has already reached over 100 thousand installs with a 4.3 average, giving it a visible user base.
My recommendation comes with a condition: test it before depending on it. Confirm that the Android phone works comfortably, learn where transaction status is shown, review the permissions and privacy choices presented during setup, and establish a backup plan. Those steps matter more than simply installing the latest version.
Jim is a good fit when portability and straightforward card acceptance matter more than a complete point-of-sale system. I would recommend it to a mobile seller who wants to keep equipment minimal and is willing to manage phone security, battery life, connectivity, and transaction checks responsibly. I would skip it in favor of a dedicated terminal or full retail platform when the business needs advanced controls, multiple operators, or an uninterrupted high-volume checkout.
In short, I would treat Jim as a practical payment component, not as the entire business setup. Used with deliberate account habits and a simple sales record, it can make small, location-flexible transactions easier. Its real test is not whether it sounds convenient, but whether its controls and confirmation steps remain clear when a real customer is waiting.
Pros
- Instant payment options help sellers access earnings quickly.
- Simple listing tools make it easy to upload and manage items.
- Built-in messaging supports direct communication with buyers.
- Useful for selling locally without complicated setup.
- Mobile notifications help users respond to offers promptly.
Cons
- Availability and features may vary by location.
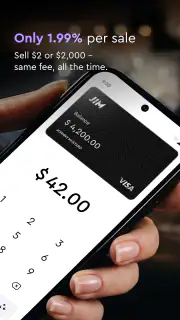
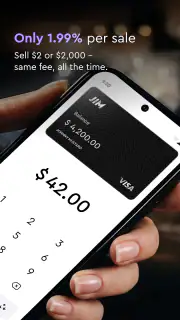
- Transaction fees can reduce the final amount received.
- Buyer and seller protection may have specific limitations.
- Some listings may attract spam or unreliable inquiries.
- A stable internet connection is needed for most actions.
FAQ's for Jim: sell & get paid instantly
What is Jim: sell & get paid instantly?
Jim: sell & get paid instantly is a marketplace app designed to help users list items for sale, communicate with potential buyers, and receive payment through the platform. Its main appeal is speed and convenience: instead of waiting for a traditional bank transfer or arranging complicated payment steps, sellers can manage listings and transactions from one mobile app. Availability and supported features may vary by location.
How do I sell an item using Jim?
To sell an item, you generally create a listing by adding clear photos, a title, description, price, and any relevant condition or delivery details. Accurate information is important because it helps buyers understand what they are purchasing and reduces misunderstandings. After publishing the listing, you can respond to inquiries, agree on the transaction details, and complete the sale through the available in-app process.
Do sellers really get paid instantly?
The app is built around fast payments, but the exact meaning of “instantly” can depend on the payment method, account verification, banking provider, country, and transaction status. Some payments may appear immediately, while others can require processing time or additional checks. Before selling, review the payment terms shown in the app and confirm when funds become available for withdrawal or use.
Is Jim safe to use for buying and selling?
Jim may provide tools intended to make transactions more convenient, but users should still follow basic marketplace safety practices. Keep communication and payment activity inside the official app whenever possible, avoid sharing unnecessary personal information, and be cautious of buyers or sellers who pressure you to move elsewhere. Check item details carefully, use secure meeting arrangements, and report suspicious behavior through the app.
Is Jim available on Android and iPhone, and does it cost anything?
Availability, supported devices, and pricing can change over time, so users should check the official Google Play Store or Apple App Store listing before downloading. The app may be free to install, but certain transactions, payment services, delivery options, or premium features could involve fees. Read the current terms, seller charges, and privacy information carefully before completing a sale.