
Split Pay: Split Bills in Two
Android OnlyFree·User Rating
 Analysis by ViaAPK
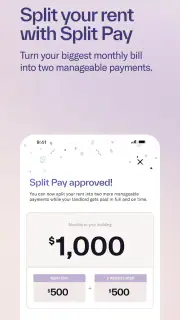
Managing a large payment is rarely difficult because of the arithmetic. The awkward part is usually timing: rent is due before payday, a mortgage withdrawal lands alongside other bills, or a car payment makes one week much tighter than the next. Split Pay is a finance app from Split Pay built around that specific problem. Its store summary focuses on rent, mortgage, and car payments, while the short description keeps the idea deliberately simple: Split Pay.
I approached it as a practical cash-flow tool rather than a general budgeting app. That distinction matters. It is not trying to replace a full spending tracker, and it is not the same as asking a friend to cover a bill informally. The useful question is whether dividing a major payment into smaller parts makes a real difference for your month, and whether the process feels clear enough to trust.
The app is free, carries an Everyone age rating, and has reached over 100 thousand installs. Its average rating is 4.8 from around 3.3 thousand ratings, with 462 written reviews. Those figures suggest that the central idea is resonating with a meaningful group of users, but they do not remove the need to understand the workflow. A payment app can be appealing in principle and still be a poor fit if its timing, handoffs, or conditions do not match your situation.
How the payment workflow feels from start to finish
I find the workflow easiest to judge by following one recurring bill all the way through, rather than focusing only on the first smaller payment. The useful test is whether each step stays understandable while I keep the full obligation and due date in view. That leads naturally to the next question: how the process holds up when several financial demands compete for attention.
Beginning with the payment that causes the squeeze
The most sensible way to use this app is to begin with one known, recurring obligation rather than treating it as a place to manage every financial decision. I would start with the payment that creates the clearest cash-flow problem: perhaps rent arriving before a salary deposit, a mortgage payment that dominates the first week of the month, or a vehicle payment that competes with groceries and utilities.
That starting point creates a useful boundary. Instead of opening the app with a vague goal such as “get better with money,” I can ask a concrete question: will splitting this particular payment make the month easier without creating a larger problem later? If the answer is yes, the app’s purpose is immediately understandable. If the payment is already comfortable, adding another step may not be worthwhile.
I also recommend deciding the maximum amount I can comfortably commit before beginning. A split arrangement should improve timing, not encourage me to promise money I do not have. This is one of the less obvious trade-offs: a smaller payment today can feel easier, but the full obligation still exists. The app can organize the movement of money; it cannot make an unaffordable bill affordable.
News Worth Your Time
Brain Test 2 Suits the Stop-and-Start Rhythm of Modern Phones
Google Play Games Makes Android Gaming Easier to Navigate, Not Easier to Love
WhatsApp Under Pressure: How Well It Recovers When Messages Fail
UNO!™ Beyond the Table: How Rivalry Keeps Players Coming Back
LinkedIn: Dominating the Professional Networking Arena
Unlocking the Full Potential of Pixel Art - Color by Number
Roblox: A Creative Revolution in Gaming
Why Gallery Stands Out in the Photo App World
How Pi Network is Revolutionizing Social Cryptocurrency
Google TV's Ecosystem Strategy: Redefining Streaming
How Little Panda: Princess Makeup Thrives with New OS Updates
Why Decor Life - Home Design Game Stands Out in Creative Simulation
For renters, this can be especially useful when income arrives on a different schedule from the lease payment. A person paid twice a month may prefer to align the housing cost with both pay periods instead of watching one large withdrawal consume a single deposit. For a mortgage or car payment, the same thinking applies, although the consequences of a missed or late obligation may be more serious. I would therefore use the app as a timing aid, not as permission to delay a payment without checking the underlying agreement.
Moving through the setup without losing the real deadline
The next stage is entering the payment details and following the app’s process for dividing the amount. I found that the important mental shift is to focus on the final due date, not merely the first smaller amount. A good setup is one where I can explain the whole sequence in plain language: what the original obligation is, what gets handled first, what follows, and when the recipient should regard the bill as settled.
That explanation is also a useful personal test. If I cannot describe the schedule clearly after setting it up, I should pause before relying on it. Financial tools deserve a slower review than ordinary productivity apps because a confusing screen can lead to a missed deadline, duplicate action, or false confidence that a payment has completed.
One practical habit is to compare the app’s schedule with my bank balance on each relevant payday. I would not simply set it and forget it. I would check that the planned amount still fits after essentials such as food, utilities, and transport. This is a concrete advantage of thinking in workflow terms: the setup is not the outcome. The outcome depends on the later handoffs and on whether the money is available when each part is due.
The current version is 2.0.4, and the app requires Android 10 or later. That makes compatibility worth checking before planning around it, particularly on an older phone that is still reliable for banking. The app is available at no charge, which lowers the barrier to trying the process, but “free” should not be confused with “risk-free.” The financial commitment remains the payment itself, and I would still read each confirmation carefully.
Understanding the handoffs between me, the app, and the bill recipient
The most important part of this kind of service is not the first tap. It is the handoff. There is me, the app, the account or payment method involved, and the landlord, lender, or vehicle finance provider expecting the money. Each party needs to line up with the same timing.
In everyday use, I would treat the app as the coordinator of a payment plan rather than assuming the recipient sees the process exactly as I do. A landlord may care only that the complete rent arrives by the required date. A lender may have its own rules for posting payments. A car finance company may distinguish between a payment being initiated and a payment being credited. Those details make it important to verify the recipient’s expectation instead of relying only on an in-app status.
This is where Split Pay can be more useful than an informal arrangement with a friend. Asking someone close to cover part of a bill creates a social handoff: reminders, uncertainty, and the possibility that the other person needs the money back at the same time. A dedicated payment workflow gives the situation a clearer structure. However, it is still not identical to paying the bill directly through the recipient’s own portal. Direct payment may be preferable when the biller requires a specific reference, demands one complete transaction, or offers a better-established confirmation trail.
I would keep the recipient’s account information and due date available while using the app, especially for the first cycle. If the payment is time-sensitive, I would also retain the confirmation or record supplied by the relevant service. That is not unnecessary caution; it is a way to separate “the app accepted my request” from “the biller has credited my account.” The difference can matter when a deadline is close.
What the result looks like when the plan works
The best result is not simply seeing a smaller amount leave at the beginning. It is reaching the due date without having to scramble, borrow from a friend, or choose between housing and other essentials. For someone paid on a regular schedule, splitting a large obligation can make the month feel more predictable because the cost is distributed across the available cash-flow points.
Consider a realistic example. I receive income twice during the month, but my rent is due near the beginning, when the previous month’s expenses have already reduced my balance. Rather than waiting until the deadline is close, I use the app to structure the payment around the money I expect to have available. I then check the later portion against the second income date and keep enough aside for ordinary spending. The benefit is not that the rent became cheaper. The benefit is that the payment no longer collides with one unusually expensive week.
That distinction makes the app most attractive to people with predictable income and a clear recurring bill. It may also help households where one person handles the payment but wants a more disciplined way to reserve money over time. The workflow can act like a commitment device: once the plan is arranged, the payment receives attention before discretionary spending does.
For a mortgage or car payment, the result should be judged more conservatively. These obligations can involve stricter consequences, so I would want a reliable understanding of when the payment is considered complete. If there is any uncertainty, paying through the lender’s established channel may be the safer choice. Split Pay is strongest when the timing problem is the main obstacle and the payment arrangement is compatible with the recipient’s expectations.
Where the flow becomes uncomfortable or breaks down
The first weakness is that splitting a payment can create a false sense of extra money. Seeing a smaller initial amount may make the month look healthier than it really is. I have to mentally reserve the remaining obligation, otherwise the app solves one timing problem while creating a later shortage. This is why I would avoid using it for several major bills at once until I had seen how one complete cycle behaves.
A second friction point is any mismatch between the app’s process and the biller’s rules. If a landlord accepts only one full rent payment, or a lender posts funds according to its own schedule, the convenience of splitting may disappear. The app cannot override those requirements. In that situation, a conventional bank transfer, the provider’s payment portal, or a carefully planned savings pot may be better.
A third issue is irregular income. Freelancers, seasonal workers, and people whose hours vary may not benefit from a fixed split unless they already maintain a reliable buffer. The app can divide the obligation, but it cannot predict whether next week’s income will arrive. For those users, a flexible emergency reserve or a broader budgeting system may provide more protection than a payment-specific tool.
There is also a behavioral risk for people who already have several scheduled withdrawals. Adding another payment layer can make the calendar harder to understand. My practical advice is to use one recurring obligation first, label the purpose clearly in my own records, and review the account before every handoff. If the process requires constant mental translation, the convenience is probably not worth it.
How it compares with ordinary alternatives
The usual alternative is to pay the bill directly from a bank account. That is often the cleanest approach when the money is already available, the recipient’s portal is dependable, and a single payment is required. Direct payment has fewer moving parts and usually makes the relationship between the biller and the payer easier to verify.
Another alternative is a budgeting app or spreadsheet. Those tools can help me set aside money gradually, but they generally leave the final payment entirely in my hands. Split Pay is more focused: instead of only showing that I should reserve money, it is designed around dividing a major payment into a more manageable flow. The trade-off is narrower scope. Someone seeking category budgets, spending reports, savings goals, and a complete financial overview may find a general budgeting tool more useful.
Borrowing from a friend or family member can be fast, but it introduces personal pressure and an informal repayment promise. The dedicated structure here is preferable when I want the arrangement to be tied to the bill rather than to a relationship. Still, informal help may be better in a genuine emergency if it avoids a deadline problem and carries no confusing payment handoffs.
Finally, saving into a separate account before the due date can achieve a similar result without adding a payment service to the chain. That method offers maximum control, but it depends on discipline. Split Pay is more compelling for someone who repeatedly intends to reserve money and then spends it elsewhere. It is less compelling for a person who already manages a reliable bill calendar and prefers the fewest possible financial intermediaries.
Who should try it, and who should skip it
I would recommend trying Split Pay if a large recurring payment regularly arrives at the wrong point in the month, income is reasonably predictable, and I am willing to monitor the later handoffs. Rent is the clearest use case because housing costs are large, recurring, and often difficult to move around. The same applies to a mortgage or car payment when the arrangement fits the recipient’s process and the user can keep the full obligation covered.
I would skip it for a one-off crisis if I had no realistic plan for the remaining balance. I would also be cautious if my income changes sharply, my account is already crowded with automatic payments, or the biller has strict rules about payment timing and posting. In those situations, direct communication with the provider, a conventional payment route, or help from a qualified financial adviser may be more appropriate.
My final recommendation is to treat the first use as a controlled trial. Choose one payment, read every confirmation, note when each handoff occurs, and compare the result with the biller’s own record. If the process reduces stress without making the schedule harder to understand, the free app earns a place in the monthly routine. If it merely makes the obligation look smaller while adding uncertainty, direct payment or a simple savings plan is the better answer.
Overall, Split Pay is a focused finance app with a clear practical purpose. I like it most as a cash-flow organizer for people who know exactly which large payment is causing the squeeze. Its strength is the structured path from one major obligation toward smaller, more manageable steps. Its limitation is equally clear: the user still has to understand the full commitment, protect the later funds, and make sure the recipient accepts the arrangement. Used with that discipline, it can make a difficult payment feel more orderly without pretending that the underlying cost has disappeared.
Pros
- Quickly divides bills between two people
- Useful for meals
- rent
- trips
- and shared purchases
- Simple interface with minimal setup required
- Helps avoid awkward payment calculations
- Reduces mistakes when splitting equal expenses
Cons
- Limited usefulness for groups larger than two
- May not support every local currency or payment method
- Manual entry is still needed for some expenses
- Does not guarantee that the other person will pay
- Features may vary between Android and iOS versions
FAQ's for Split Pay: Split Bills in Two
What is Split Pay: Split Bills in Two, and how does it work?
Split Pay: Split Bills in Two is designed to help you divide shared expenses between two people without calculating every item manually. After entering the bill amount, users can generally choose an equal or customized split, review the totals, and see how much each person should pay. It is useful for meals, rent, shopping, travel costs, and other everyday expenses.
Can I split a bill unevenly with Split Pay?
Yes, the app is intended to support more than a simple 50/50 division. You can adjust the amounts when one person paid for extra items, ordered a more expensive meal, or needs to cover a different share of the total. Before confirming the calculation, check that the individual amounts add up correctly, especially when tips, taxes, discounts, or service charges are included.
Does Split Pay include tips, taxes, discounts, or additional charges?
Split Pay can be used to calculate a final bill that includes extra costs, but the exact method may depend on the version of the app and the options available on your device. The safest approach is to enter the complete amount shown on the receipt, including tax and tip, or add those charges before dividing the bill. Always compare the result with the original receipt.
Does Split Pay: Split Bills in Two require an internet connection?
For basic bill calculations, an internet connection may not be necessary because the main function can work locally on the device. However, internet access could be required for downloading the app, receiving updates, displaying advertisements, or using any sharing-related features connected to external services. If you plan to use it in a restaurant or while traveling, test the app offline beforehand.
Is Split Pay safe to use, and does it store my financial information?
The app is primarily a calculation tool, so you normally do not need to enter bank details, card numbers, or payment credentials simply to divide a bill. Nevertheless, privacy practices can vary by platform version, advertising provider, and app update. Before downloading, review the permissions and privacy policy listed in the Google Play Store or Apple App Store, and avoid entering sensitive personal information.